
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
FuelCell Stock Just Scored a New Bullish Rating. What to Know.
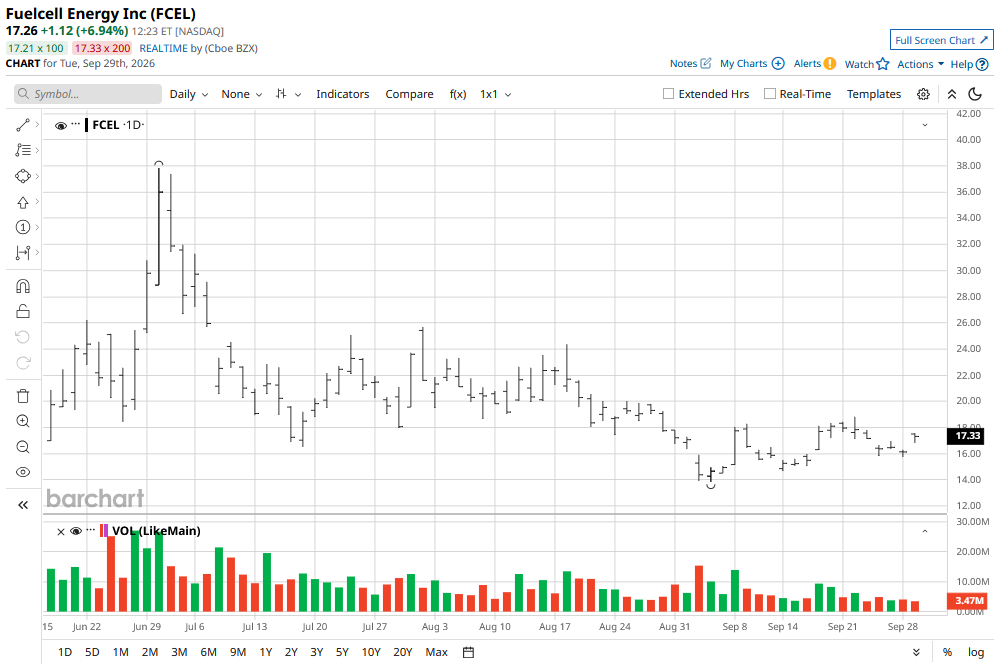
FuelCell Energy (FCEL) shares are inching higher on Tuesday morning after Oppenheimer’s lead analyst Colin Rusch initiated coverage with an “Outperform” rating. In his research note, Rusch assigned a bullish $24 price target on FCEL, indicating the clean energy technology company could rally nearly 50% from its previous close.
FuelCell stock performance has been nothing short of impressive in 2026, even though it currently sits at less than half its price in late June.
Why Is Oppenheimer Bullish on FuelCell Stock?
Rusch’s bullish thesis on FCEL shares hinges primarily on the explosive power demand as AI data centers continue to face severe electric grid connection delays.
According to him, FuelCell is positioned as a “differentiated provider of firm, on-site power for data center build-outs,” enabling enterprise customers to bypass multi-year interconnection queues.
Market interest is already accelerating rapidly; FCEL wrapped up its fiscal Q3 with an expansive sales pipeline exceeding 10 gigawatts, 97% of which is tied directly to data center infrastructure.
The analyst also noted that commercial traction is materializing through concrete commitments, including a framework agreement with Fit Energy for up to 380 MW and a capacity reservation deal for 75 MW.
FCEL Shares to Rally as Operating Leverage Unlocks
To meet this burgeoning demand, FuelCell plans to scale its Torrington manufacturing facility from about 40 megawatts to as much as 100 megawatts within the next few months. In fact, the clean energy company is aiming for 500 MW by fiscal 2029.
Oppenheimer expects this multi-fold expansion to “unlock significant operating leverage,” driving revenues from $158 million last year to $932 million by the end of this decade.
With $658 million in unrestricted cash and over $3.65 billion in total backlog, FCEL has sufficient liquidity to navigate its expected $200 million to $275 million expansion cost, the firm told clients.
Rusch sees gross margins turning positive in late fiscal 2027, setting the stage for a notable recovery in FuelCell shares.
Wall Street’s View on FuelCell Energy
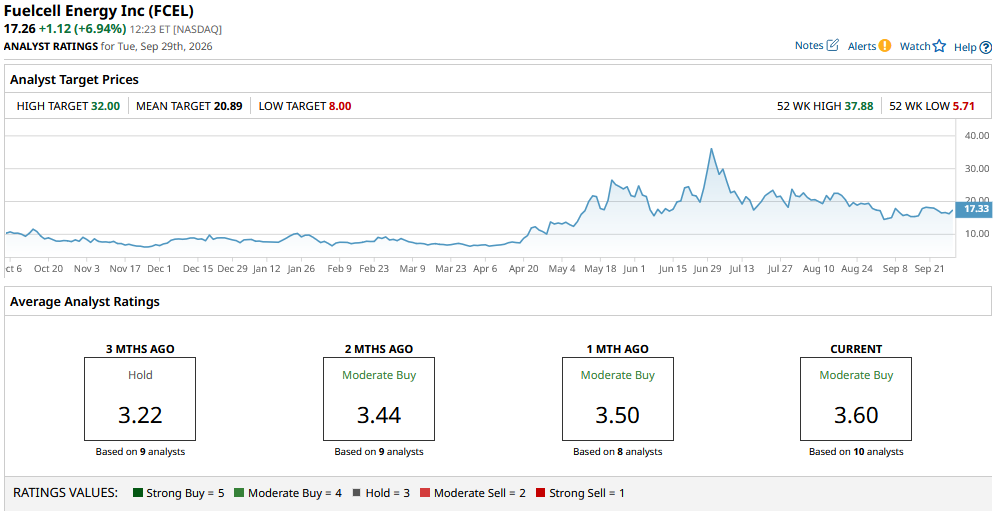
While not nearly as bullish as Oppenheimer, other Wall Street firms also remain positive on FCEL stock for the remainder of 2026.
The consensus rating on FuelCell Energy sits at “Moderate Buy” currently, with the mean price target of nearly $21 indicating potential upside of more than 20% from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.