
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Could Louisiana LNG Contract Change The Bull Case For Maire Stock?
- Maire’s subsidiary Tecnimont USA Inc. previously signed a Front End Engineering Design contract with Argent LNG for a planned LNG export facility in Louisiana, covering FEED work, permitting documentation, and support for the Federal Energy Regulatory Commission process.
- The FEED role gives Maire early involvement in a United States LNG export project, which can shape project specifications, execution scope, and potential follow on engineering, procurement, and construction opportunities if Argent LNG proceeds after a final investment decision.
- We will now look at how Maire's investment narrative could be affected by Tecnimont USA's FEED role in Argent LNG's Louisiana project.
Scan how Maire’s LNG and AI angle compares with other infrastructure focused plays by reviewing our curated list of 39 power grid technology and infrastructure stocks in one place.
Maire Investment Narrative Recap
Maire appeals to investors who buy into an energy transition contractor that still earns most of its money from traditional EPC work, while gradually building higher margin, technology led services. The short term story hinges on execution quality across big projects and how consistently that €15.7b backlog turns into cash flow without nasty cost overruns.
The Argent LNG FEED award looks directionally positive for Maire’s US footprint but does not fundamentally change the near term risk and reward profile. The bigger swing factor remains exposure to fossil linked spending and complex geographies, balanced against earnings that analysts expect to grow and a P/E below both Italian market and peer averages.
The AI partnership with Octave Intelligence feels most relevant when thinking about Maire’s ability to manage that growing backlog. Multi agent software tied into long cycle engineering work can, if executed well, help improve schedule visibility, permitting workflows and risk management on projects such as Argent LNG.
For you as a shareholder, the interest is practical. Better digital tooling could support the shift toward higher quality earnings from technology licensing and services while also limiting the chance of cost blowouts on complex EPC work in regions like Central Asia or Africa. The flip side is execution risk on the digital roll out itself and the opportunity cost if peers move faster.
Maire’s Analyst Case In One Line
Maire's current analyst storyline points to €8.6b in revenue and €381.4m in earnings by 2029, based on an assumed 6.4% yearly increase in revenue and an earnings rise of about €115m from €266.1m today.
Uncover why Maire's fair value indicates a 39% potential upside to its current price that could narrow quickly.
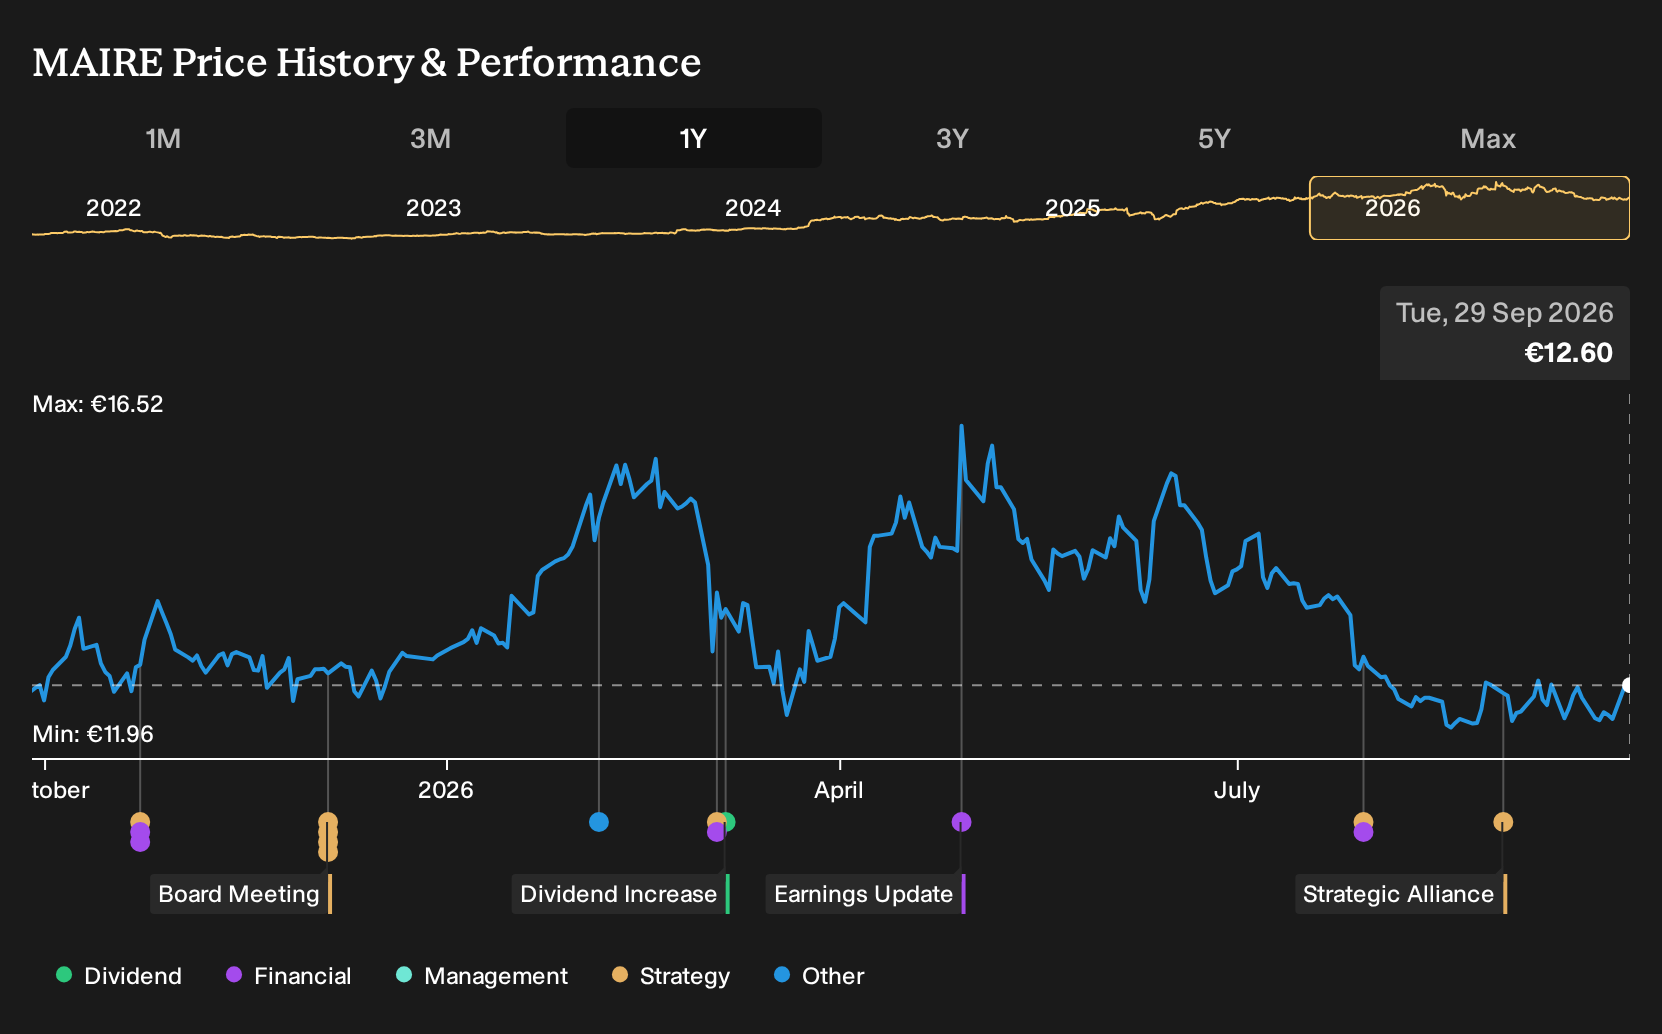
Exploring Other Perspectives
The five fair value estimates from the Simply Wall St Community span roughly €8.89 to €17.46, so some retail investors see Maire as priced for modest outcomes while others pencil in almost double that. Before the Argent LNG FEED and AI rollout fully play through, consider how execution risk, fossil exposure and digital adoption could push these opinions even further apart.
Explore 4 other Maire fair value estimates, including one that suggests as much as 39% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Maire research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Maire. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Maire's overall financial health at a glance.
Looking for more ideas beyond Maire?
If the Maire story has sharpened your thinking about risk, return and project quality, it can help to line it up against other opportunities using the Simply Wall St Screener. That way you can stress test whether the trade off you see in Maire still appeals once you compare it with businesses that have different balance sheet strength, payout profiles or valuation setups.
- If capital preservation comes first for you, start by reviewing a curated group of resilient businesses in the 225 resilient stocks with low risk scores that keep overall risk scores in focus.
- If your priority is long term value, benchmark Maire against the 202 high quality undervalued stocks that blend solid cash generation with what looks like a discounted price.
- If steady income is a core part of your plan, round out your watchlist with the 164 dividend fortresses where yield and durability go hand in hand.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com