
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Monolithic Power Systems (MPWR) Could Be 27% Undervalued Following GLOBALFOUNDRIES Deal
Investor attention around Monolithic Power Systems (MPWR) has sharpened after its long-term manufacturing agreement with GLOBALFOUNDRIES, which expands access to 300mm capacity in Singapore for power management chips serving targeted high growth markets.
Recent trading shows that momentum in Monolithic Power Systems is still alive, with a year to date share price return of 44.31% sitting alongside a 1 year total shareholder return of 53.47%, even though the 90 day share price return has eased 2.25% ahead of this manufacturing deal.
Scan other power and chip players riding similar manufacturing and AI infrastructure trends by checking our hand picked list of 88 AI infrastructure stocks alongside Monolithic Power Systems.
The GLOBALFOUNDRIES deal and a share price near US$1,351 put Monolithic Power Systems squarely in the spotlight. After such a strong run, does the current valuation still skew the risk and reward toward new buyers?
Most Popular Narrative: 27% Undervalued
On the most followed narrative, Monolithic Power Systems screens as undervalued, with a fair value of $1,842.64 set against a last close of $1,351.20. That gap rests on a very specific view of how AI data centers and automotive power needs reshape the earnings profile over the next several years.
Monolithic Power Systems is attaining major design wins with multiple large, blue-chip customers in the rapidly growing AI and ASIC data center market, and is benefiting from secular multi-year expansion in AI, machine learning, and power-hungry architectures, which is viewed as a structural tailwind for power management IC suppliers that could support robust, sustained top-line growth. There is sustained strong momentum in the automotive segment, with content per vehicle rising due to adoption of 48-volt and zonal architectures, and MPS is set to benefit further as electrification and digitalization accelerate across the auto industry. This can provide a reliable and high-growth revenue stream for the company over several years.
See why 80 investors see Monolithic Power Systems as 27% undervalued.
Result: Fair Value of $1,842.64 (UNDERVALUED)
Still, the bullish Monolithic Power Systems narrative could crack if AI data center demand cools or if rising manufacturing and R&D costs squeeze those premium margins.
Find out about the key risks to this Monolithic Power Systems narrative.
Another View: Monolithic Power Systems Through A P/E Lens
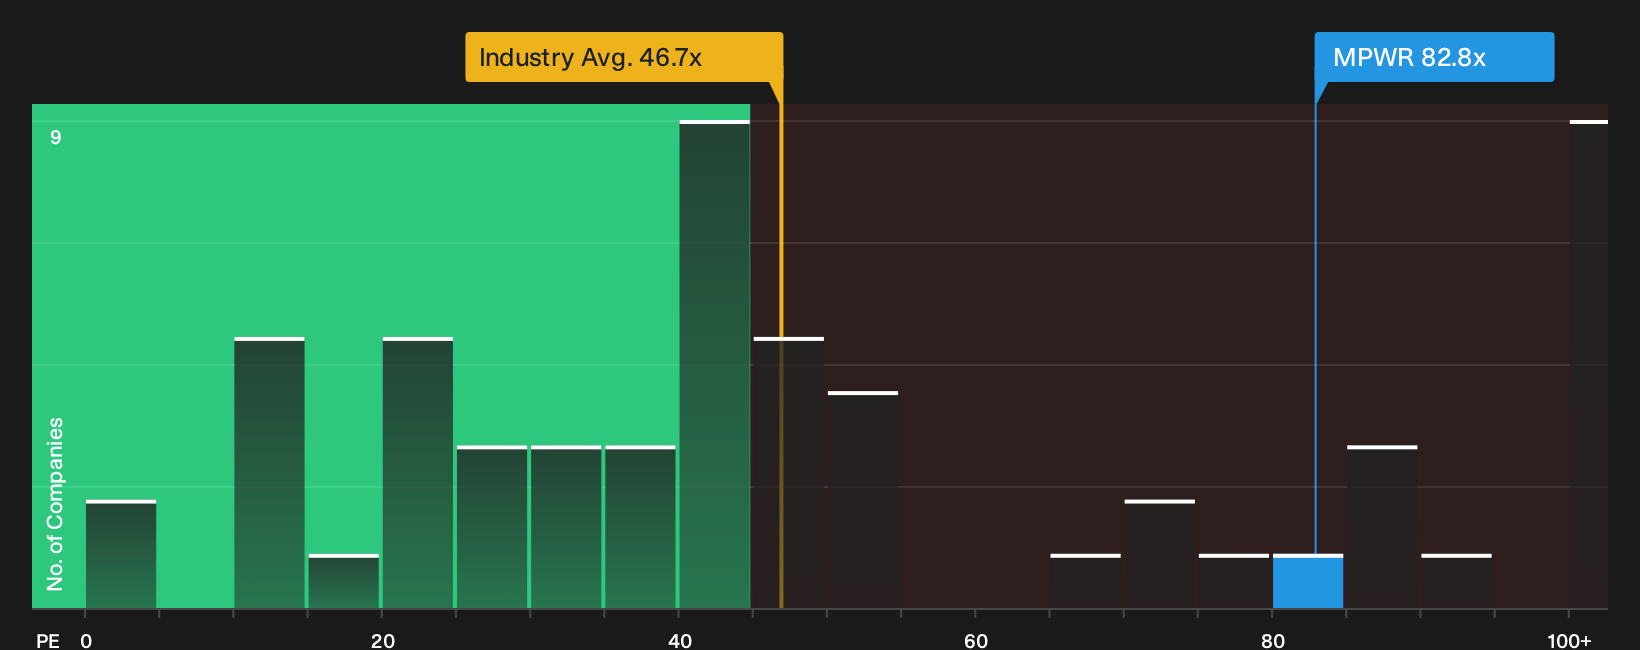
The SWS fair value narrative points to upside, yet the current P/E of 82.8x paints a very different picture for Monolithic Power Systems. That multiple is far above the US Semiconductor industry at 46.7x and well ahead of the fair ratio of 35.6x that the market could move toward.
If pricing drifts closer to either peers or the fair ratio, the valuation gap would close through the share price rather than earnings alone. This raises real risk for anyone paying today’s multiple. Is this premium a cushion of quality, or is it simply a thin layer over valuation downside?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment on Monolithic Power Systems split between rich valuation and AI upside, it makes sense to move quickly and look at the underlying data yourself. To weigh both the optimism and the concerns in one place, review the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Monolithic Power Systems?
If you stop with Monolithic Power Systems, you risk missing opportunities that fit your style even better, so give yourself options and scan a few focused lists.
- Target stability and income by reviewing a curated group of 6 dividend fortresses that aim to combine yield with resilience.
- Hunt for quality at a sensible entry point by checking a focused set of 32 high quality undervalued stocks backed by solid fundamentals.
- Prioritize capital preservation by assessing 30 resilient stocks with low risk scores that score well on financial strength and downside resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com