
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Could Micron Technology (MU) Reshape Syracuse With A $100 Billion Chip Megafab?
- Micron Technology (NasdaqGS: MU) has committed more than US$100b to a semiconductor megafab project in the Syracuse, New York area.
- The planned complex is described as one of the largest semiconductor manufacturing sites in U.S. history, with multiple advanced memory chip fabrication plants.
- Local and federal officials have framed the Syracuse megafab as a pillar of U.S. semiconductor reshoring and a potential Rust Belt jobs catalyst.
- Micron's Syracuse megafab plan, and what it could mean for American reindustrialization, needs to be weighed alongside the rest of our findings. Check out 3 warning signs (1 major) that Micron Technology investors should know about.
This reshoring push is not limited to Micron, so it is worth looking at other businesses tied into AI-focused manufacturing and infrastructure exposure through 88 AI infrastructure stocks.
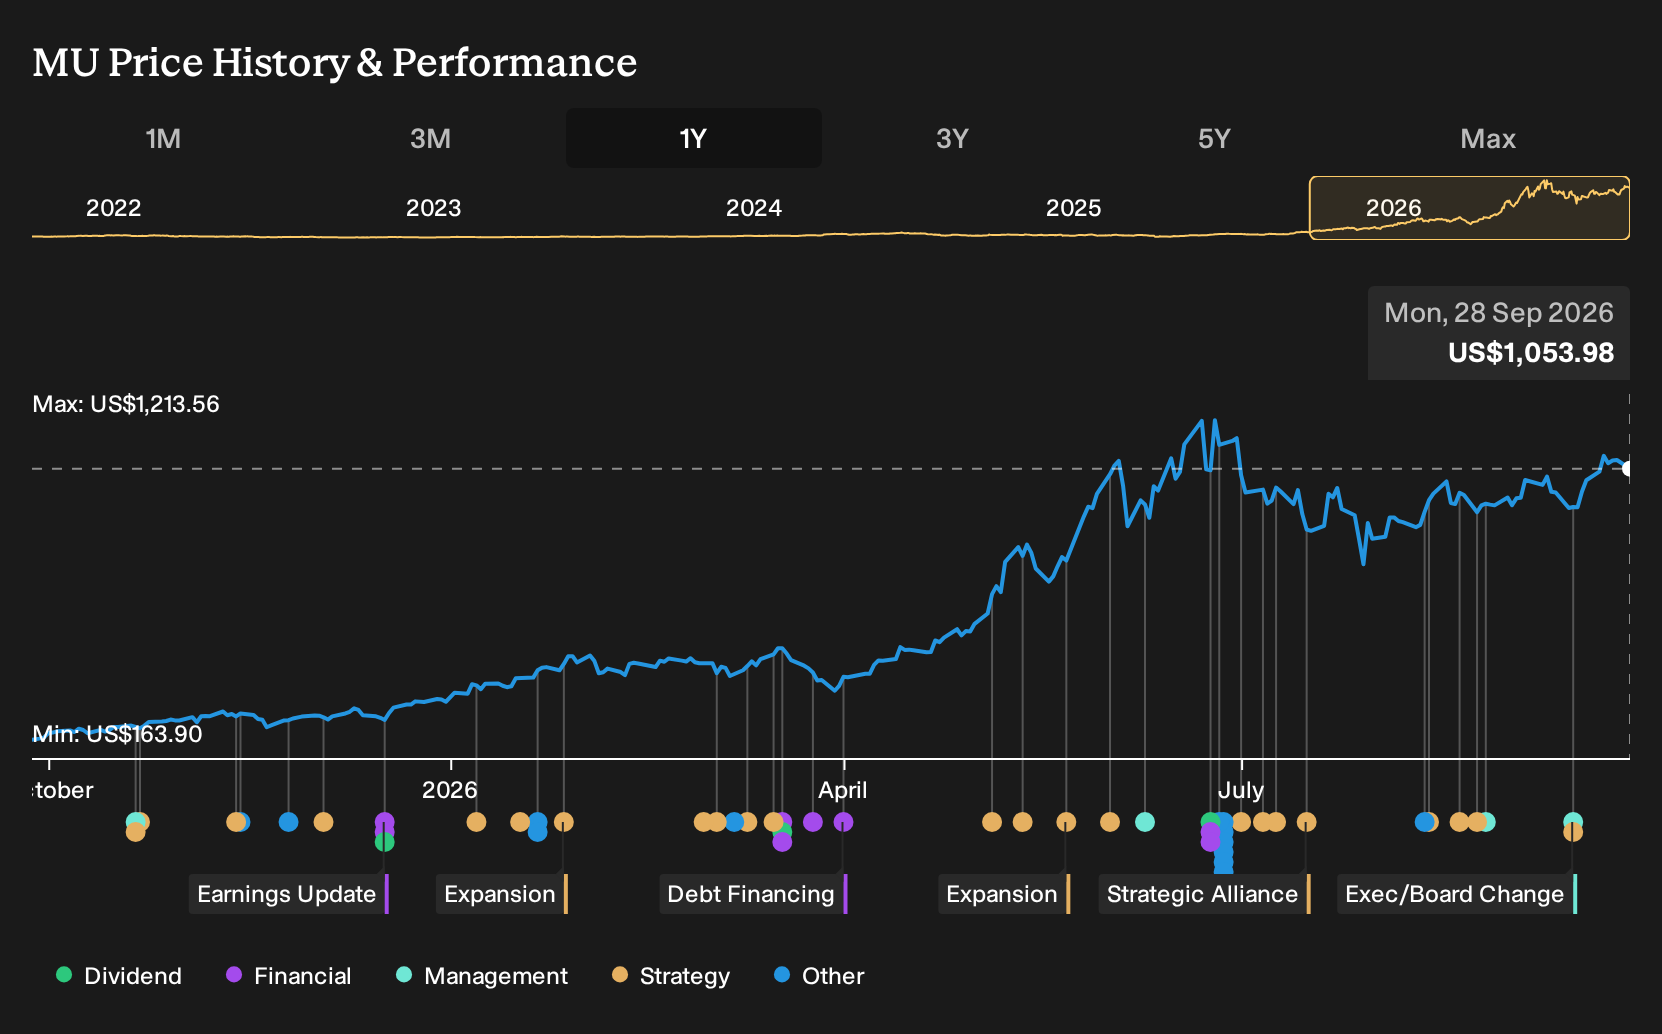
Micron Technology manufactures memory and storage products used in data centers, AI hardware, consumer devices, and industrial equipment. A large U.S. fabrication hub directly targets those high‑demand end markets. With a market cap of US$1.2 trillion, the company already ranks among the larger semiconductor producers globally, which shapes both the scale and expectations around a megaproject of this size.
Micron’s Syracuse megafab leans into the AI memory supercycle, but magnifies cycle risk
The Syracuse build strengthens the bull case in Micron’s Narrative that long term AI and data center demand can justify heavy U.S. capacity, particularly for DRAM, HBM and DDR5 that are already central to the thesis. A committed multi decade megafab lines up with the view that AI driven memory use and a shift toward higher value products can support margins and capital returns if demand stays close to analyst assumptions. It also fits the idea that management is willing to invest aggressively behind long horizon capacity and research, especially with Micron Research Labs now moving from launch toward execution under Deirdre Hanford.
See how these catalysts shape Micron Technology's path to a $1,507 fair value.
The same project also sharpens the bear argument from the Narrative that historically high capital intensity can strain free cash flow if the memory cycle turns. The practical test will be Micron’s capex, utilization and pricing commentary over the next few fiscal years as Syracuse spending ramps, particularly whether DRAM and HBM contract structures still support the margin and profit assumptions analysts map out through 2029.
The one Micron check to run before you act on any headline
Before you make any move off the headlines, it is worth knowing that our checks on Micron Technology flag something important about how the headline profit figures are built underneath. See what our checks flag about the quality of Micron Technology's earnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com