
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Xenon Pharmaceuticals (XENE) Undervalued On Its FDA Filing And Psychiatry Trial Pause?
Xenon Pharmaceuticals (NasdaqGM:XENE) is back in focus after submitting a New Drug Application to the U.S. Food and Drug Administration for azetukalner in focal-onset seizures, while pausing enrollment in certain psychiatry trials to reassess dosing.
Recent trading shows how sensitive Xenon Pharmaceuticals has become to news flow, with the share price down 38.8% over the past month and 39.2% over the past quarter. Even though the 5 year total shareholder return is 16.6%, this points to longer term holders still being in positive territory, despite momentum fading in the short run as investors reassess both the NDA progress and the psychiatry dosing pause.
Scan 37 healthcare AI stocks that, like Xenon Pharmaceuticals, are working on neurologic and psychiatric treatments where fresh trial data and regulatory milestones can quickly reshape the story.
On one side, Xenon Pharmaceuticals now has an FDA filing supported by late stage epilepsy data and a pipeline that stretches across neurology and psychiatry. After a sharp share price reset, are investors getting that platform at a sensible price today?
Most Popular Narrative: 51.5% Undervalued
Against a last close of $36.72, the most followed fair value estimate of $75.69 implies that Xenon Pharmaceuticals is being priced at a steep discount, with the gap hinging on how investors view azetukalner and the broader ion channel portfolio.
Advancing azetukalner toward multiple late stage readouts in focal onset and generalized seizures positions Xenon to tap a growing pool of refractory epilepsy patients who need better tolerated, easy to use therapies. This supports a step change in revenue on approval and later expands earnings as fixed R&D is leveraged.
See why 1 investors see Xenon Pharmaceuticals as 51% undervalued.
On this framework, a discount rate of 7.27% is applied to analyst forecasts that reach $449.0 million of revenue and $79.2 million of earnings by 2029, with a future P/E of 139.3x used to justify the $75.69 fair value. The outcome is highly sensitive to those long range inputs, since Xenon Pharmaceuticals currently reports no revenue and a loss of $409.2 million, so even small changes in adoption, pricing or margin assumptions can swing the model meaningfully.
The same narrative recognises several counterweights, including forecasts that Xenon Pharmaceuticals remains unprofitable over the next 3 years, analyst expectations for share count to grow 7% a year, and recent insider selling, which all add execution and dilution questions to an already ambitious growth profile. Analyst price targets also span a wide $46 to $100 range, and the commentary flags that this dispersion reflects genuine disagreement on psychiatry optionality, reimbursement conditions and the pace at which a new CNS medicine can reach scale.
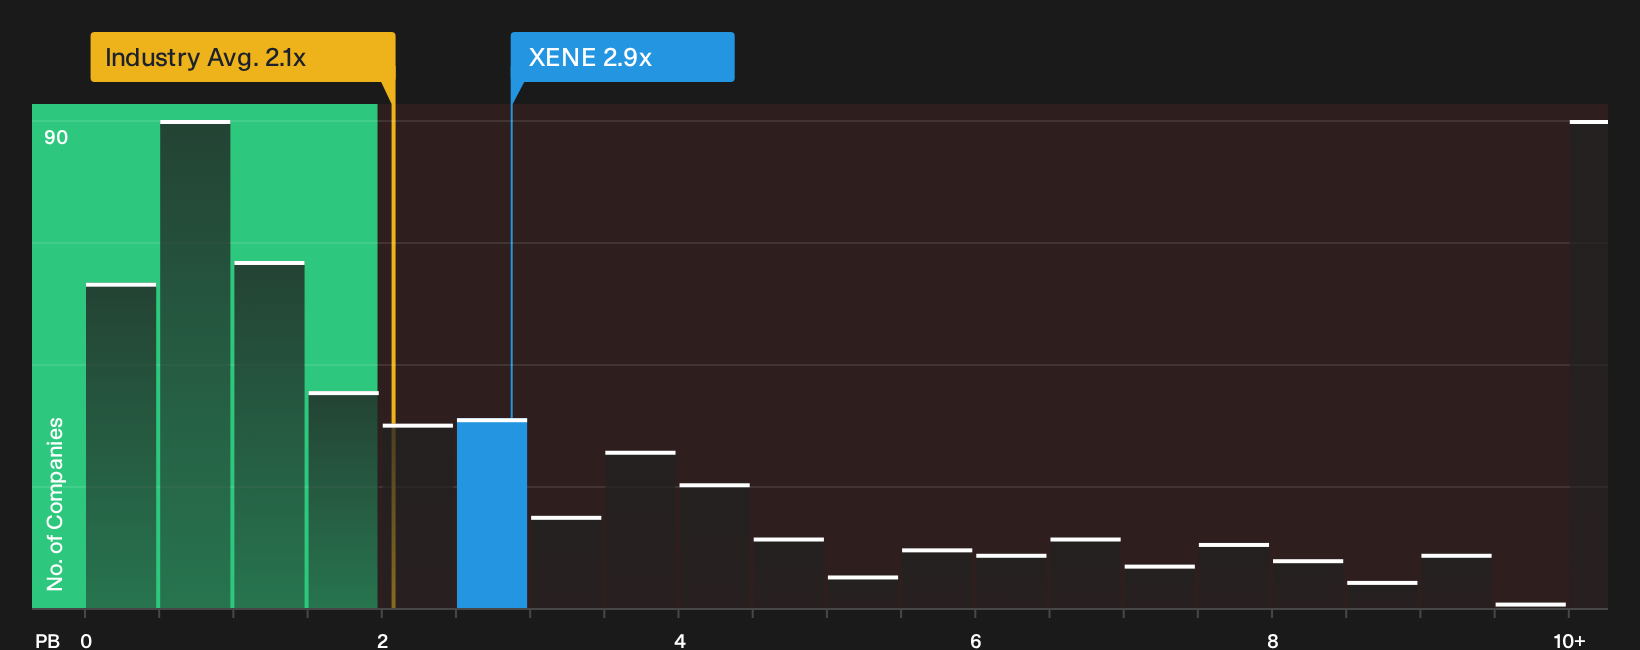
Compared with simple balance sheet indicators like the current P/B of 2.9x, which screens as expensive relative to the broader US biotech average of 2.1x, the fair value story here leans more on discounted future cash flows than on today’s reported metrics. The narrative effectively asks whether investors are comfortable underwriting a very large revenue ramp and a mid teens profit margin years out, in exchange for what the model views as a roughly half price entry point versus that $75.69 estimate.
Result: Fair Value of $75.69 (UNDERVALUED)
Still, the psychiatry enrollment pause and the wide analyst target range from US$46 to US$100 could both undermine confidence in the current Xenon Pharmaceuticals narrative.
Find out about the key risks to this Xenon Pharmaceuticals narrative.
Another View: Using Xenon Pharmaceuticals’ P/B Ratio
The earlier fair value story leans on long term cash flow forecasts. A simpler lens is the current P/B of 2.9x. That looks expensive versus the US biotech average of 2.1x, even though it screens cheap against closer peers at 21.4x.
This split suggests valuation risk cuts both ways if sentiment turns against high growth, loss making drug developers, and also if investors refocus on nearer term balance sheet metrics. Which yardstick do you trust more when none of the major trials has fully read out yet?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Xenon Pharmaceuticals can make the story feel unclear. Review the full picture quickly and form your own stance by weighing the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Xenon Pharmaceuticals?
Once you have a view on Xenon Pharmaceuticals, it can help to compare it with other opportunities that offer different mixes of risk, return, and income potential.
- Kickstart a watchlist of potential turnaround candidates by reviewing 7 elite penny stocks with strong financials that already show stronger fundamentals than most investors might expect.
- Bolt on potential value opportunities by scanning the 32 high quality undervalued stocks that combine solid cash generation with supportive balance sheets.
- Strengthen the income side of your portfolio by checking out 6 dividend fortresses that aim to pair higher yields with resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com