
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How New Robotics Deals At Medtronic (MDT) Have Changed Its Investment Story
- Medtronic received FDA clearance for its LigaSure RAS Maryland jaw device on the Hugo robotic-assisted surgery system, and Sonus Microsystems announced a collaboration with Medtronic to combine its AI-powered Sonus Patch with Medtronic acute care monitoring technology for maternal health studies in Kenya.
- The combination of a new U.S. cleared robotic instrument and a maternal health wearable ultrasound trial highlights Medtronic's efforts to broaden its surgical robotics tools while testing new, lower-cost care models in emerging markets.
- We will now look at how Medtronic's LigaSure Hugo integration could influence the broader investment narrative around its robotics ambitions.
Medtronic Investment Narrative Recap
To own Medtronic, you need to buy into a story of steady demand for devices in chronic disease and a long buildout in robotics, digital tools, and higher-margin therapies. The key near term swing factor remains execution on major product ramp ups like Hugo, CAS and new sensors while keeping gross margin pressure from mix and manufacturing in check.
The new LigaSure RAS clearance and the wearable ultrasound trial look additive rather than thesis changing. They feed into the robotics and AI angle but do not directly resolve underperforming units such as U.S. Diabetes or pockets of MedSurg softness, which still sit at the center of the current earnings risk.
The Cornerstone Robotics deal, with up to US$700 million committed to distribute the Sentire surgical system globally, connects most directly with Medtronic’s Hugo push. Investors watching robotics as a catalyst are likely to see the LigaSure Hugo integration and the Sentire distribution rights as part of a single execution test in soft tissue surgery.
That said, this broader robotics footprint also magnifies the same issues that already exist. Complexity in manufacturing, hospital adoption timing, and training needs all feed into the execution risk list that analysts have been flagging around Hugo and related platforms. The reward is a wider robotic ecosystem. The trade off is higher sensitivity to any missteps.
What The Medtronic Consensus Is Building In
Medtronic's consensus story leans on modest business expansion rather than a moonshot. Analysts are penciling in 4.5% yearly revenue growth over the next few years and expect earnings to move from US$4.8b today to US$6.6b by 2029. That is an earnings increase of about US$1.8b, with profit margins modeled to move from 13.2% to 15.8% as scale, mix and efficiency work through the income statement.
The same models point to 2029 revenue of US$41.5b. That top line, paired with the US$6.6b earnings estimate, implies a P/E of 24.4x on those future profits, compared with 21.5x on current earnings and below the cited 25.7x P/E level for the wider US medical equipment group. The forecast year is 2029 in both the revenue and earnings bridge, and the analysts are using an 8.6% discount rate for their scenario work.
Medtronic's narrative projects US$41.5b revenue and US$6.6b earnings by 2029. This requires 4.5% yearly revenue growth and an earnings increase of about US$1.8b from US$4.8b.
Uncover why Medtronic's fair value indicates a 9% potential upside to its current price, which could close faster than many investors expect.
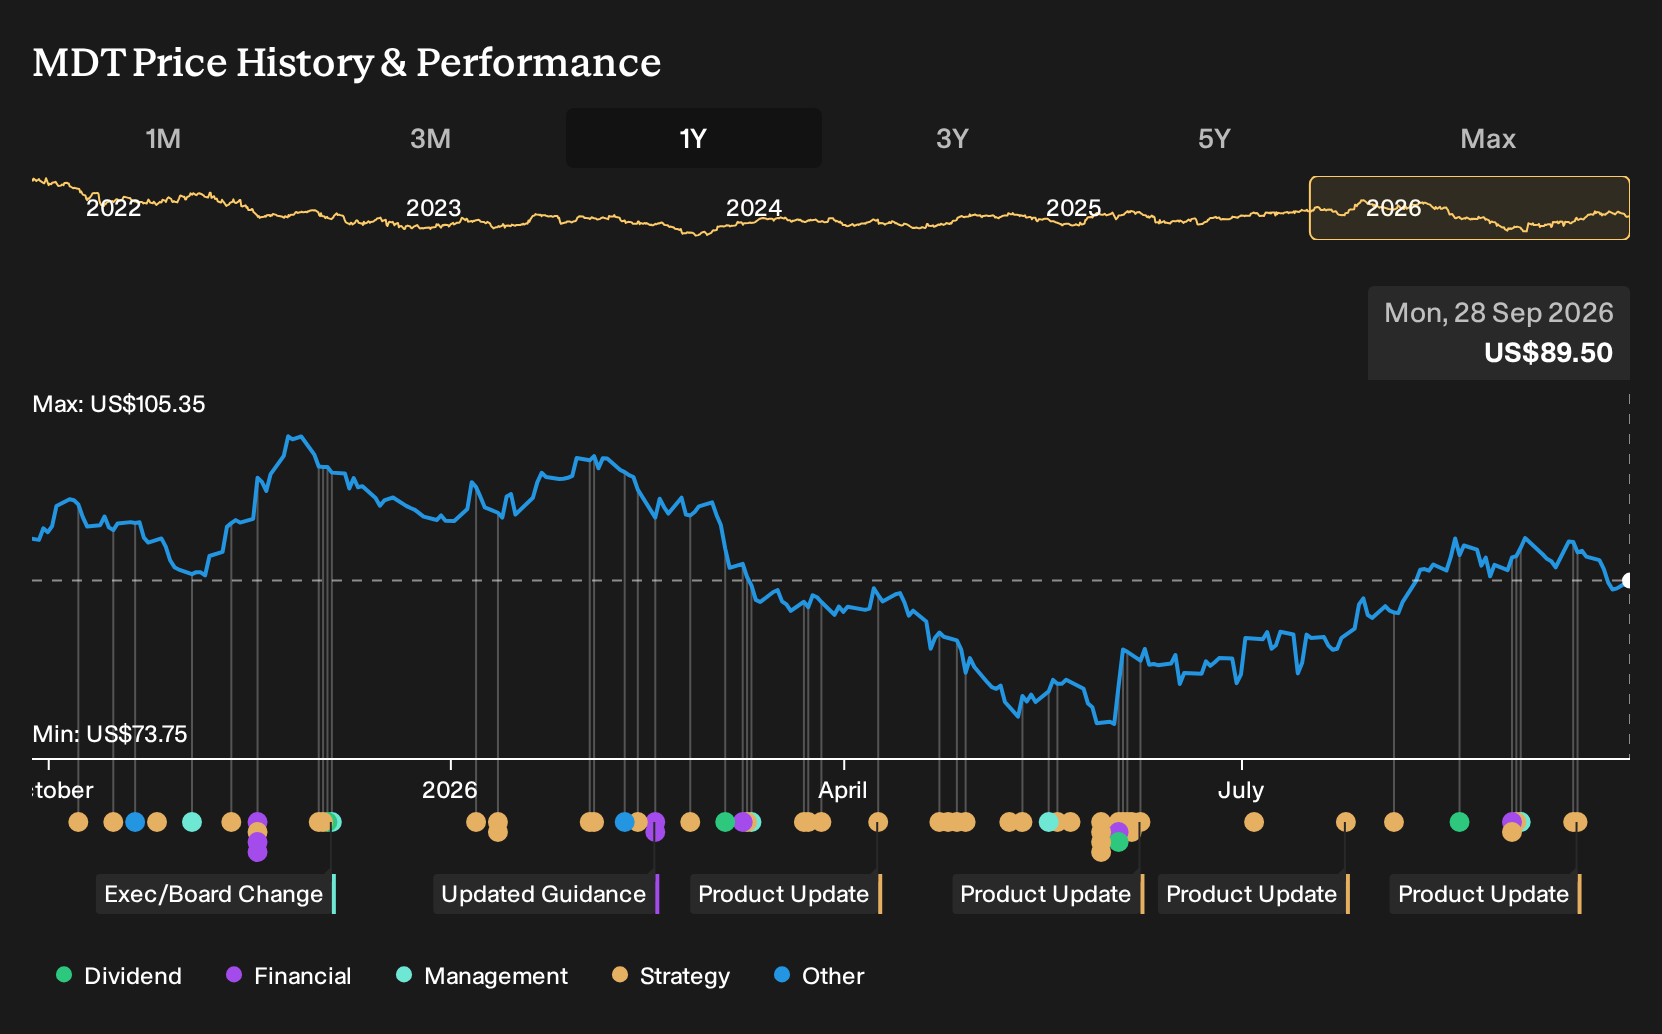
Exploring Other Perspectives
One alternate storyline for Medtronic focuses on hypertension devices rather than robotics. The most bearish analysts were modeling only 1.7% yearly revenue growth to about US$39.5b and earnings of roughly US$6.4b by 2029, before these LigaSure and Sonus announcements. That is a far cooler outlook. Use it as a prompt to compare several viewpoints yourself.
Explore 8 other Medtronic fair value estimates, including one that suggests it could be worth just $90.37.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Medtronic research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Medtronic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Medtronic's overall financial health at a glance.
Looking For More Investment Ideas Beyond Medtronic?
If you want to stress test your Medtronic view against other opportunities, cast the net wider with the Simply Wall St Screener and compare businesses with very different risk and return profiles.
- If you care most about stability and capital protection, use our screener to focus on 30 resilient stocks with low risk scores that aim to keep drawdowns in check while still offering equity upside.
- If balance sheet strength is non negotiable for you, start with a list of solid balance sheet and fundamentals (25 results) that can help you filter out fragile capital structures before you spend time on deeper research.
- If you want to get in early on underfollowed stories, scan through a curated 16 high quality undiscovered gems that might not be widely covered yet but already show solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com