
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Harley Davidson (HOG) Could Be 14% Undervalued As Realtree Tie Up Renews
Harley-Davidson (HOG) just refreshed its partnership with outdoor brand Realtree, rolling out a second limited-edition apparel line that targets riders who also identify as hunters and outdoor enthusiasts.
The refreshed Realtree collaboration lands at a time when Harley-Davidson’s share price has slipped 12.21% over the past 30 days and 5.88% over the last week, even though the year-to-date share price return sits at 19.53% and the 1-year total shareholder return is down 11.16%. This suggests that recent momentum has cooled while longer term investors have yet to see a recovery in overall returns.
Scan beyond Harley-Davidson and this Realtree tie-in by sizing up other consumer-focused stocks with resilient brands, using our hand-picked 16 high quality undiscovered gems as a starting list.
After a sharp pullback that leaves Harley-Davidson still up for the year but weaker over one and three years, you now have to ask whether the meaningful upside sits ahead of you or already lies in the rear-view mirror.
Most Popular Narrative: 12% Undervalued
Harley-Davidson’s most followed valuation storyline points to a fair value of $28.18 per share versus the recent $24.67 close, which frames the Realtree tie-in against a backdrop of modest implied upside and rising execution demands.
The new partnership in HDFS unlocks significant cash ($1.25b) and reduces leverage, enabling accelerated share buybacks and freeing up $300m for growth investments, which can directly bolster EPS and future revenue streams through both financial engineering and new business initiatives.
See why 13 investors see Harley-Davidson as 12% undervalued.
Result: Fair Value of $28.18 (UNDERVALUED)
Still, Harley-Davidson’s story can change quickly if weak global motorcycle demand persists or if tariff costs bite harder than analysts currently assume.
Find out about the key risks to this Harley-Davidson narrative.
Another View: Harley-Davidson Through A Cash Flow Lens
Analysts see Harley-Davidson as undervalued using earnings based ratios, yet the Simply Wall St DCF model paints a very different picture. On that framework, the current price of $24.67 sits well above an estimated future cash flow value of $4.35, which sharply widens the question around downside risk.
For anyone weighing these conflicting signals, it helps to understand exactly how the cash flow assumptions differ from the earnings story, then decide which feels more realistic for your own thesis. Look into how the SWS DCF model arrives at its fair value.
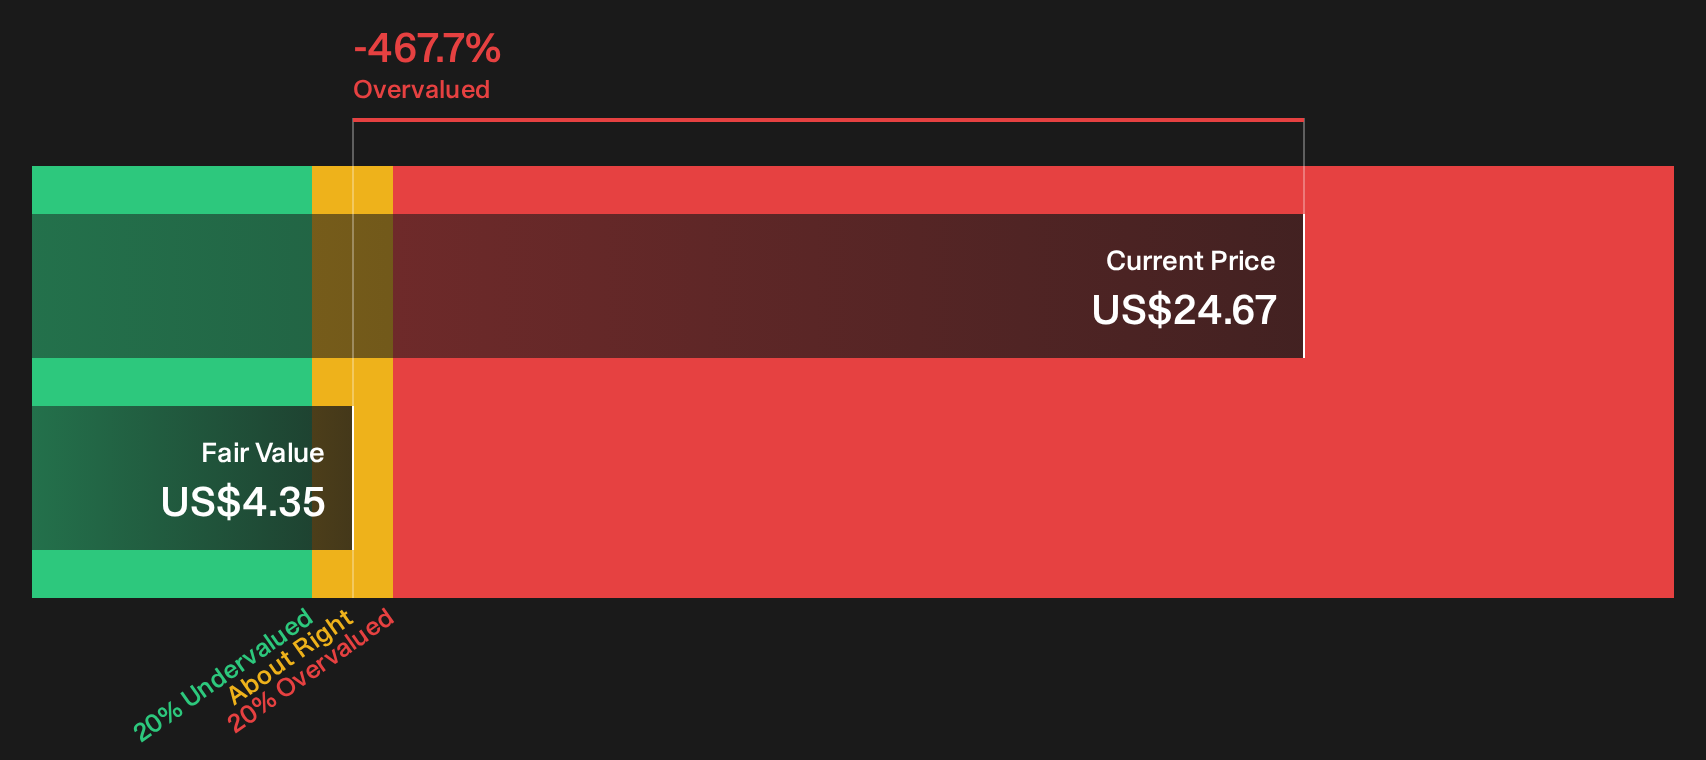
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Harley-Davidson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Harley-Davidson feels split right now, so consider acting promptly, weighing the mixed signals, and basing your view on the underlying data by checking 3 key rewards and 1 important warning sign.
Looking for more Harley-Davidson sized opportunities?
If Harley-Davidson has you rethinking where the best risk and reward might sit next, broaden your watchlist now with fresh ideas sourced directly from focused stock screeners.
- Target potential turnaround candidates early by scanning the 7 elite penny stocks with strong financials that already show stronger financial underpinnings than the typical micro-cap story.
- Zero in on quality at a discount by reviewing the 32 high quality undervalued stocks that pair healthier balance sheets with pricing that still looks conservative.
- Prioritise resilience over thrills by filtering for the 30 resilient stocks with low risk scores that score well on stability and keep downside as a constant consideration.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com