
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Should View Marvell Stock as Seaport Analysts Join the MRVL Bulls
Semiconductor stocks have been on a strong run, and the artificial intelligence (AI) data-center spending boom is a big reason why. Bank of America now sees the industry’s addressable market reaching $2.7 trillion by 2030, up from its earlier $2.3 trillion forecast. That would mean a 28% annual growth rate from 2025.
Marvell Technology (MRVL) has been one of the biggest winners of the semiconductor space, with MRVL stock up 203% over the past 52 weeks and up more than 196% in 2026. That is well ahead of the S&P 500 ($SPX), which has gained 16% over the past year and 12% so far in 2026.
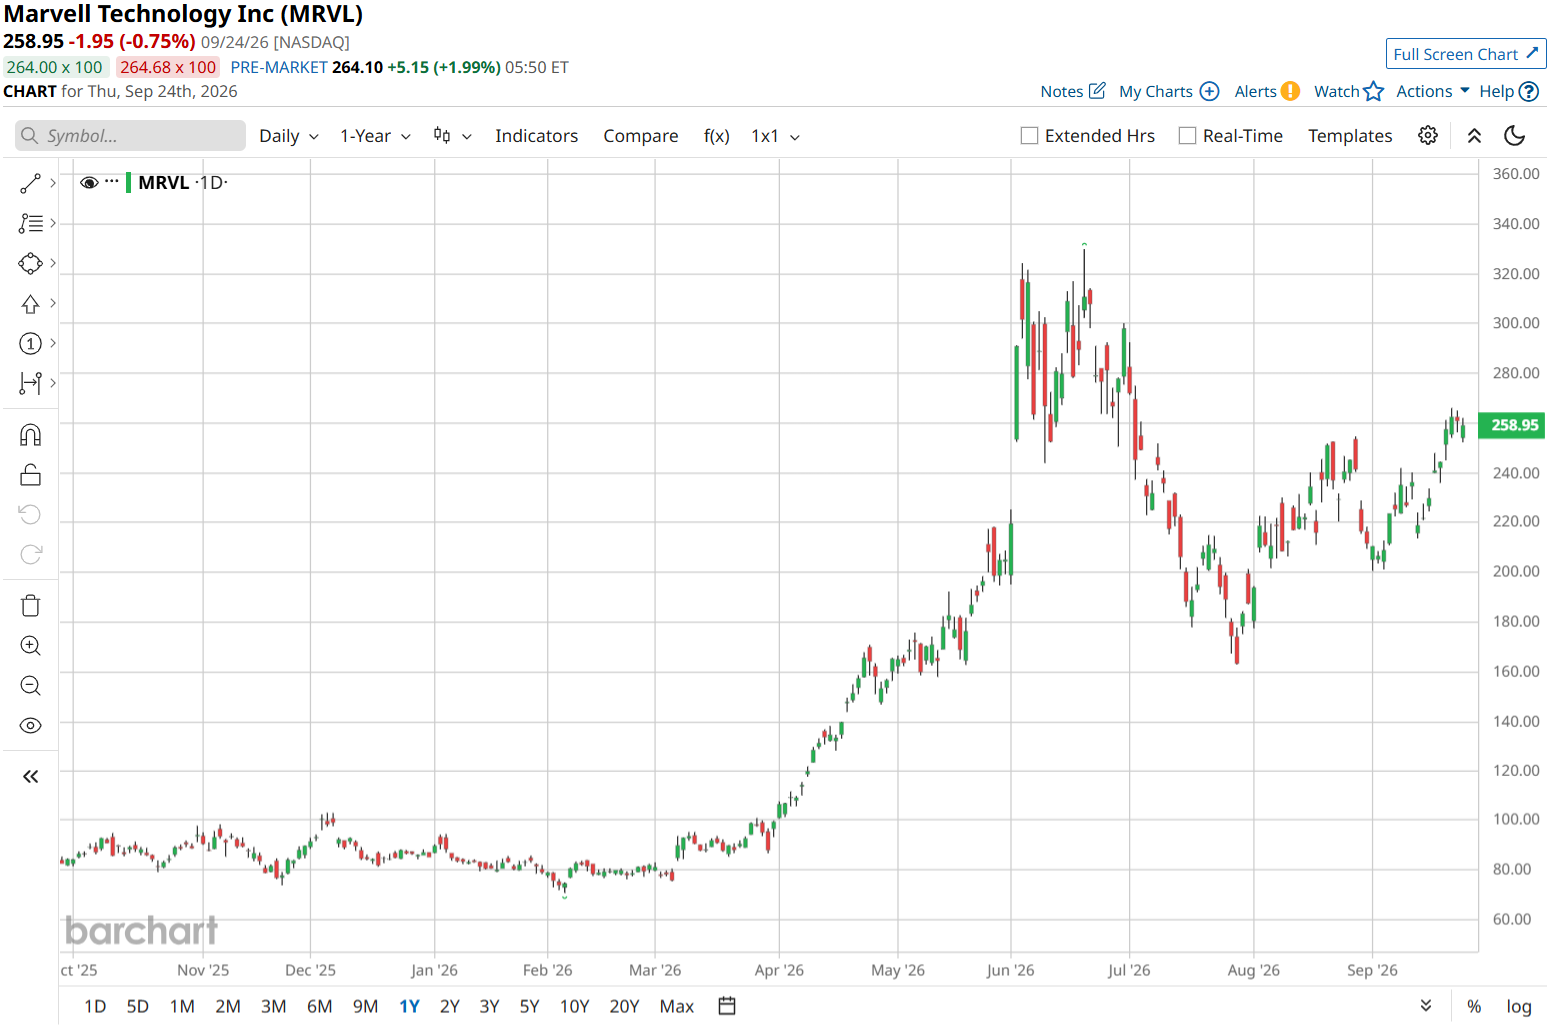
MRVL stock got another boost earlier this week after Marvell Technology said it would showcase 2-nanometer optical interconnect technology for AI data centers. Its lineup includes 400G-per-lane optical PAM4, 800G and 1.6T ZR products, and a 102.4T co-packaged optics platform. Shares of Marvell rose more than 6% in one session following the news.
Now, Seaport Research Partners has added its voice to the bull case. On Sept. 23, Seaport initiated coverage of Marvell with a “Buy” rating and a $270 price target, pointing to growth in the company’s interconnect and custom-silicon businesses. Still, after a gain of more than 200% this year, can MRVL stock keep climbing? Let's take a closer look.
Breaking Down Seaport’s ‘Buy’ Call
On Sept. 23, Seaport started coverage of Marvell with a “Buy” rating and a $270 price target. Analyst Jay Goldberg expects more growth from the company’s optical-connectivity and custom-chip businesses as cloud companies keep spending on new data-center capacity.
The $270 price target was not calling for a huge immediate move. MRVL stock traded near $262 when Seaport began coverage, so the target implied limited potential upside at that point. Still, Goldberg sees a solid long-term case in Marvell’s optical products, which are used in systems built around chips from Nvidia (NVDA), and in its custom-chip business for large cloud customers.
Seaport’s call covered more than just Marvell Technology. The firm also gave “Buy” ratings to Semtech (SMTC) and ON Semiconductor (ON). Meanwhile, SiTime (SITM) received a “Neutral” rating from the firm. Goldberg referred to the group as the “four horsemen of AI.”
There is one detail investors should keep in mind. Marvell expects non-GAAP gross margin of 58.25% to 59.25% this quarter, below the 59.4% it reported a year ago. That means earnings growth may depend more on keeping costs under control than on improving margins.
The Fundamentals Behind the Bull Case
Marvell backed up Seaport’s bullish view with a strong second-quarter fiscal 2027 report. Revenue hit a record $2.739 billion during the quarter, up 37% from a year earlier, while adjusted earnings rose 40% year-over-year (YOY) to $0.94 per share. GAAP net income came in at $308 million, or $0.33 per diluted share. The company's data-center business did most of the heavy lifting with revenue up 46% YOY to $2.17 billion, or roughly 79% of total sales. Communications and other revenue rose 10% YOY to $567.8 million. Marvell also generated $605.5 million in operating cash flow.
For the current quarter, management expects about $3.15 billion in revenue and adjusted EPS of $1.10. Management also now sees fiscal 2027 revenue near $12 billion and fiscal 2028 revenue near $18 billion.
Marvell is also working more closely with Nvidia. Under a partnership announced on March 31, Nvidia invested $2 billion in the company. Marvell will supply custom XPUs and networking products compatible with Nvidia’s NVLink Fusion platform, while the two firms will also work together on optical connections, silicon photonics, and AI-RAN products for 5G and 6G networks. That gives Marvell more ways to sell its custom chips and connectivity products as data-center customers build larger systems.
What Do Analysts Expect Next?
Marvell is scheduled to report earnings on Dec. 1. Analysts expect EPS of $0.79 for the October quarter, up 27% from $0.62 a year earlier. For fiscal 2027, the consensus estimate is $3.05 per share, up 41% YOY from $2.16. Those numbers show that analysts expect Marvell Technology’s recent growth to continue, not slow down.
Morgan Stanley recently raised its price target for MRVL stock to $268 from $246. The firm pointed to Marvell’s networking products and growing custom-chip work with Alphabet (GOOGL). Rosenblatt Securities took a more bullish view after the Q2 results, raising its target to $300 on expectations that big cloud customers will keep buying more custom chips.
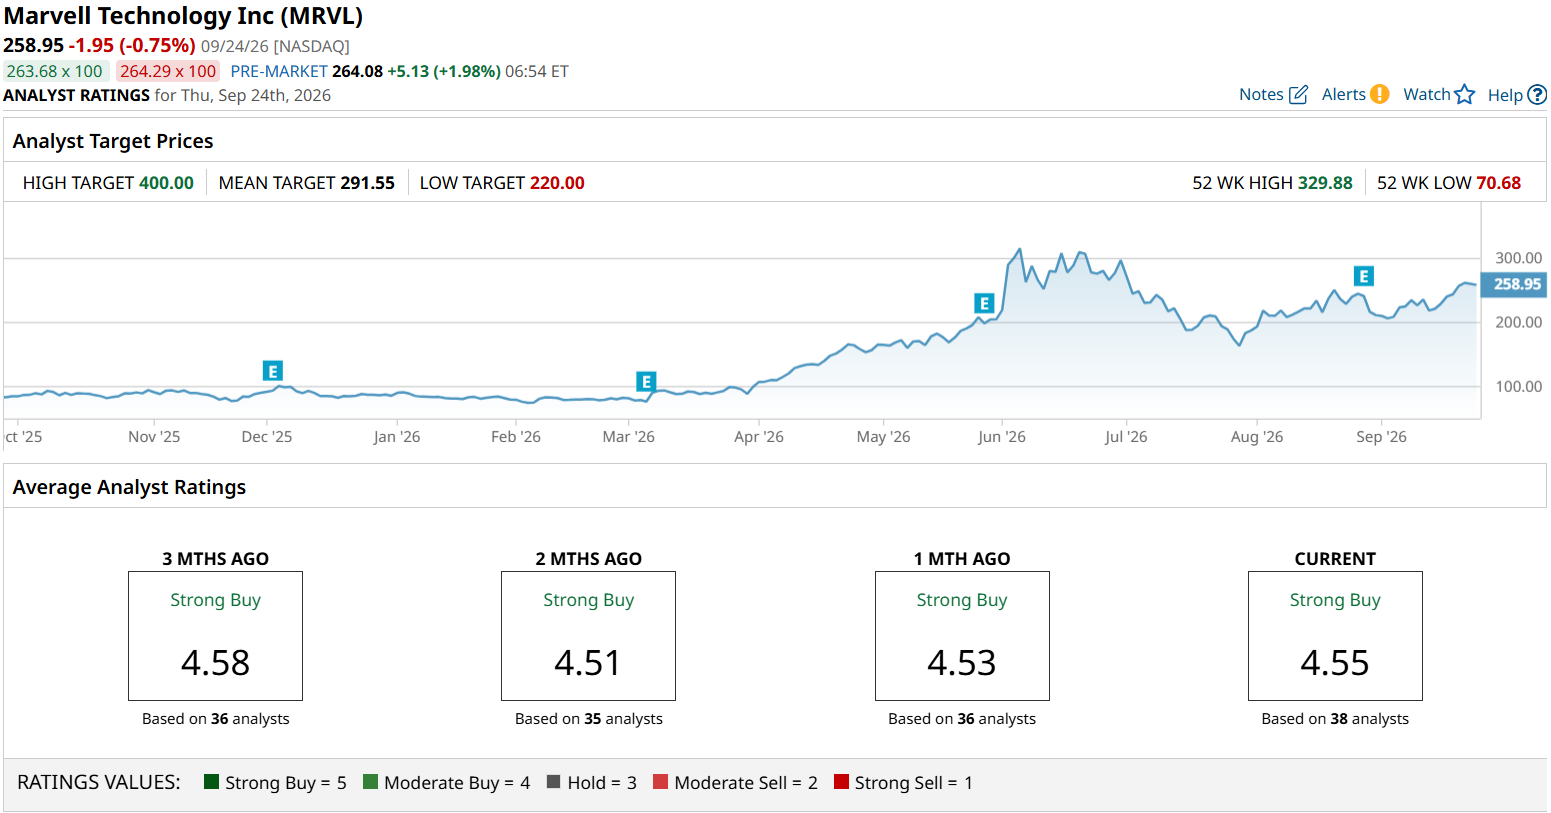
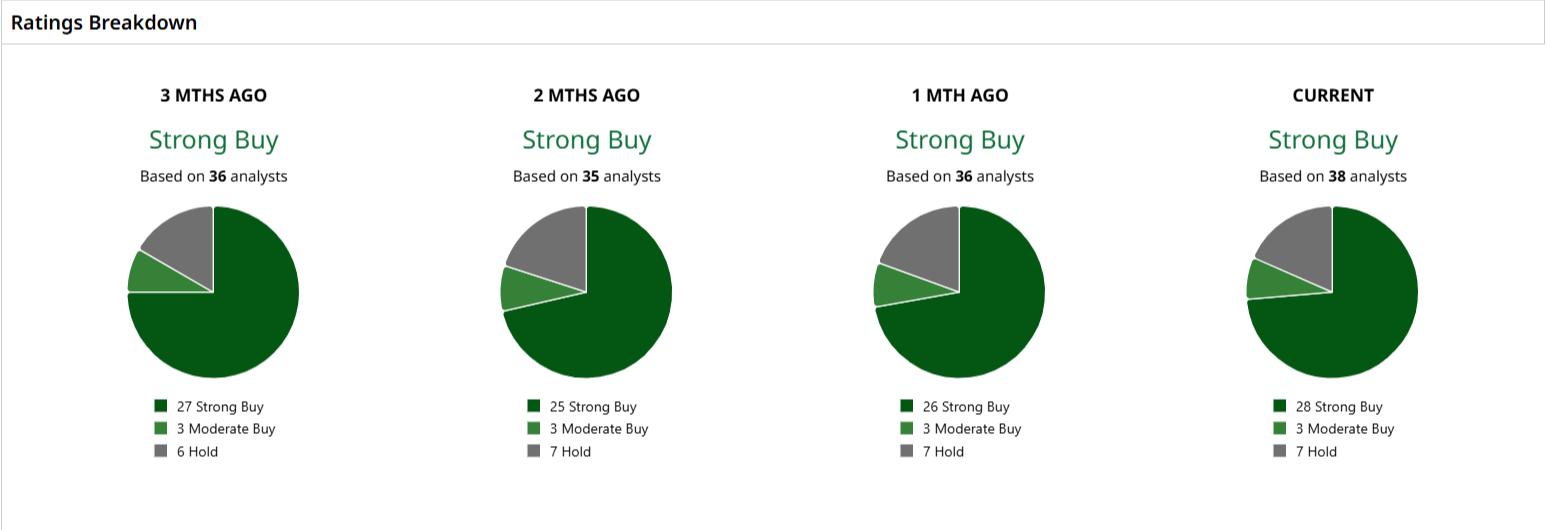
Overall, MRVL stock has a consensus “Strong Buy” rating on Wall Street based on 38 analysts with coverage. The average price target of $291.55 points to potential upside of 16% from current levels.
Conclusion
So, how should investors view Marvell Technology stock now? Seaport Research's “Buy” rating is not a lone call. It reflects a broader Wall Street conviction backed by record revenue, a 46% jump in data-center sales, and a deepened Nvidia partnership. The catch is that much of this optimism is already baked in after the 200% run this year, while the implied 16% upside is decent, not dramatic. For long-term investors, the AI buildout story still has room to run, so shares will likely grind higher toward the $291.55 mean target with bumps along the way. Buying on pullbacks looks smarter than chasing rallies at these levels.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.