
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Patrick Industries (PATK) Undervalued As It Heads To The Wells Fargo Consumer Conference?
Patrick Industries (PATK) is set to present at the Wells Fargo 9th Annual Consumer Conference in Dana Point on September 23, 2026, giving investors fresh context for the stock’s recent performance.
The Patrick Industries share price has slipped 17.34% over the past month and 23.15% over the last quarter, contributing to a year to date share price decline of 37.52%. However, long term total shareholder returns over three and five years remain positive at 45.85% and 32.52% respectively, suggesting earlier buyers have still come out ahead.
Scan how Patrick Industries compares to a hand picked group of resilient manufacturers and distributors by checking out the list of solid balance sheet and fundamentals (25 results) in the same corner of the market.
The slide in Patrick Industries over the past few months could signal deeper concerns about the business, or it could simply reflect a swing in sentiment. The current valuation will show which story fits.
Most Popular Narrative: 37% Undervalued
Patrick Industries is trading at $69.00 while the most followed narrative framework pegs fair value at $109.80. This creates a wide gap that sets up a very different conversation from the recent share price slide.
Accelerated growth in the aftermarket segment, including direct-to-consumer (DTC) sales via RecPro and expanded SKUs, opens new and less cyclical revenue streams that diversify away from OEM production cycles, supporting topline and margin stability.
See why 2 investors see Patrick Industries as 37% undervalued.
Result: Fair Value of $109.80 (UNDERVALUED)
Still, the fair value story for Patrick Industries could unravel quickly if RV demand stays weak for longer or if acquisition integration falls short of expectations.
Find out about the key risks to this Patrick Industries narrative.
Another View on Patrick Industries Valuation
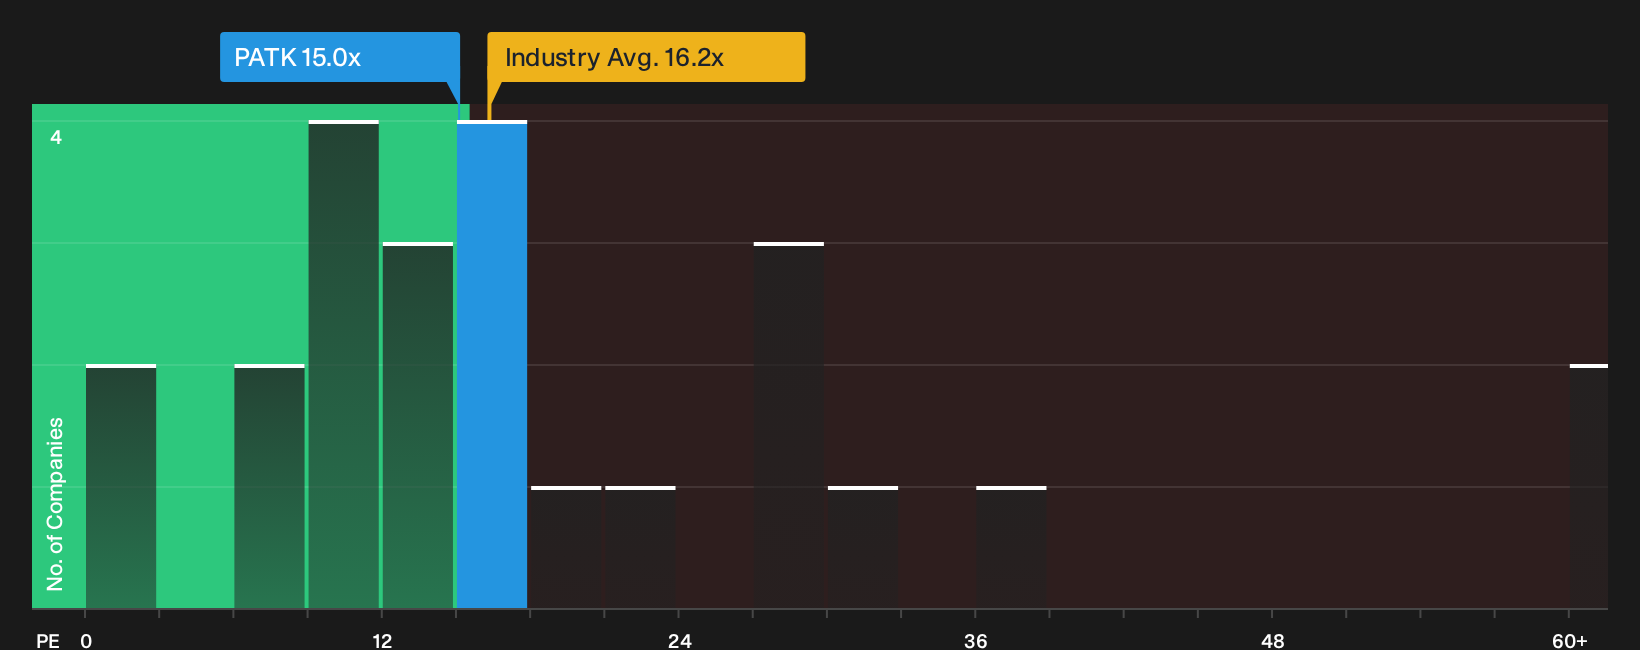
The first lens on Patrick Industries leans heavily on discounted cash flows and a narrative fair value of $109.80, yet the market is still trading the shares on simple earnings maths. At about 15x P/E, the stock sits above direct peers on 12.2x, but only slightly below its own fair ratio of 15.5x.
That mix points to a business priced richer than similar Auto Components stocks, while still close to where the fair ratio suggests the multiple could drift. For anyone weighing the 37% DCF style undervaluation against this tighter P/E picture, the real question is which yardstick feels more reliable when the cycle turns next.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Patrick Industries is clearly split. Use that tension as a prompt to move quickly, review the data, and weigh both sides through the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Patrick Industries?
Do not stop with Patrick Industries. Use the Simply Wall St screener to quickly spot fresh opportunities across different styles instead of waiting for the next headline.
- Target resilient cash generators that still look mispriced by running your eye over 32 high quality undervalued stocks.
- Prioritise capital preservation and steadier returns with a focus on 30 resilient stocks with low risk scores.
- Hunt for future leaders that few investors are talking about by scanning the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com