
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Ulta Beauty (ULTA) A Bargain As In Store Brand Expansions Draw More Attention?
Ulta Beauty (ULTA) is back in focus after several partner brands, including Wavytalk, Flower Knows, and COSRX, expanded from online listings into Ulta’s physical stores with exclusive products and in-person experiences.
These brand launches land at a moment when Ulta Beauty’s share price has climbed 21.76% over the past 90 days and 6.11% over the past month, even as its year-to-date share price return is down 11.44% and the 1-year total shareholder return is slightly negative at 0.83%. The longer 3 and 5-year total shareholder returns of 36.28% and 48.45% point to momentum that has built over a multi year period despite recent volatility.
Scan how Ulta Beauty compares with other retailers leaning into experiential beauty and wellness by reviewing the handpicked 32 high quality undervalued stocks.
Recent gains put Ulta Beauty in a tighter spotlight. Are investors finally catching up to the underlying business shift toward experiential retail, or has sentiment run ahead of what the current earnings profile supports?
Most Popular Narrative: 12.5% Undervalued
On the most followed view, Ulta Beauty’s fair value of $627.25 sits above the last close at $549.13, which puts the recent share price rebound in a different light and centers the discussion on whether its experiential and wellness push can carry that gap.
Ulta Beauty's expansion into the wellness category, with dedicated in-store footprints and over 150 brands, is set to capture a larger share of the rapidly growing self-care and wellness market, driving new customer acquisition and top-line revenue growth over the long term.
The widening of Ulta's assortment, particularly through exclusive brand launches, key partnerships with in-demand emerging brands, and the rollout of a curated online marketplace, positions the company to attract Gen Z and Millennials, increase basket sizes, and capture higher-margin sales, benefiting both revenue and gross margins.
See why 74 investors see Ulta Beauty as 12% undervalued.
Result: Fair Value of $627.25 (UNDERVALUED)
Still, Ulta Beauty faces pressure if rising store and labor costs squeeze margins, or if competition in beauty and wellness slows customer spending and loyalty gains.
Find out about the key risks to this Ulta Beauty narrative.
Another View: Ulta Beauty Through The P/E Lens
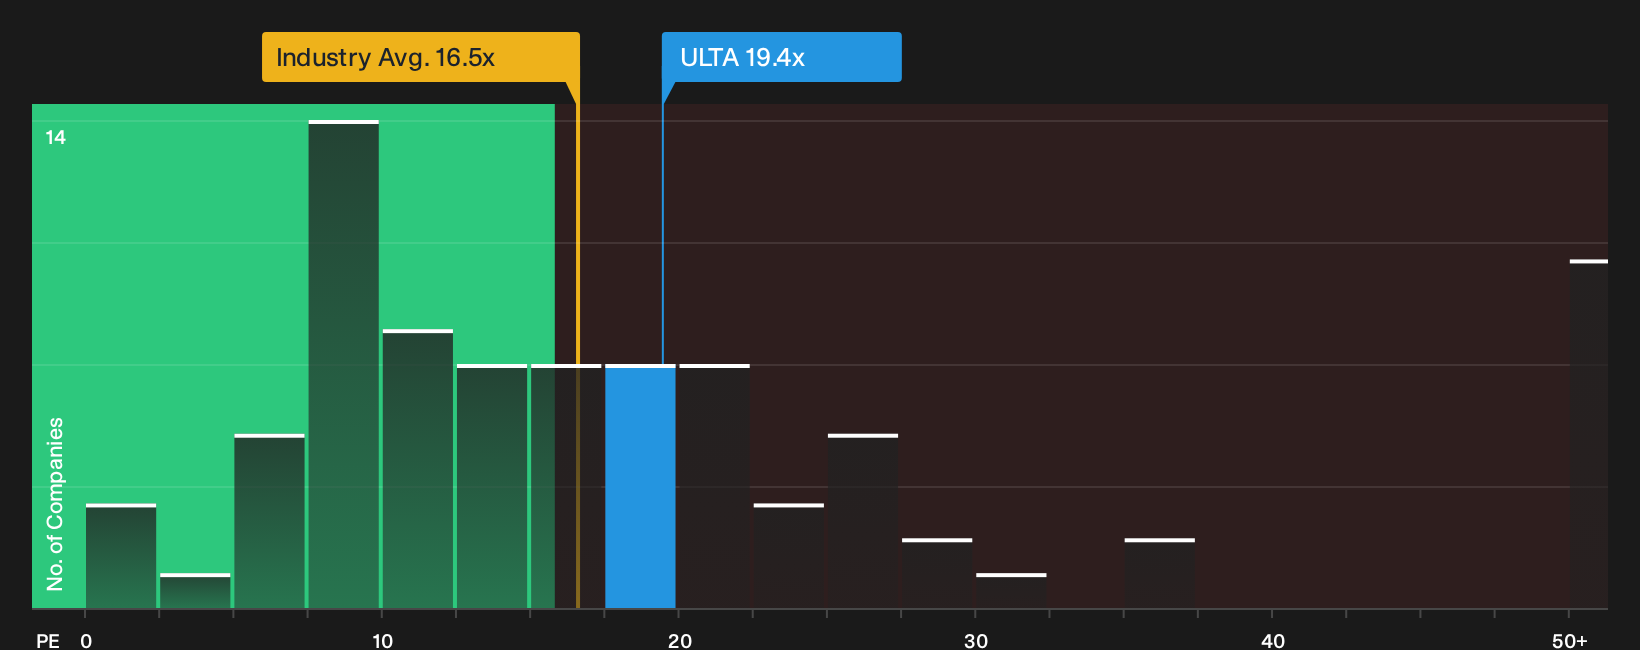
Ulta Beauty screens very differently when you step away from the analyst fair value and look at the P/E. The stock trades around 19.4x earnings, above the US Specialty Retail average of 16.5x and its own fair ratio of 16.6x. This points to less margin for error if growth cools or margins slip.
For a closer look at how this earnings multiple compares with sector peers and that fair ratio the market could move toward, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
There have been mixed messages on Ulta Beauty so far, and you may want your own angle before the crowd moves on. Explore the full picture in 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Ulta Beauty?
If you stop with Ulta Beauty, you miss plenty of other angles. Put the same level of scrutiny to work across sectors and potential opportunities.
- Target potential high upside by scanning through 7 elite penny stocks with strong financials that pair tiny market caps with stronger than usual fundamentals and real operating traction.
- Focus on quality at a reasonable price by running through the handpicked 16 high quality undiscovered gems that screen for robust balance sheets and underfollowed stories.
- Dial down portfolio stress by reviewing 30 resilient stocks with low risk scores that highlight businesses scoring well on financial strength and earnings consistency.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com