
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Mercury Systems (MRCY) Overvalued Even After Reaffirmed Guidance?
Mercury Systems has delivered a very strong 120.7% share price gain over the past three years, yet recent short term declines now put a spotlight on whether that run is still supported by its sales base. With the stock last closing at US$80.12, the key issue for investors is how much revenue power they are effectively paying for at today’s level.
- The 120.7% return over three years means anyone looking at Mercury Systems today is assessing a business whose valuation has already been reset by a very large move in the share price.
- The decision to extend Chairman and CEO Bill Ballhaus’s contract to 2030, alongside reaffirmed financial targets, can signal that management expects the company’s revenue and margin profile to support its current business plans.
- There is a second opinion on Mercury Systems worth weighing. See what analysts think Mercury Systems's shares could be worth.
The issue now is whether Mercury Systems’ current share price is appropriately anchored to what its sales can justify.
If you want to pressure test whether Mercury Systems’ sales-based valuation still feels reasonable, you can compare it with a wider set of 32 high quality undervalued stocks.
Has Mercury Systems Run Too Far on Sales?
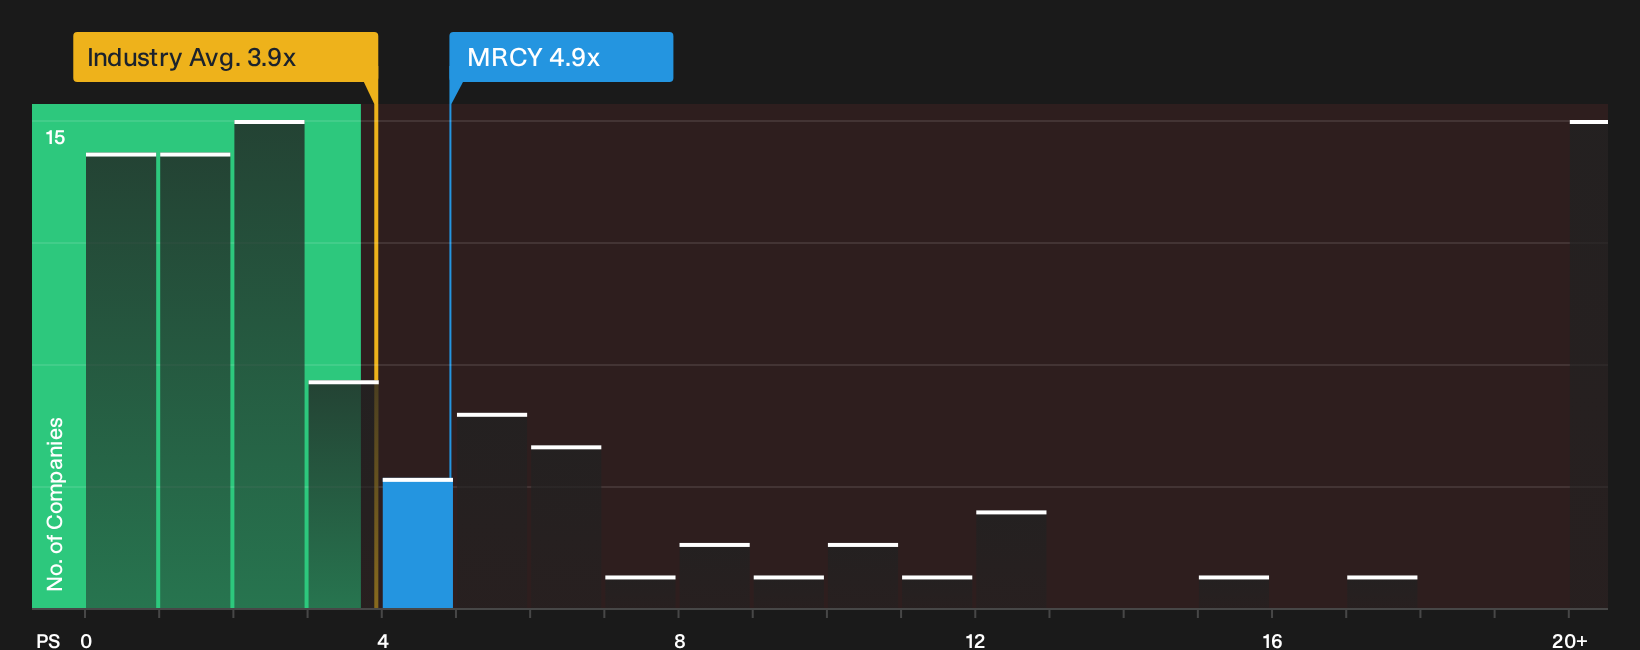
The P/S ratio suits Mercury Systems because investors are currently paying more attention to its revenue base than its earnings. At roughly 4.9x sales, the stock trades above the Aerospace & Defense industry average of about 3.9x, yet below a peer group closer to 8.8x. That leaves Mercury Systems priced at a premium to the broader sector but at a discount to more richly valued direct comparisons.
The fair-value model for this stock implies a lower P/S multiple than where Mercury Systems trades today, so the current 4.9x screens as overvalued on this framework. Because management recently extended the CEO’s contract and reaffirmed guidance, the market seems willing to pay a higher sales multiple for that continuity and outlook, even though the valuation already reflects a strong revenue profile. Explore the numbers behind Mercury Systems's P/S valuation.
The Mercury Systems Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Mercury Systems pick up where this valuation puzzle leaves off. They spell out which assumptions on revenue growth, profitability, and earnings power would need to hold for Mercury Systems' stock to be worth materially more or less than it trades for today. Each scenario ties a fair value to a clear story about catalysts and risks so you can track over time which version of events appears to be unfolding on the Community page.
Community views on Mercury Systems are split between those who see more upside in the backlog story and those who think expectations already look full.
Bull case: 31% undervalued
"Growth in backlog and bookings across U.S. and European defense primes, particularly in radar, electronic warfare, and sensor modernization, demonstrates strong alignment with defense modernization..."
Discover why this Narrative puts Mercury Systems at 31% undervalued.
Bear case: roughly fairly valued
"Despite robust recent results, medium-term revenue growth is likely to stall as Mercury Systems faces persistent government budget deficits and elevated interest rates, which could force downward pressure on defense spending..."
Explore why this Narrative puts Mercury Systems at roughly fairly valued.
Before you move on Mercury Systems, there is one more signal worth checking
Price tells you what the market thinks today, but the next layer is how professionals see Mercury Systems a few years from now and how that lines up with the current multiple. Explore where analysts expect Mercury Systems to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com