
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Mercantile Bank (MBWM) Cools After A Strong Run, Is The Valuation Gap Too Wide?
Mercantile Bank (MBWM) has drawn fresh attention after its shares closed at US$59.38 on 27 September 2026. This invites a closer look at recent returns and underlying business performance.
Recent trading has been a mild step back rather than a reversal, with the 1-day share price return down 1.08% and the 30-day share price return down 1.38%. Mercantile Bank still shows a 24.72% year-to-date share price gain and a 36.15% 1-year total shareholder return, supported by a 112.59% 3-year and 114.92% 5-year total shareholder return that together highlight the stock’s longer-term momentum.
Scan how Mercantile Bank’s recent run compares with other financial stocks by reviewing a curated set of list of solid balance sheet and fundamentals (25 results) that investors are watching for their resilience.
Mercantile Bank now trades below both analyst targets and an estimated fair value, yet the stock has just cooled after a strong run. Is that discount compensation for risk or a market overreaction?
Most Popular Narrative: 10% Overvalued
Against Mercantile Bank’s last close at $59.38, the most followed narrative anchors fair value at about $59.33, effectively in line with the current price and framed using a 7.45% discount rate.
The widespread transition to digital banking services risks outpacing Mercantile's current technology investments, and any lag in rolling out advanced, seamless digital experiences may erode market share over time. This could constrain future revenue growth and pressure net margins, especially given intensifying competition from fintech firms.
See why 1 investors see Mercantile Bank as 0% overvalued.
Result: Fair Value of $59.33 (ABOUT RIGHT)
Still, Mercantile Bank could break from this cautious narrative if its Jack Henry digital upgrade meaningfully trims operating costs or if the Eastern Michigan Bank partnership delivers stronger earnings support.
Find out about the key risks to this Mercantile Bank narrative.
Another View On Mercantile Bank’s Valuation
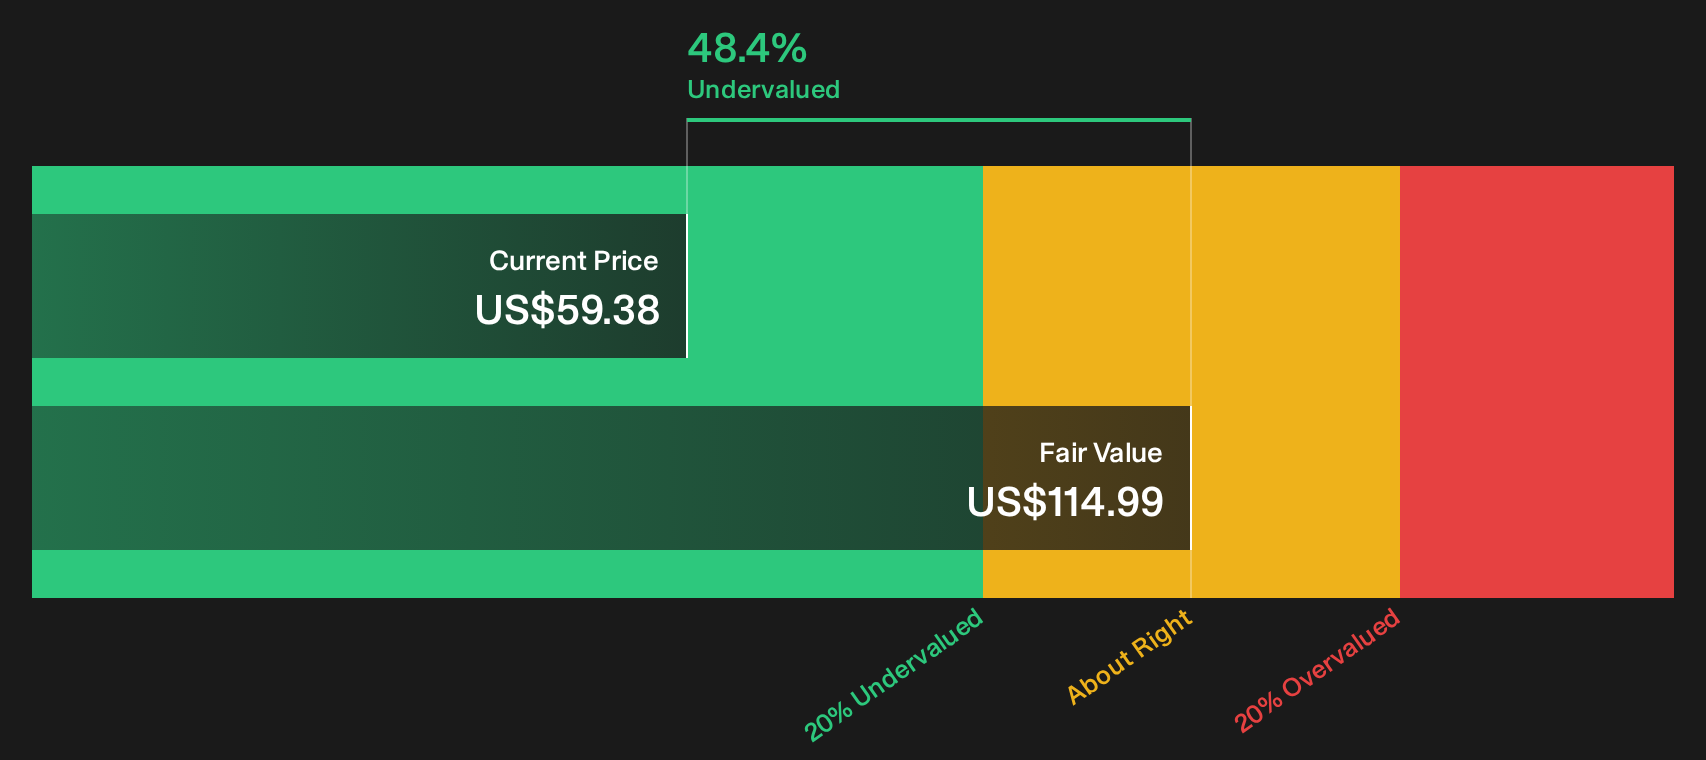
The analyst narrative frames Mercantile Bank as roughly fairly priced around $59.33, yet the SWS DCF model presents a very different picture. On that cash flow view, MBWM at $59.38 trades about 48% below an estimated value of $114.99, which highlights a wide gap investors may want to consider.
That kind of disconnect raises an obvious question: Is the market correctly discounting future risks, or is the DCF being too generous about how durable Mercantile Bank’s cash generation will be over time?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views on Mercantile Bank’s value are clear, so move quickly, test the assumptions against your own checklist, then weigh up the 3 key rewards.
Looking for more Mercantile Bank sized ideas?
If Mercantile Bank has sharpened your focus, do not stop here. Broaden your watchlist so you are not relying on a single opportunity.
- Target stronger value potential by scanning companies that screen as 32 high quality undervalued stocks and see which ones deserve a closer look.
- Prioritise resilience by reviewing a 30 resilient stocks with low risk scores that can help you build a portfolio with fewer unpleasant surprises.
- Hunt for future standouts by checking a 16 high quality undiscovered gems that most investors are not paying attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com