
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bank OZK (OZK) Stock May Be Undervalued Despite Profitability Questions
Bank OZK has delivered a solid multi year gain, yet the stock has been under pressure more recently, which raises a simple question for investors: Is today’s share price well supported by the earnings that the bank is generating right now and is expected to produce over time?
- Over the past 3 years the stock has returned about 45.9%, putting real weight on whether current earnings can shoulder the price that has built up.
- The business leans heavily on its ability to earn a return on equity above its cost of capital, which can shape how much value each extra dollar of retained profit adds for shareholders.
- The analysts covering Bank OZK have run their own numbers. See what analysts think Bank OZK's shares could be worth.
The issue now is whether Bank OZK's current earnings power is strong enough to justify where the shares trade today.
If you want a wider yardstick for Bank OZK's earnings story, it can help to compare it with other financials using the solid balance sheet and fundamentals stocks screener (25 results).
Does Bank OZK Look Undervalued on Earnings?
P/E works well for a lender like Bank OZK because earnings are a direct read on how effectively it turns its loan book and capital base into profit for shareholders.
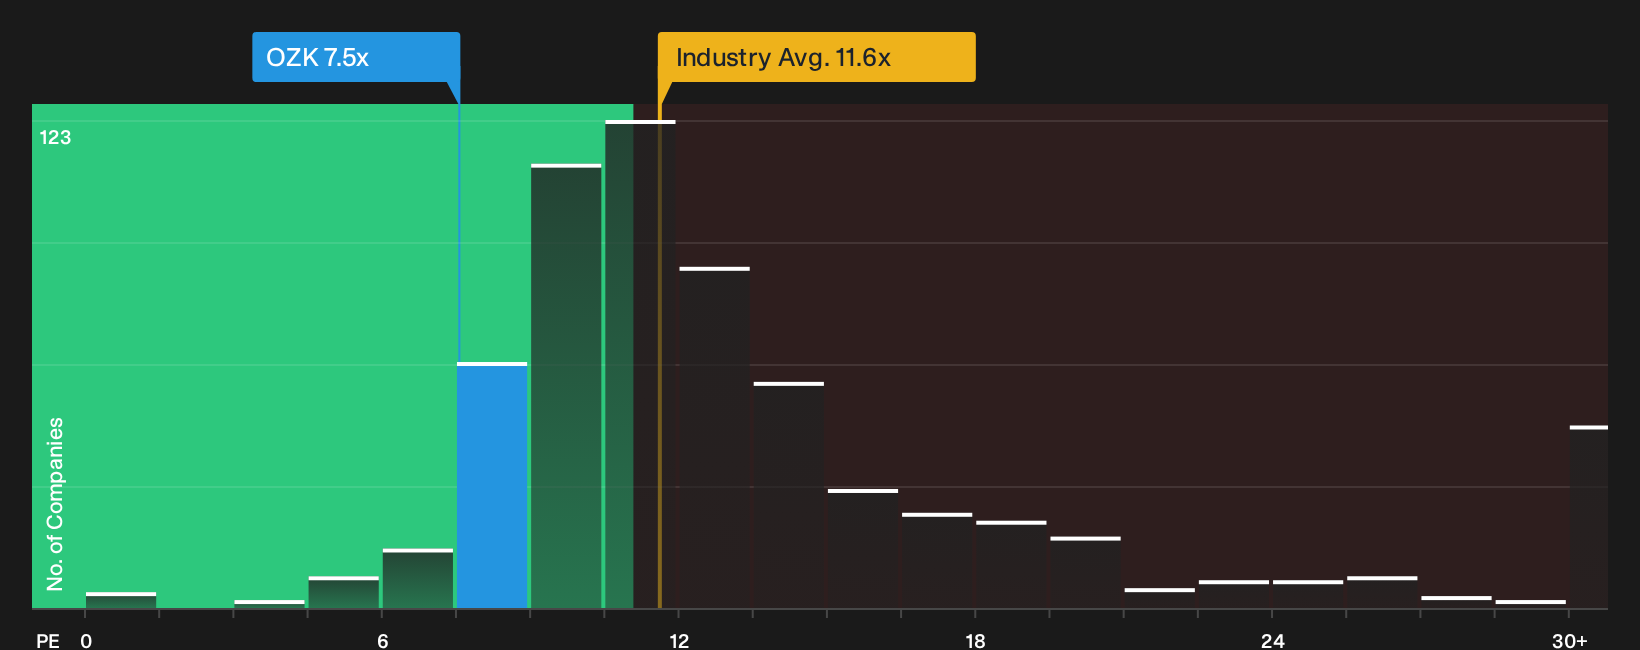
On this metric, Bank OZK trades on about 7.5x earnings. That is well below the wider banks industry average of roughly 11.6x and also under a broader peer group closer to 21.1x. A separate valuation framework that blends the company’s profitability, risk profile and size suggests Bank OZK could trade on a higher multiple than where it is now, which points to the current P/E sitting on the cheaper side of that range.
For you as an investor, that gap means the market is pricing Bank OZK’s earnings more cautiously than both sector averages and the tailored fair multiple imply. The key question is whether you think its profitability and balance sheet justify closing some of that discount over time. Explore the numbers behind Bank OZK's P/E valuation.
The Bank OZK Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Bank OZK valuation puzzle leaves off. They spell out which paths for future growth, profitability and earnings would need to play out for the stock to look materially more expensive or cheaper than today’s share price, and they sit on the platform’s Community page. Rather than a single P/E or model output, each narrative lays out the key assumptions behind its estimate of worth so you can compare those inputs with actual results as they arrive.
Community views on Bank OZK split between a loan mix and buyback story on one side and credit visibility worries on the other.
Bull case: 28% undervalued
"The ongoing plan to bring the RESG and Corporate & Institutional Banking loan books to roughly equal size around 2027 opens the door to a different balance sheet mix..."
Discover why this Narrative puts Bank OZK at 28% undervalued.
Bear case: 12% overvalued
"Bank OZK's heavy concentration in commercial real estate lending exposes it to heightened asset quality risks, as sectoral challenges such as increased refinancing and property value pressures could lead to elevated credit losses..."
Explore why this Narrative puts Bank OZK at 12% overvalued.
Bank OZK’s share price is only one piece of the puzzle
The current valuation tells you what the market pays for Bank OZK today, but analyst projections a few years out give you a different lens on where expectations sit and how confident they look. Explore where analysts expect Bank OZK to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com