
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What to Expect From Interactive Brokers’ Next Quarterly Earnings Report
Interactive Brokers Group, Inc. (IBKR), headquartered in Greenwich, Connecticut, is a global electronic brokerage providing trading and investment services. With a market capitalization of approximately $148.2 billion, the company offers access to stocks, ETFs, options, futures, currencies, bonds and mutual funds across more than 170 markets, alongside advanced trading platforms, research tools and portfolio management services.
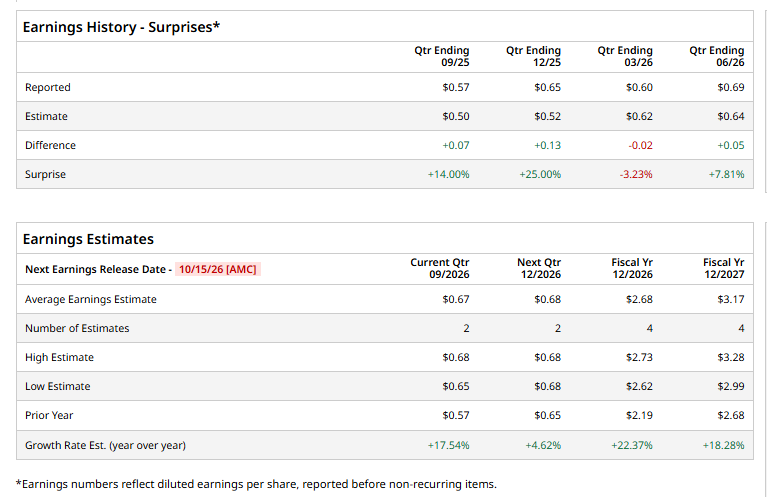
Interactive Brokers is set to report its Q3 earnings on Thursday, October 15, 2026, after the market closes. Ahead of the release, analysts expect the company to report diluted EPS of 67 cents, up 17.5% from 57 cents in the year-ago quarter. Moreover, Interactive Brokers has exceeded Wall Street’s EPS estimates in three of the past four quarters, while missing expectations in the remaining quarter.
For fiscal 2026, analysts expect the company to report EPS of $2.68, up 22.4% from $2.19 in fiscal 2025. Moreover, EPS is projected to increase another 18.3% year over year to $3.17 in fiscal 2027.
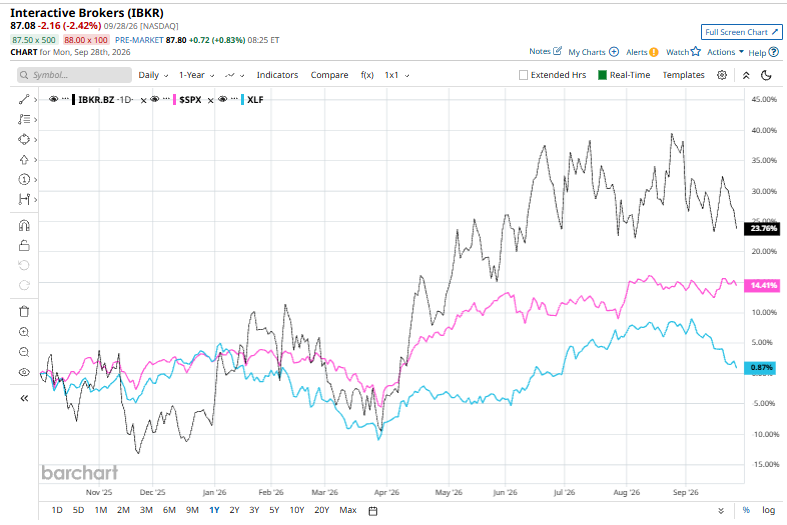
IBKR stock has gained 31.7% over the past 52 weeks, substantially outperforming the S&P 500 Index ($SPX), which returned 15.7%, as well as the State Street Financial Select Sector SPDR ETF (XLF), which posted only a marginal gain over the same period.
Interactive Brokers’ strong performance has been supported by rising net interest income and expanding margin lending activity. In its second-quarter results announced on July 21, net interest income increased 22.9% to $1.06 billion, while margin loan interest grew 39% and margin loan balances jumped 67% year over year to $108.5 billion. The Federal Reserve’s 25-basis-point rate hike could provide an additional tailwind, with management estimating an $81 million annual increase in NII.
More recently, on September 15, Interactive Brokers strengthened its competitive position in Japan by introducing three programs designed to reduce trading costs and help clients generate income from cash and fully paid shares. The new margin financing structure charges interest only on the amount borrowed, while Gaika+ and the Stock Yield Enhancement Program allow eligible clients to earn income on cash and shares. These offerings could support client growth and engagement while reinforcing IBKR’s cost-efficient and transparent platform.
Analysts remain somewhat bullish on IBKR, with the stock carrying a consensus “Moderate Buy” rating. Among the 12 analysts covering the stock, eight recommend a “Strong Buy,” while four suggest a “Hold.” Meanwhile, the average price target of $108.82 implies potential upside of 25% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.