
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Opengear Europe Deal Altering The Investment Case For Ingram Micro (INGM)?
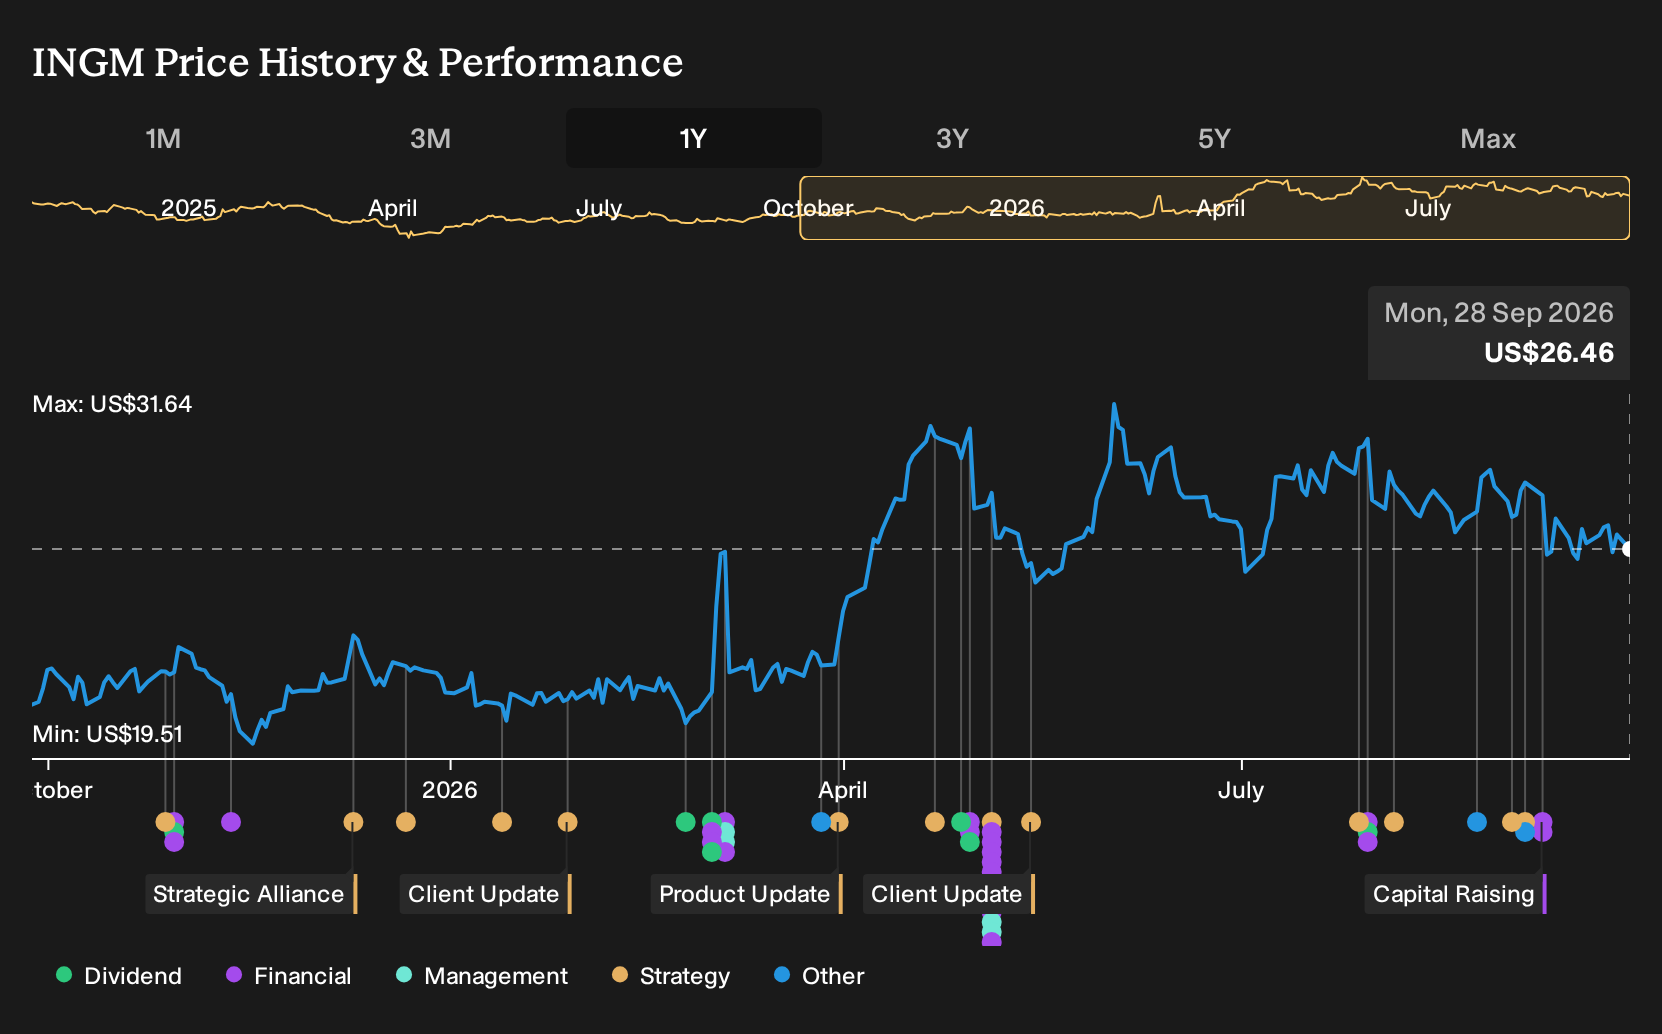
- Opengear announced it has entered a pan European distribution agreement with Ingram Micro, giving resellers in multiple EMEA countries access to Opengear’s network resilience portfolio, training, and pre and post sales support.
- The deal broadens Ingram Micro’s enterprise networking offering across existing and new European markets, potentially supporting more resilient demand for advanced infrastructure solutions and services.
- Attention now turns to how Ingram Micro’s broader EMEA reach for Opengear’s network resilience platform could influence the existing investment narrative.
Scan beyond Ingram Micro Holding and see how other distributors and infrastructure providers stack up on resilience and fundamentals with the hand-picked list of solid balance sheet and fundamentals (25 results).
Ingram Micro Holding Investment Narrative Recap
To own Ingram Micro Holding, an investor needs to believe that its scale in hardware distribution, growing AI infrastructure exposure and digital tools like Xvantage can gradually improve the quality of earnings despite a historically thin margin profile. The Opengear deal slightly supports that thesis in the near term by adding a higher value resilience offering, although it does not fundamentally change the earnings mix on its own.
The key short term swing factor remains execution on AI centric GPU, server and storage projects while keeping working capital in check. The biggest risk is that low margin infrastructure volumes and elevated inventory needs could strain free cash flow, especially if PC refresh demand cools or cloud growth stays muted.
The Opengear pan European agreement is most closely tied to the existing catalyst around advanced solutions and services. It broadens Ingram Micro Holding’s enterprise networking and resilience portfolio in EMEA, which can feed more volume into Xvantage and related AI enabled tools and create more touchpoints for SMB and enterprise partners that value uptime sensitive infrastructure.
This expansion also sits alongside the main operational risks. Larger hardware and AI deals transacted at deliberately low margin might still dilute gross margin mix, and the added territories can require more working capital. The real test is whether incremental Opengear activity supports higher quality service revenue and better operating leverage rather than just more low return volume.
Ingram Micro Holding's scenario assumes revenues of US$61.4b and earnings of US$678.6m by 2029, based on analysts’ forecast for 3.1% yearly revenue growth and an earnings increase of about US$248m from US$430.6m today.
Uncover why Ingram Micro Holding's fair value indicates a 25% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You might see this Opengear agreement and focus on resilience upside, but the most bearish analysts fixate on margin pressure instead. Before this news, they were only pencilling in about 2.3% annual revenue growth to roughly US$60.0b and earnings of US$649.5m by 2029. That more cautious view could shift as forecasts get refreshed.
Explore another Ingram Micro Holding fair value estimate, including one that suggests as much as 35% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Ingram Micro Holding research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ingram Micro Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ingram Micro Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ingram Micro Holding?
If the Opengear story has sharpened your interest in resilience, cash flows and balance sheet strength, it can help to compare Ingram Micro Holding with other potential opportunities using the Simply Wall St Screener. Different filters let you line up businesses by financial quality, pricing, income potential and risk profile, so you can build a watchlist that fits your own approach rather than just following consensus forecasts.
- For investors who care most about resilient balance sheets and solid fundamentals, start with a curated list of solid balance sheet and fundamentals (25 results) that focus on financial strength first.
- If value is your priority and you prefer companies that screen cheaply on quality metrics, sort through a hand picked set of 32 high quality undervalued stocks that may warrant closer fundamental work.
- Income focused investors can zero in on reliable cash payouts by scanning a targeted pool of 6 dividend fortresses and seeing which yields look sustainable based on the underlying financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com