
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DataBuddy Launch Might Change The Case For Investing In Tencent Stock (SEHK:700)
- Tencent Cloud recently launched DataBuddy, an agent native Data + AI workbench now rolling out globally, while Tencent partnered with W4 Games on Godot adoption in Asia and deployed its esports competition system across 11 medal events at the 20th Asian Games.
- These moves point to Tencent Holdings deepening its role as a core infrastructure provider across AI driven cloud services, open source game development, and standardized esports operations.
- Next, the focus will be on how Tencent's new DataBuddy AI platform could reshape the existing investment narrative around cloud and AI.
Scan how Tencent Holdings is pushing deeper into AI infrastructure, then size up other potential beneficiaries of this shift with a hand picked set of 87 AI infrastructure stocks in one place.
Tencent Holdings Investment Narrative Recap
To hold Tencent Holdings, you need to believe its pivot toward AI infrastructure, cloud and data platforms can keep earnings growing even as Chinese demand and regulation stay uneven. The near term swing factor is whether heavy AI spending, including compute prepayments, turns into higher quality revenue fast enough to support margins that analysts already see easing slightly.
The main risk right now is execution. Tencent is threading a needle between higher capex, tighter chip supply rules, and ongoing scrutiny on gaming and fintech. The new launches in AI agents and esports systems do not remove those pressures, but they show where management is trying to shift the earnings mix.
DataBuddy is the clearest operational link between Tencent Holdings and the AI narrative. It ties AI agents directly into data engineering, governance, analytics, and data science, and plugs into existing OLAP engines without forcing clients to move data. That setup leans into current enterprise digitalization trends in Asia and beyond rather than relying on entirely new demand.
For catalysts, the interest is not the marketing label but the plumbing. Unity Semantics, the Agent Runtime and OneOps speak directly to the risk that AI costs run ahead of monetization. If enterprises standardize more of their work on platforms like DataBuddy, Tencent’s cloud and enterprise arm gains a clearer path to scale, while poor adoption would leave the higher AI spend more exposed.
What The Analyst Scenario Implies For Tencent Holdings
Tencent Holdings' narrative projects CN¥1,040.3b revenue and CN¥295.2b earnings by 2029. This assumes 9.7% yearly revenue growth and an earnings increase of about CN¥59.7b from CN¥235.5b today.
Uncover why Tencent Holdings' fair value indicates a 54% potential upside to its current price that could close faster than many investors expect.
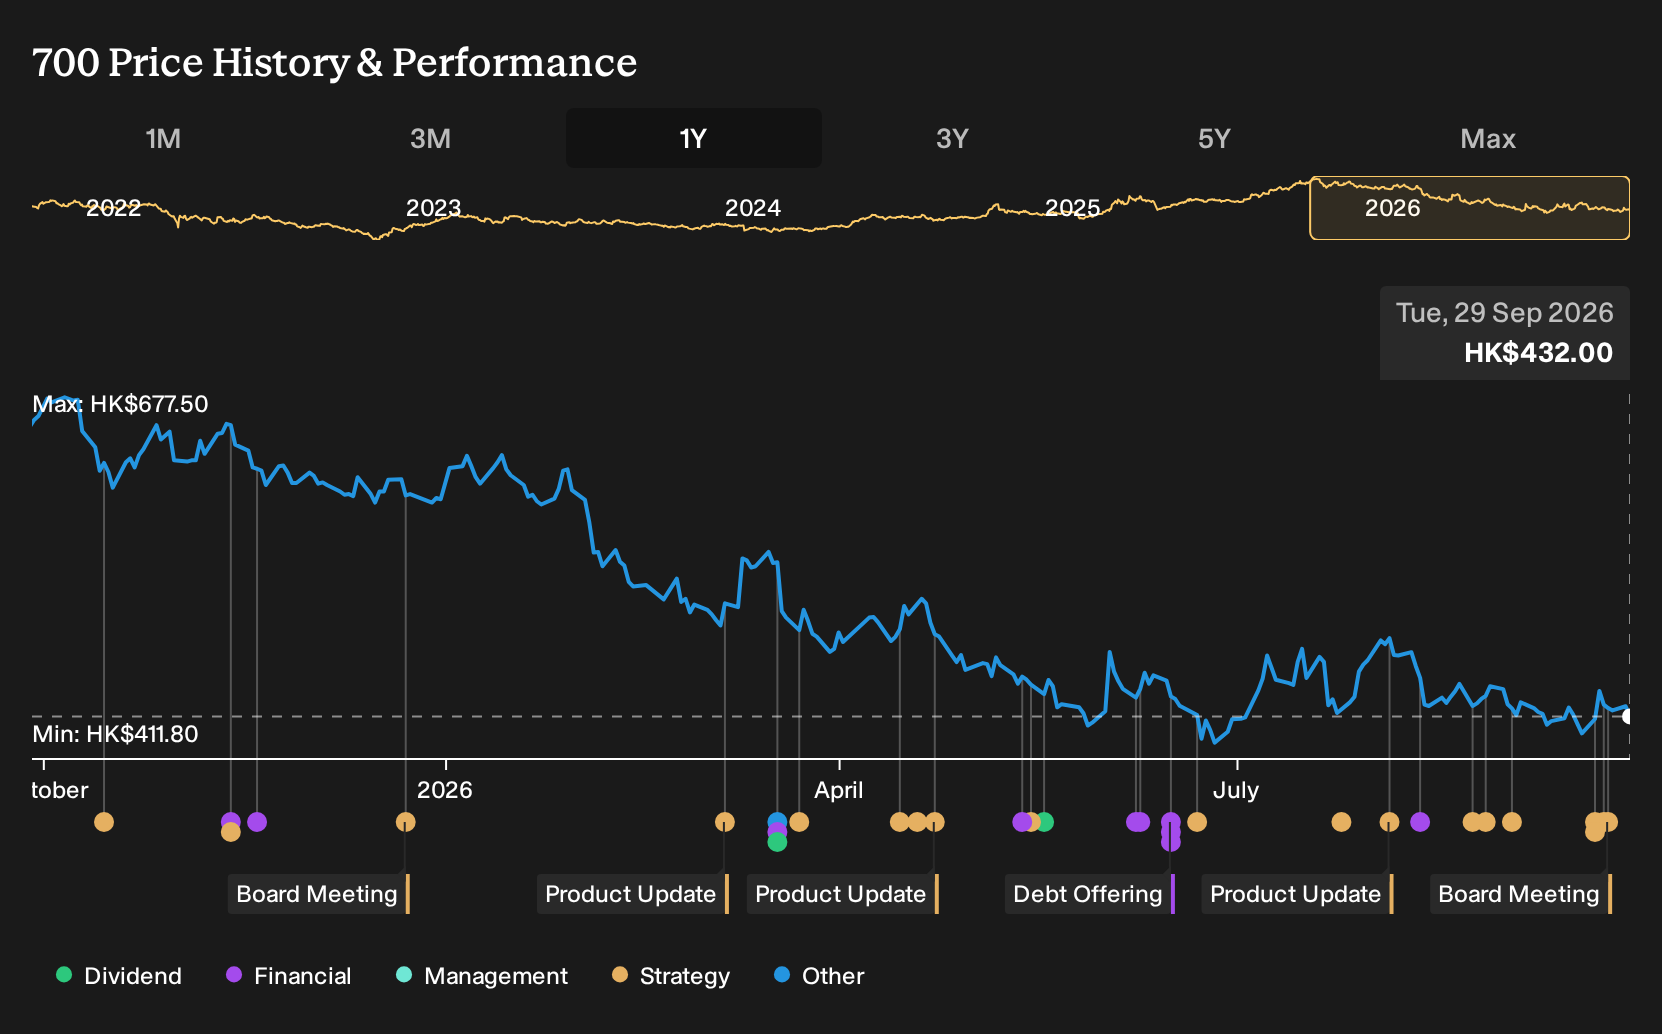
Exploring Other Perspectives
Some of the most optimistic analysts focus on Tencent Holdings' AI agents as a separate upside story. They were already pencilling in CN¥1,105.6b of revenue and CN¥314.2b of earnings by 2029 before this DataBuddy launch. That is far above the bearish CN¥237.2b earnings view. Opinions clearly differ, so it pays to compare several narratives and decide which fits your expectations for how this week’s news might reshape Tencent’s path.
Explore 6 other Tencent Holdings fair value estimates, including one that suggests as much as 54% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tencent Holdings research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Tencent Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tencent Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Tencent Holdings?
Once you have a handle on Tencent Holdings, it can help to widen the lens and see how other companies line up on quality, value, and resilience using the Simply Wall St Screener.
- Focus on potential mispricing opportunities by scanning a curated set of 198 high quality undervalued stocks that pair solid fundamentals with more appealing entry points.
- Prioritise resilience and capital strength by reviewing a list of solid balance sheet and fundamentals (203 results) that can help you see which businesses may be better positioned for shocks.
- Hunt for under followed stories by checking out a 618 high quality undiscovered gems that combines financial strength with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com