
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Canadian Undervalued Stocks With ROE Over 22%
Australia’s central bank just pushed interest rates to a 15 year high, which has hit expensive, widely owned blue chips hard and pushed many investors to the sidelines. That kind of stress can leave smaller, financially solid Canadian companies overlooked and mispriced. This article highlights three under the radar Canadian small caps with strong balance sheets and resilient business models that screen as high quality on fundamentals.
The three stocks below are just a small sample of the opportunity. The full screen surfaced 6 more Canadian small caps with equally compelling stories that are not covered in this article. To identify those potential high quality undiscovered gems for yourself, head straight to the High-Quality Undiscovered Gems screener and use it to filter, analyze, and focus on your highest conviction ideas.
Minco Capital (TSXV:MMM)
Overview: Minco Capital is a Vancouver based investment firm that takes minority stakes in under followed public and private small caps.
Operations: The business currently generates about $4 million from acquiring and selling equity investments in other companies that it holds in its portfolio.
Market Cap: $6.9 million
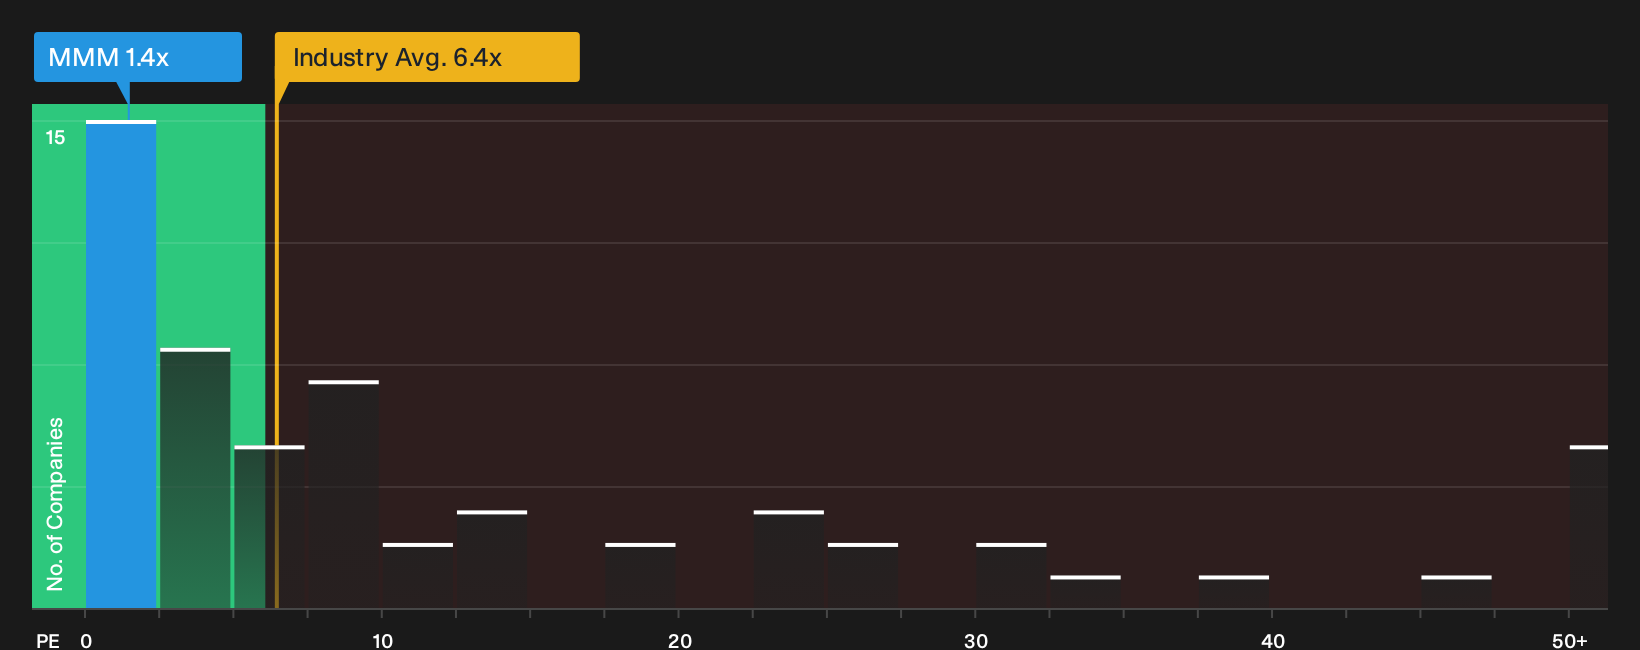
Minco Capital fits directly into the High Quality Undiscovered Gems theme by hunting for overlooked early stage businesses and taking meaningful minority positions. High ROE and a 1.4x P/E indicate that the market may not be fully pricing that portfolio. Investor attention now focuses on how one unseen pressure affects the outcome from those holdings.
That pressure on hidden positions makes it worth checking the 2 key rewards and 2 important warning signs (1 is major!) to see what might be quietly stretching or compressing Minco Capital’s valuation.
Amerigo Resources (TSX:ARG)
Overview: Amerigo Resources is a Vancouver based copper producer that processes tailings from Chile’s El Teniente mine into copper and molybdenum concentrates, directly linking the business to the electrification theme.
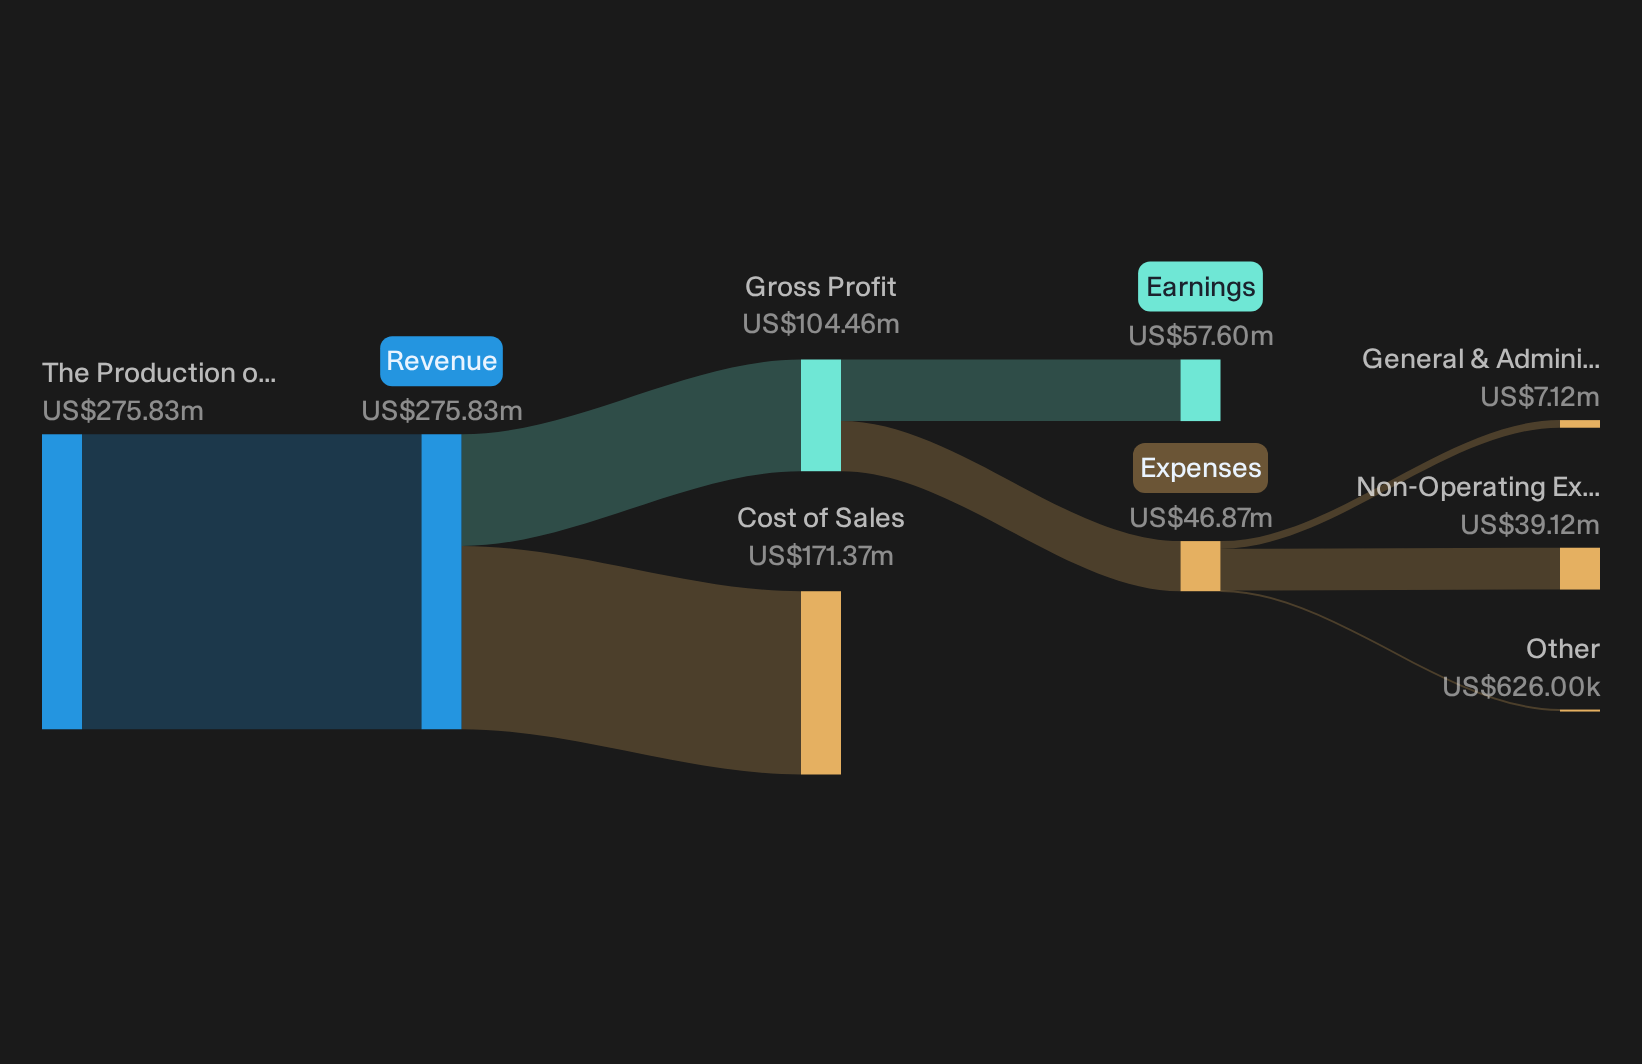
Operations: Amerigo Resources generates about US$276 million by producing copper concentrates under a tolling agreement with El Teniente in Chile, its sole operating region.
Market Cap: CA$1.47b
Amerigo Resources fits into the High Quality Undiscovered Gems theme through copper and molybdenum output from El Teniente tailings, with H1 2026 showing strong sales, high margins, substantial ROE and active cash returns via dividends and buybacks, while investor outcomes still depend on how one unseen pressure affects those margins over time.
That pressure on Amerigo Resources’ margins is exactly what you can unpack in the 1 key reward and 2 important warning signs to see what might be masking the real story.
Fortuna Mining (TSX:FVI)
Overview: Fortuna Mining is a Vancouver based miner producing gold from the Lindero and Séguéla mines, complemented by silver and base metal operations across Latin America and West Africa.
Operations: Fortuna Mining generates about $680 million from Sango, $357 million from Mansfield and $145 million from Bateas, largely in Ivory Coast and Argentina.
Market Cap: CA$4.9b
Fortuna Mining fits the High Quality Undiscovered Gems theme through its producing gold mines that already generate cash while larger funds still pay more attention to bulkier peers.
"Expansion at Seguela and the development of Diamba Sud position Fortuna to restore and surpass its previous production levels, with higher-margin and longer-life ounces, aligning with anticipated increases in global demand for gold and other strategic metals, supporting future revenue and cash flow growth."
The key question is whether one unseen pressure allows those higher quality ounces to translate into the margin profile institutions tend to prize.
If that pressure on margins is what you care about, go straight to the full narrative for Fortuna Mining to see how Fortuna Mining’s risk and upside really line up.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities move fast. Breakout stories build momentum while they are still under the radar for now, and information edge drops quickly. Scan the next wave and get in early.
- Spot cash rich operators and reduce balance sheet surprises by running the list of solid balance sheet and fundamentals (7 results) before the crowd wakes up to them.
- Ride structural demand for electrification and infrastructure by tracking future facing metals producers through the 16 top copper producer stocks while prices still look reasonable.
- Lock in income ideas with staying power by using the 1 dividend fortresses to pinpoint payout streams that aim to keep flowing even when headlines turn.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com