
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Altamira Gold (CVE:ALTA) In A Good Position To Deliver On Growth Plans?
Even when a business is losing money, it's possible for shareholders to make money if they buy a good business at the right price. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. Nonetheless, only a fool would ignore the risk that a loss making company burns through its cash too quickly.
So, the natural question for Altamira Gold (CVE:ALTA) shareholders is whether they should be concerned by its rate of cash burn. In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. Let's start with an examination of the business' cash, relative to its cash burn.
When Might Altamira Gold Run Out Of Money?
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. When Altamira Gold last reported its May 2026 balance sheet in July 2026, it had zero debt and cash worth CA$5.5m. In the last year, its cash burn was CA$6.2m. That means it had a cash runway of around 11 months as of May 2026. To be frank, this kind of short runway puts us on edge, as it indicates the company must reduce its cash burn significantly, or else raise cash imminently. Depicted below, you can see how its cash holdings have changed over time.
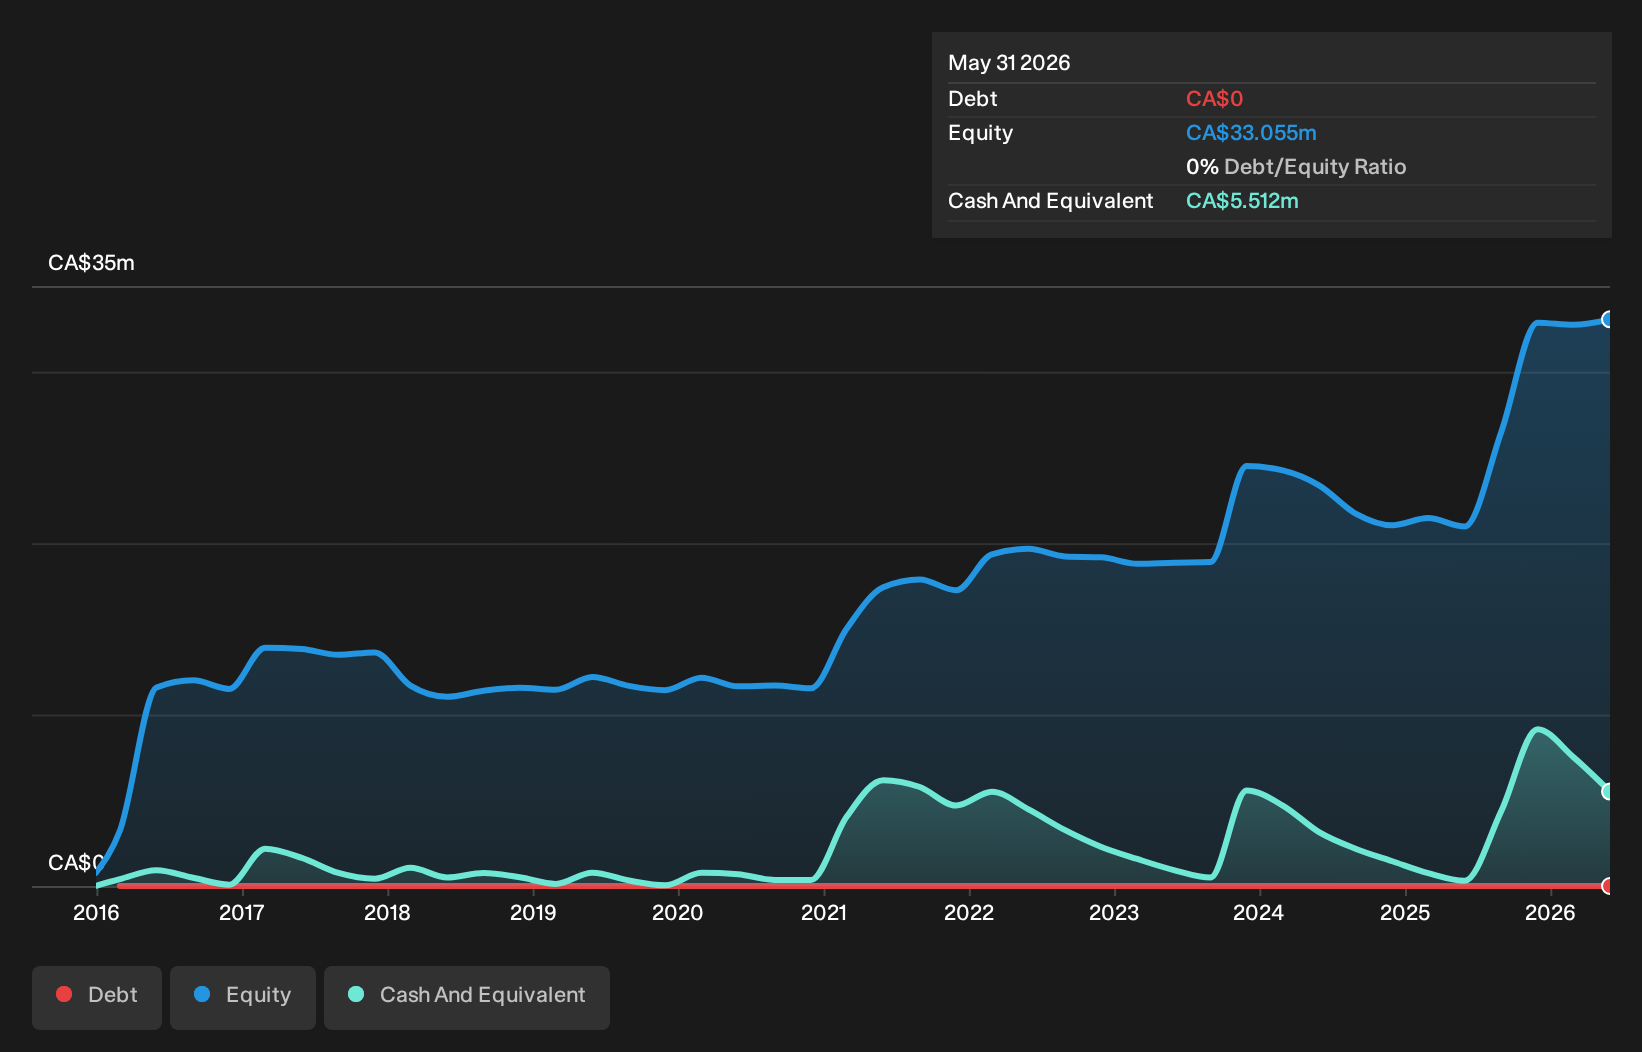
Check out our latest analysis for Altamira Gold
How Is Altamira Gold's Cash Burn Changing Over Time?
Because Altamira Gold isn't currently generating revenue, we consider it an early-stage business. So while we can't look to sales to understand growth, we can look at how the cash burn is changing to understand how expenditure is trending over time. In fact, it ramped its spending strongly over the last year, increasing cash burn by 117%. That sort of spending growth rate can't continue for very long before it causes balance sheet weakness, generally speaking. Altamira Gold makes us a little nervous due to its lack of substantial operating revenue. So we'd generally prefer stocks from this list of stocks that have analysts forecasting growth.
How Easily Can Altamira Gold Raise Cash?
Since its cash burn is moving in the wrong direction, Altamira Gold shareholders may wish to think ahead to when the company may need to raise more cash. Generally speaking, a listed business can raise new cash through issuing shares or taking on debt. Commonly, a business will sell new shares in itself to raise cash and drive growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Altamira Gold's cash burn of CA$6.2m is about 7.6% of its CA$82m market capitalisation. That's a low proportion, so we figure the company would be able to raise more cash to fund growth, with a little dilution, or even to simply borrow some money.
How Risky Is Altamira Gold's Cash Burn Situation?
Even though its increasing cash burn makes us a little nervous, we are compelled to mention that we thought Altamira Gold's cash burn relative to its market cap was relatively promising. Even though we don't think it has a problem with its cash burn, the analysis we've done in this article does suggest that shareholders should give some careful thought to the potential cost of raising more money in the future. Separately, we looked at different risks affecting the company and spotted 5 warning signs for Altamira Gold (of which 4 don't sit too well with us!) you should know about.
Of course Altamira Gold may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.