
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
High K Chip Demand Could Change Lam Research (LRCX) Stock Narrative
- Recent industry research profiles Lam Research as a leading supplier of High K dielectric materials used in advanced logic, 3D memory, GaN and SiC power devices, and sensor fabrication.
- The focus on High K materials highlights Lam Research’s exposure to chip scaling and low power device requirements that rely on atomic layer deposition process expertise.
- We will now look at how Lam Research’s High K dielectric exposure could influence the broader investment narrative around its equipment business.
Scan other High K and advanced fabrication plays positioned around Lam Research’s segment by comparing the 87 AI infrastructure stocks that are powering the next wave of chip scaling and low power electronics.
Lam Research Investment Narrative Recap
To own Lam Research, you need to believe that wafer fab equipment demand tied to AI, 3D architectures and High K materials can stay healthy enough for the company to keep filling its tools and services pipeline. The High K dielectric market report fits that view by placing Lam Research alongside other key suppliers, but it does not materially change the near term story.
The key short term swing factor remains the pace and timing of AI heavy fab projects that underpin Lam Research’s order book. The biggest risk still sits with export controls and exposure shifts away from China, which could make regional spending more uneven. At the same time, a higher tax rate limits how much earnings benefit from any operational strength.
Recent commentary around High K adoption ties back to Lam Research’s existing push into 3D architectures such as gate all around, backside power and higher NAND layers. Management links these trends to a higher served market share. That inflection is already embedded in the current narrative, and this new market study largely reinforces that the processing steps Lam Research targets are in focus for chipmakers.
The company’s more than US$3b of committed global R&D lab investments, including the Oregon AI semiconductor lab expansion, looks particularly relevant in this context. These labs give Lam Research a place to refine High K and atomic layer deposition processes with customers, which matters for tool acceptance, installed base growth and, over time, the recurring support revenue that helps smooth through regional or policy related spending swings.
Lam Research is currently framed around analyst expectations that revenues reach US$46.4b and earnings come in at US$17.7b by 2029. These expectations are anchored to an assumed 25.9% yearly top line growth rate and a move from US$7.3b of earnings today to a forecast level that is about US$10.4b higher.
Uncover why Lam Research's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
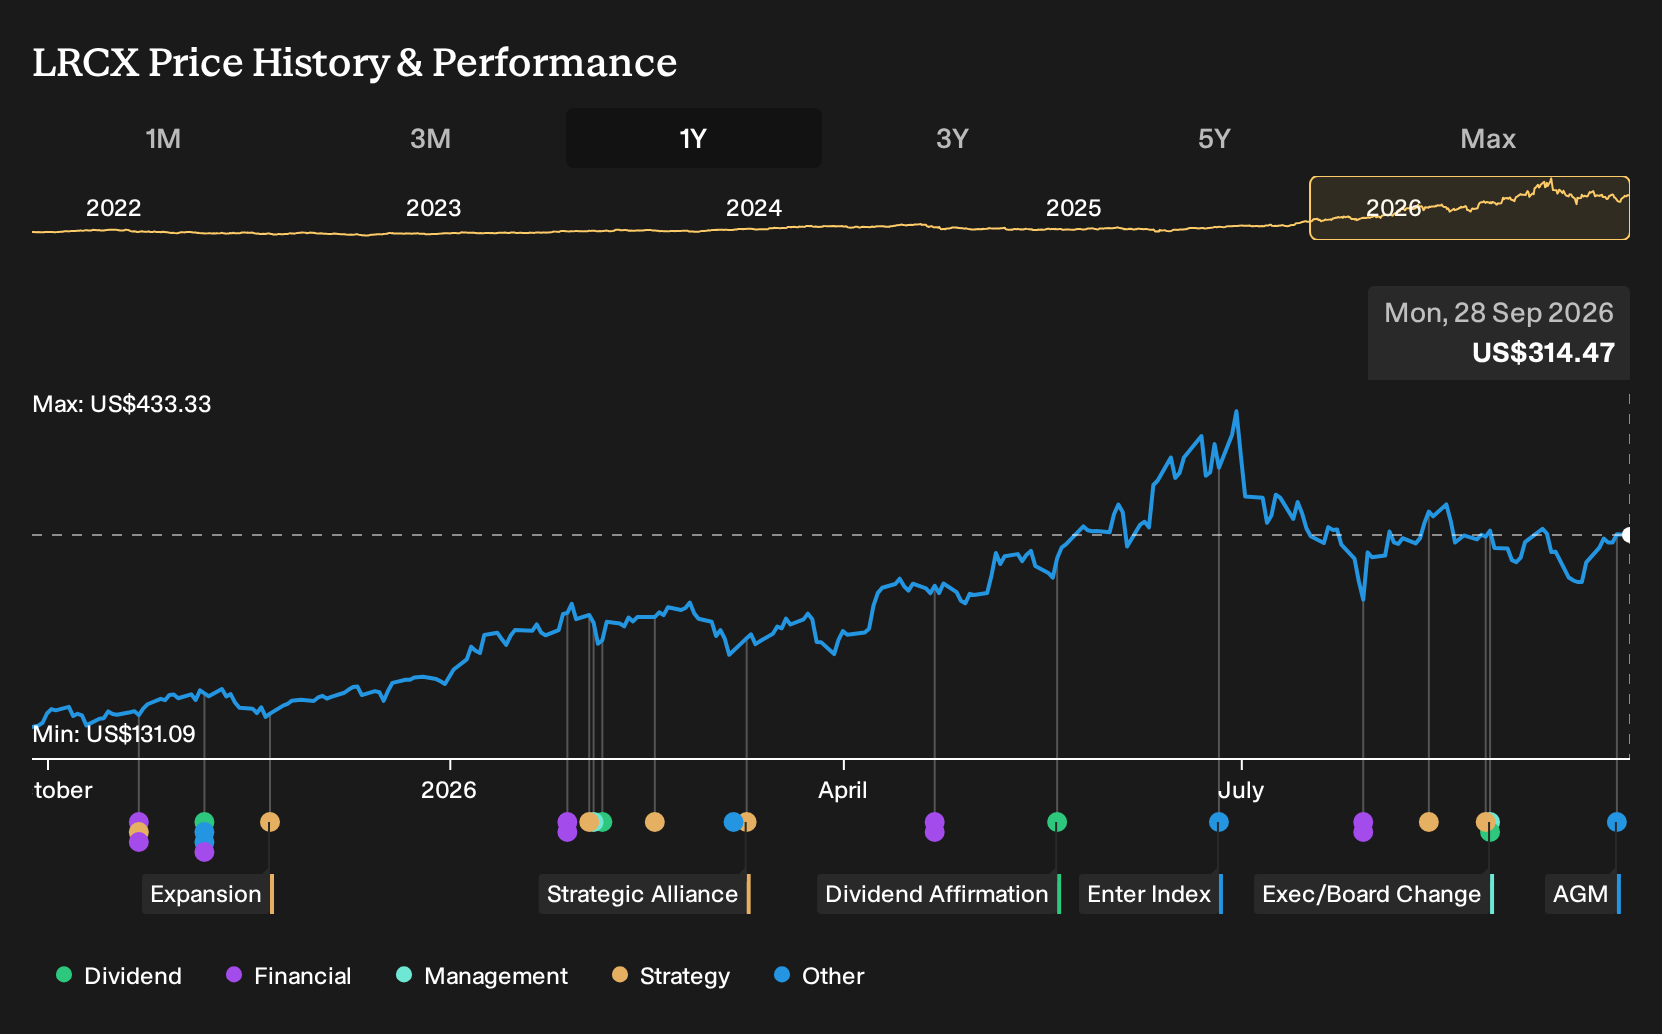
Exploring Other Perspectives
One alternate view zeroes in on deglobalization risk. The most cautious analysts worry that tighter export rules around China could leave Lam Research with slower growth than consensus, which is why their pre news models only had revenues reaching about US$38.6b and earnings near US$14.3b by 2029. Those expectations are meaningfully lower than the baseline forecasts, and the new High K focus could push both narratives to shift.
Explore 8 other Lam Research fair value estimates, including one that suggests as much as 47% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Lam Research research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lam Research. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lam Research's overall financial health at a glance.
Looking For More Ideas Beyond Lam Research?
If you want to stress test your Lam Research view against other opportunities, using a structured stock screener can help you quickly surface candidates that match the kind of balance sheet strength, income potential, or risk profile you are aiming for.
- If capital preservation sits high on your priority list, you can filter for companies with more defensive profiles using our 30 resilient stocks with low risk scores, which may better match your tolerance for swings.
- Income focused investors can scan for higher yield opportunities by reviewing the 6 dividend fortresses, which may suit a portfolio anchored around regular payouts.
- Those hunting for potential overlooked stories can cast a wider net with the 16 high quality undiscovered gems, which pair solid fundamentals with lower current market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com