
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Guoco Group (SEHK:53) Stock Flags Margin Pressure Behind Low P/E
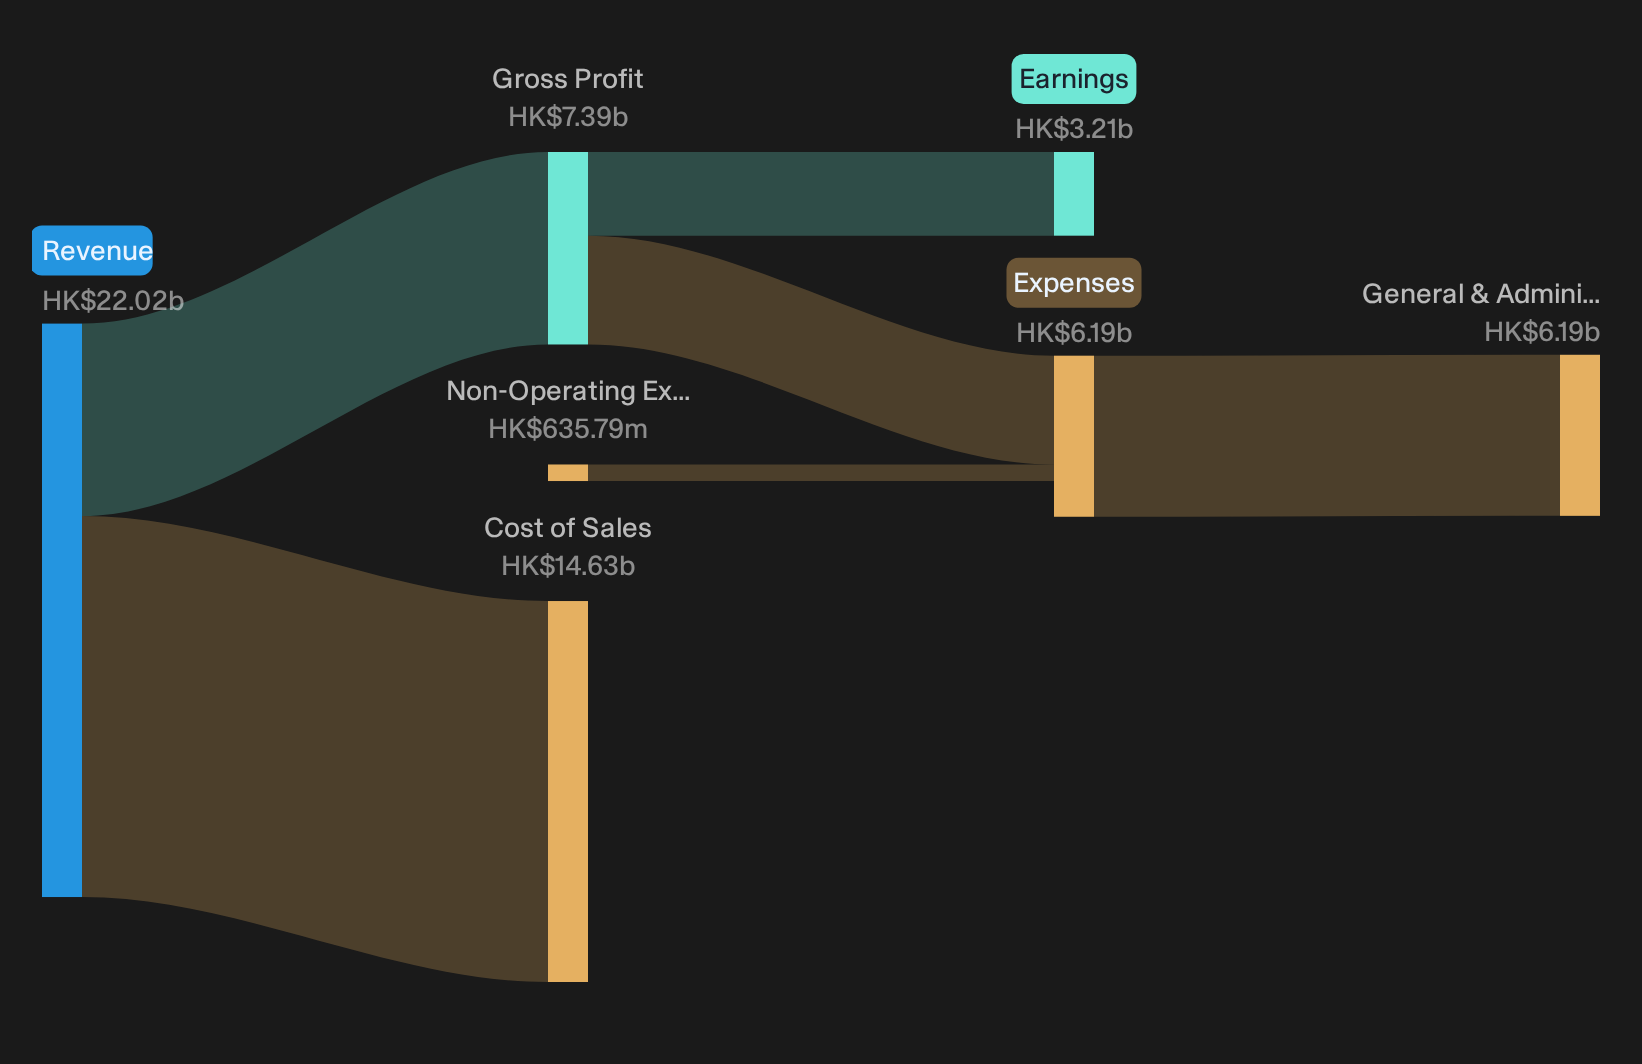
Guoco Group shares barely budged into the earnings release, with the stock flat over the past week and only a modest 7% gain across three months. The headline is not the price action. The real story is a profit squeeze that has chipped net margin down to 14.6% over the last year from 16.5%.
That pressure lands on a business trading on a 7.3x trailing P/E and a market value that sits far below an estimated cash flow figure of HK$279.18 per share. In the short term, the reaction looks muted. Over a multi year horizon, the valuation gap and earnings strain are the key factors.
Love Guoco Group's low 7.3x P/E but concerned that a shrinking net margin could point to a value trap rather than a bargain? Take a look at our 198 high quality undervalued stocks for a curated list of stocks that pair discounted valuations with stronger profitability support.
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs Q4 2025): HK$5,127.72m vs. HK$5,861.50m (decline of roughly 12.5%)
- Net Income (Excl. Extra Items, Q4 2026 vs Q4 2025): HK$586.02m vs. HK$1,111.04m (decline of roughly 47.3%)
- Basic EPS (Q4 2026 vs Q4 2025): HK$1.80 vs. US$3.42 (directional comparison limited by different reporting currencies)
- Net Profit Margin (TTM vs Prior Year): 14.6% vs. 16.5% (compression of 1.9 percentage points over the last 12 months)
Prefer clean visuals instead of another wall of earnings tables and margin figures? See Guoco Group's full valuation picture presented in simple charts and key ratios with our company report for Guoco Group.
Bullish Signals: Diversification And Portfolio Tidy-Up
For anyone leaning positive on Guoco Group, the earnings still leave a narrow path for a constructive view. The group runs a broad mix of businesses, so pressure in one area does not automatically break the whole story. Management is also simplifying where it can. The move to privatise GuocoLand Malaysia and delist it by July 2026 points to a cleaner property structure and more direct control over capital. That kind of tidying up can support the idea that a diversified platform is being managed with more focus, even as margins come under strain.
Bearish Signals: Profit Compression And Slower Momentum
The latest figures give plenty for cautious investors to point to. Revenue fell from HK$5,861.50m to HK$5,127.72m and net income excluding extra items dropped from HK$1,111.04m to HK$586.02m. That is a heavy hit to earnings power in a single quarter. Net profit margin over the last year compressed from 16.5% to 14.6%, so the squeeze is not just one noisy period. Guoco Group still benefits from diversification, but the mix is not currently shielding overall profitability. For now, the earnings trend leans toward validation of the more bearish narrative.
After a quarter where revenue and earnings both weakened, are you sure margin pressure is the only concern here, or could Guoco Group face deeper structural issues? Review our independent risk analysis for Guoco Group which shows 1 important warning signStay Ahead Of Your Next Move
Compressed margins and a low P/E make Guoco Group a stock that can shift from opportunity to risk quickly, so register for free with Simply Wall St and add it to a Watchlist to keep price and fair value on your radar before deciding on an entry. After you own any shares, use the Portfolio Command Center to cut through noise and surface only the most important changes that could affect your thesis. For longer term investors who want a broader view, the Community helps you weigh different angles from other investors looking at the same data. By spotting potential catalysts and problems early, you give yourself a better chance to act ahead of the wider market.
Seeking Alternatives Beyond Guoco Group?
Fresh ideas move first, and hesitation often gets caught on the wrong side of a breakout or a dropping chart. Scan under the radar for now and act now.
- Spot resilient momentum early and review 223 resilient stocks with low risk scores that keep downside in check while you focus on upside potential others ignore.
- Target income strength and assess 165 dividend fortresses built around businesses aiming to sustain higher yields while many investors still chase pure price moves.
- Hunt for future infrastructure winners and compare 39 power grid technology and infrastructure stocks before grid upgrades and electrification stories move from quiet thesis to crowded trade.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com