
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Indian Dividend Stocks With Yield Over 3%
India is preparing up to $25b for deep tech, and that kind of long term capital commitment can reshape cash flows across the local market. In a world where growth stories can be unpredictable, reliable Indian dividend payers yielding more than 3% offer a different kind of comfort. This article highlights three income focused stocks from that universe that aim to pair steady payouts with disciplined balance sheets.
The three stocks below are just a sample of what income investors can find, while the full screen surfaced 45 more companies with similarly compelling dividend stories that are not covered in this article.
If you want to identify stronger cash return candidates and analyze payout strength in one place, head straight into the Dividend Powerhouses (3%+ Yield) screener.
Emami (BSE:531162)
Emami is a consumer products group built around cash-generative personal care and healthcare brands that fit neatly with the screener’s focus on covered, stable dividends. This makes its income profile especially relevant if you prize predictability from everyday repeat purchases.
Emami generates about ₹39.1b in revenue from personal and healthcare products, spanning BoroPlus, Navratna, Zandu, Kesh King and more, and has a market value near ₹169.7b. This focused FMCG engine is what helps underpin the dividend theme for long term income investors.
"Expansion in modern trade and e-commerce will improve sales, but the real upside lies in accelerating adoption in rural and semi-urban India, where digital penetration and D2C platforms are still in the early innings. Emami's omnichannel scale and digital-first brand portfolio could unlock substantial incremental volume growth and repeat usage."
The real swing factor for Emami’s dividend story is how one quiet shift in its profitability mix plays out over the next few years.
That profitability mix is exactly what the full narrative for Emami unpacks in full, highlighting where Emami’s cash engine could be quietly accelerating or masking future risks.

Bhansali Engineering Polymers (BSE:500052)
Bhansali Engineering Polymers runs a petrochemical operation focused on ABS and SAN thermoplastic resins for autos, appliances and electronics, generating about ₹14,402 million from this line and carrying a market value near ₹31.1b. This combination is what anchors its dividend powerhouse profile.
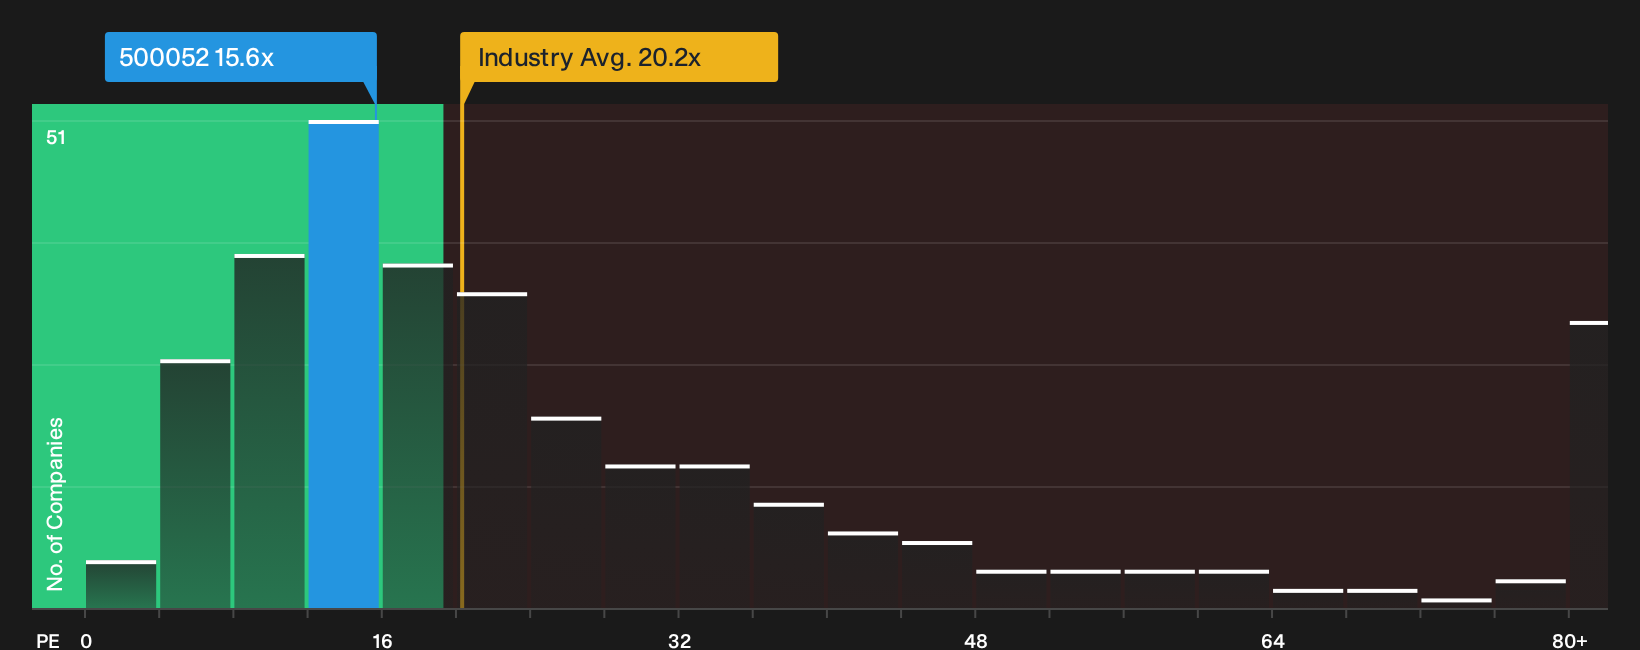
A 3.2% yield, earnings labeled high quality and a P/E of 15.6x compared with higher sector multiples present Bhansali Engineering Polymers as an income idea with a value tilt. However, dividend reliability still depends on how pressure in its funding mix and profit trend evolves.
That pressure is exactly what the 2 key rewards and 1 important major warning sign maps out, so you can see where Bhansali Engineering Polymers’ dividend story could sharpen or stall next.
Gujarat Energy (NSEI:GUJENERGY)
Gujarat Energy taps into the Dividend Powerhouses theme through a city gas distribution network that throws off recurring cash flows, which helps support a covered and stable payout for income focused investors.
Gujarat Energy runs a large city gas distribution network supplying piped natural gas to households and businesses, with about ₹196.4b from city gas and ₹194.9b from gas trading, alongside smaller power and regasification lines. This gives it India based revenue of ₹273.1b and a market value near ₹220.5b.
For a yield screen built around reliability, Gujarat Energy offers a mix of contract backed cash flows, regulated exposure and a clear link between its pipes in the ground and the dividends hitting your account.
"The accelerating shift towards renewable energy sources and electrification, such as solar, wind, and electric vehicles, is expected to significantly reduce India's long-term natural gas demand, eroding Gujarat Gas's core revenue streams and limiting growth in both household and industrial consumption."
What matters next is how one emerging squeeze on funding and payout choices shapes the trade off between today’s income and tomorrow’s growth capacity.
That capital trade off is exactly where the full narrative for Gujarat Energy goes deeper, showing how Gujarat Energy could turn today’s gas squeeze into tomorrow’s compounding cash engine.

Seeking Alternatives Before The Crowd?
Fresh themes keep breaking out while older stories lose momentum fast. Screen for under the radar ideas before they start flying and the window drops, and aim to get in at an earlier stage.
- Target rock solid balance sheets and resilient cash generators by filtering the list of solid balance sheet and fundamentals (203 results) so you focus on businesses built to handle real world shocks.
- Look for targeted AI-related opportunities by scanning 37 profitable AI stocks that aren't just burning cash where earnings already play a role and the market may not have fully reflected the shift.
- Evaluate potential metals supply constraints by reviewing the curated 36 elite gold producer stocks and stress testing which producers fit your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com