
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Kroger (KR) Is Getting Attention Today
Kroger (KR) has started piloting 24-hour store operations in select Ohio and Indiana locations after reporting 0.2% identical sales growth in the second quarter of 2026 and losing consumer packaged goods spending to large rivals.
For investors tracking Kroger, the latest 1 day share price return of 1.62% and 90 day share price return of 7.49% point to rebuilding short term momentum, even as the year to date share price return is still down 5.19%. Meanwhile, the 3 year and 5 year total shareholder returns of 44.96% and 67.88% show that longer term holders have seen significantly stronger outcomes overall.
Contrast Kroger's reset with a curated set of resilient retailers by scanning the list of solid balance sheet and fundamentals (25 results), which may be better positioned to handle shifting consumer traffic and tight grocery margins.
For Kroger, modest sales progress, a bond raise and fresh buybacks now sit against a stock that has already rebounded in recent months. Does that mix still tip the risk reward in favour of new buyers?
Most Popular Narrative: 9.1% Undervalued
Kroger last closed at $59.69, while the most followed narrative pegs fair value at $65.65, implying a modest valuation gap that hinges on how durable its new operating model really is.
The central narrative tension of the latest call is the gap between two clean stories: cost discipline working exactly as committed, and the sales line missing the guidance range. Foran’s response was to present these as compatible, a demonstration that the financial model works even when top-line conditions do not cooperate.
See why 2 investors see Kroger as 9% undervalued.
Result: Fair Value of $65.65 (UNDERVALUED)
Still, Kroger’s thesis leans heavily on cost cuts outpacing soft sales, and any stumble in store execution or e-commerce profitability could quickly unravel that narrative.
Find out about the key risks to this Kroger narrative.
Another View on Kroger’s Valuation
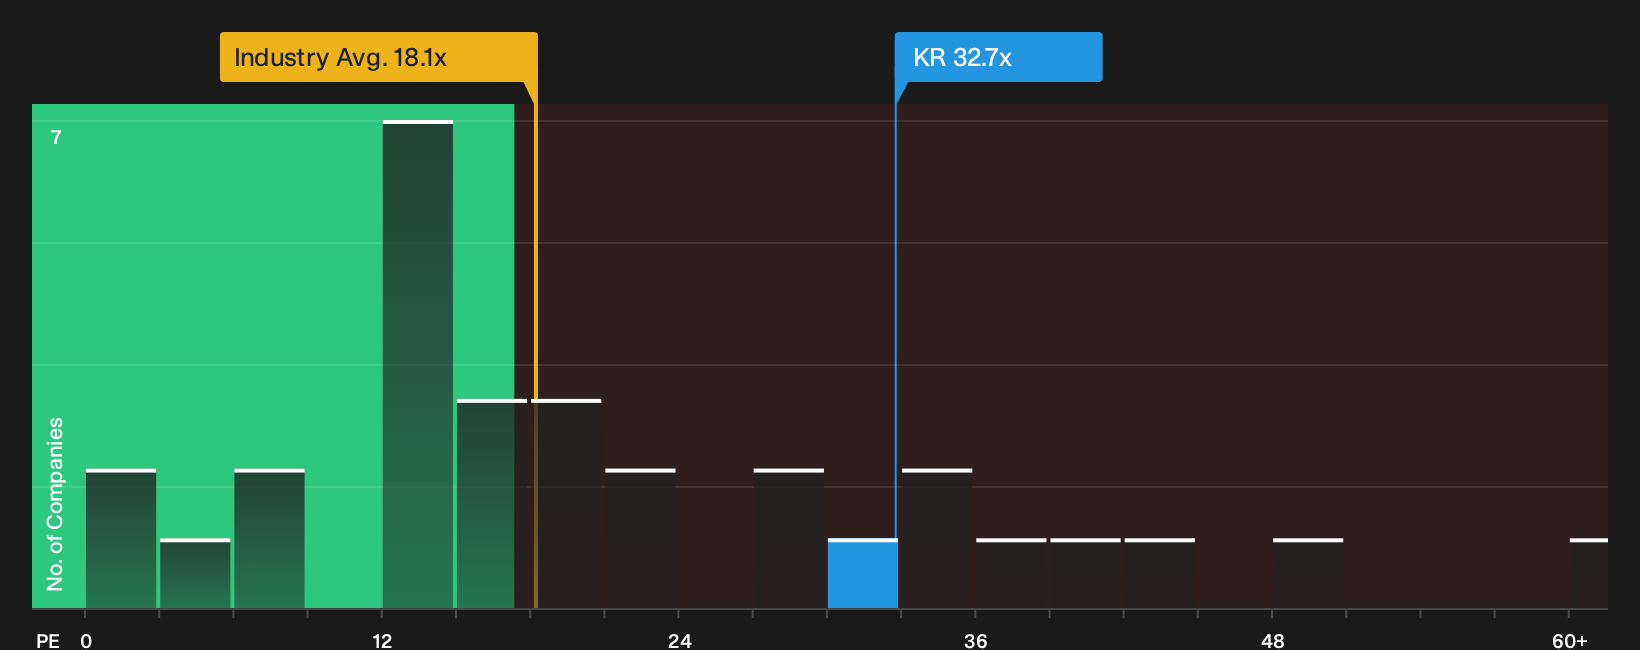
The first narrative pegs Kroger at 9.1% below an estimated fair value of $65.65, yet the share price also sits on a P/E of 32.7x versus 18.1x for the US Consumer Retailing industry and a fair ratio of 31.6x. That mix suggests investors need to weigh upside against paid-up expectations.
For a closer look at what this richer earnings multiple might mean in practice, including how peers are priced and where the fair ratio could drift over time, see the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
With Kroger raising both concerns and optimism, your best edge is to examine the moving parts for yourself and decide whether the trade off suits you. Take a closer look at the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Kroger?
If Kroger has your attention, do not stop there. Use the Simply Wall St Screener to surface other opportunities that fit your style before the crowd moves on.
- Target steadier potential by scanning resilient businesses with stronger downside protection through the 30 resilient stocks with low risk scores.
- Hunt for value opportunities that combine quality with pricing support by checking the 16 high quality undiscovered gems.
- Focus on income potential and cash return by reviewing companies in the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com