
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
InterDigital (IDCC) Could Be 29% Undervalued On Its Licensing Growth Story
InterDigital (IDCC) draws investor attention as a US$8.62b research and development specialist in wireless and visual technologies, with US$788.50m in communications software revenue and US$302.18m in net income shaping the current investment debate.
Recent trading has been choppy for InterDigital, with the share price down 2.12% on the day and 2.39% over 30 days. However, a 15.54% 90 day share price return alongside a very large 322% three year total shareholder return signals momentum that has built over a multi year horizon rather than faded in recent months.
Scan beyond InterDigital and spot other research driven software stocks with sharp revenue and earnings profiles using our curated list of 16 high quality undiscovered gems.
InterDigital looks like a powerful research engine with solid profitability, yet the share price has cooled over the past month after a strong multi year run. Is this business strength already fully reflected in today’s valuation?
Most Popular Narrative: 29% Undervalued
The prevailing narrative values InterDigital at $462.67 per share, well above the last close of $327.14. This sets a clear gap that investors are trying to explain through licensing momentum and earnings quality rather than rapid top line expansion.
The company is making rapid progress expanding into Consumer Electronics and IoT markets, exemplified by a recent HP agreement (now over 50% of the PC market under license) and a 175% increase in CE and IoT program revenue in Q2, which points to successful diversification and growing addressable market, supporting topline growth and reducing cyclicality.
See why 19 investors see InterDigital as 29% undervalued.
Behind that fair value, the most followed narrative leans on a steady rather than aggressive growth profile. Analysts in that framework assume revenue stays roughly flat over the next three years and net profit margins edge down from 44.2% to about 42.5%, while earnings move from $366.4m today to $350.8m by around June 2029.
The same storyline requires investors to accept a much richer valuation multiple over time. To reach the $462.67 fair value by 2029, the model assumes InterDigital trades on a P/E of 44.0x those earnings, compared with 20.9x today and a current US Software industry average of 25.9x. That implies the market would place a higher price on each dollar of earnings even if profits are not growing rapidly.
A discount rate of 8.71% sits at the core of that pricing logic. It reflects the return used to bring those expected cash flows and earnings back into today's dollars. A slightly lower rate in this latest update increases the present value of the same future stream compared with earlier versions of the model.
Under that lens, the analyst community views recent licensing deals with firms such as Samsung, Apple, HP, Disney and Amazon as key supports for long term royalty visibility rather than one off spikes. The narrative also acknowledges risks around regulation, arbitration outcomes and the timing of new standards like 6G, which could affect how quickly those contracts translate into cash.
Result: Fair Value of $462.67 (UNDERVALUED)
Still, the analyst story could be knocked off course if binding arbitration on the Amazon deal delivers lower royalties or if tighter patent rules compress InterDigital’s margins.
Find out about the key risks to this InterDigital narrative.
Another View: InterDigital Through The Cash Flow Lens
The analyst target paints InterDigital as 29% undervalued, yet Simply Wall St’s DCF model points in the opposite direction. On that measure, the stock at $327.14 screens as expensive versus an estimated future cash flow value of $167.74. Which story seems more realistic?
Look into how the SWS DCF model arrives at its fair value.
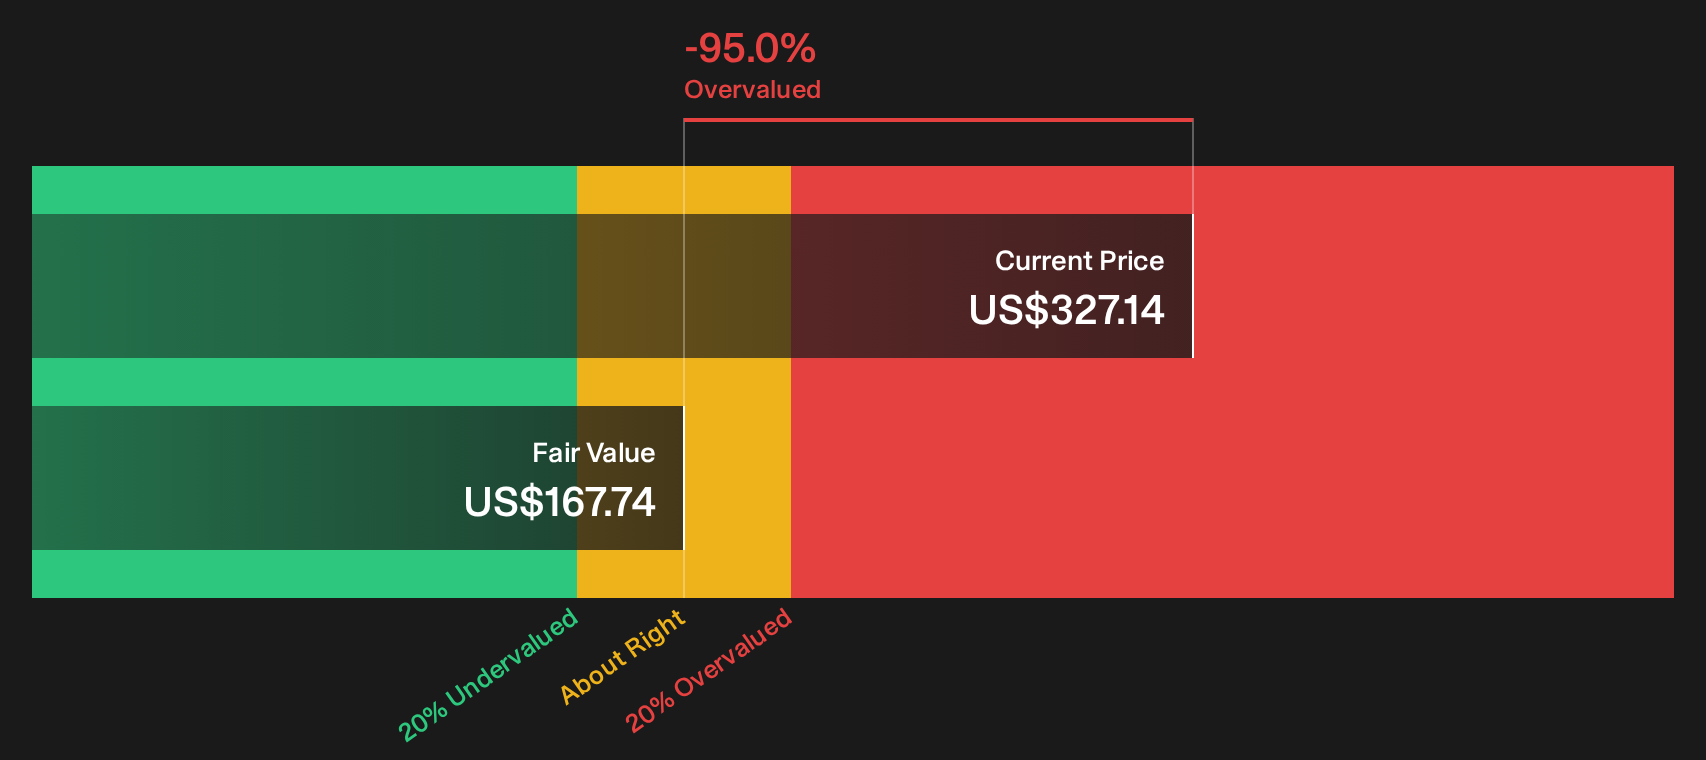
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out InterDigital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on InterDigital in this piece may feel mixed. If you want to move quickly and shape your own view based on the positives the market is watching, start with the 3 key rewards.
Looking for more investment ideas beyond InterDigital?
If InterDigital has sharpened your thinking, do not stop here. Use the Simply Wall St Screener to surface other opportunities that match your investing style.
- Target resilient balance sheets and steady fundamentals with a curated list of solid balance sheet and fundamentals (25 results) that keeps financial strength front and center.
- Hunt for quality at a markdown by scanning the 32 high quality undervalued stocks that filters for strong businesses trading below their assessed worth.
- Prioritize sleep at night potential by focusing on 30 resilient stocks with low risk scores that screens for companies with lower risk scores and sturdier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com