
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sandisk (SNDK) Could Be 19% Undervalued As AI Storage Roadmap Draws Focus
Sandisk (SNDK) is back in the spotlight after management outlined its AI storage roadmap at the 5th Global Memory Innovation Forum on September 23, 2026, which has prompted fresh interest in the stock.
After a huge run earlier in 2026, Sandisk’s momentum has cooled in recent weeks, with the share price down 3.7% over the past day and 3.0% over the week. This comes even as the 1 month share price return is up 15.4% and the 1 year total shareholder return is around 15x, reflecting a mix of profit taking, shifting views on AI demand, and reactions to news around peers and macro risks.
Spot emerging AI infrastructure momentum beyond Sandisk by scanning our hand picked 87 AI infrastructure stocks, which is aligned with the same data center and memory storage theme driving this story.Bulls see Sandisk’s AI storage roadmap and buyback as proof the pullback is overdone. Bears point to cyclicality and AI headline risk. Which side do the current valuation markers back up next?
Most Popular Narrative: 19% Undervalued
Sandisk’s most followed valuation story pegs fair value at about $2,126 per share, well above the last close of $1,712.89. This frames today’s pullback as a gap between narrative and screen price.
Rapid AI and cloud workload expansion is driving data center NAND exabyte growth at a pace well above overall supply. This positions Sandisk's enterprise SSD portfolio and deepening hyperscaler engagements to support sustained revenue acceleration and structurally higher pricing power, benefiting earnings.
See why 136 investors see Sandisk as 19% undervalued.
Result: Fair Value of $2,126 (UNDERVALUED)
Still, if AI demand cools or new NAND capacity flips the market back into oversupply, Sandisk’s pricing power and margin story could quickly look stretched.
Find out about the key risks to this Sandisk narrative.
Another View: SNDK Through The Cash Flow Lens
The first story around Sandisk leans heavily on earnings-based fair value. A very different picture appears when using the SWS DCF model. On that approach, our estimate of future cash flow value sits near $1,204 per share, which is below the current $1,712.89 price, so the stock screens as overvalued on this method. Which yardstick do you trust more when the numbers disagree?
For readers who want to see how that cash flow outcome is built line by line, Look into how the SWS DCF model arrives at its fair value.
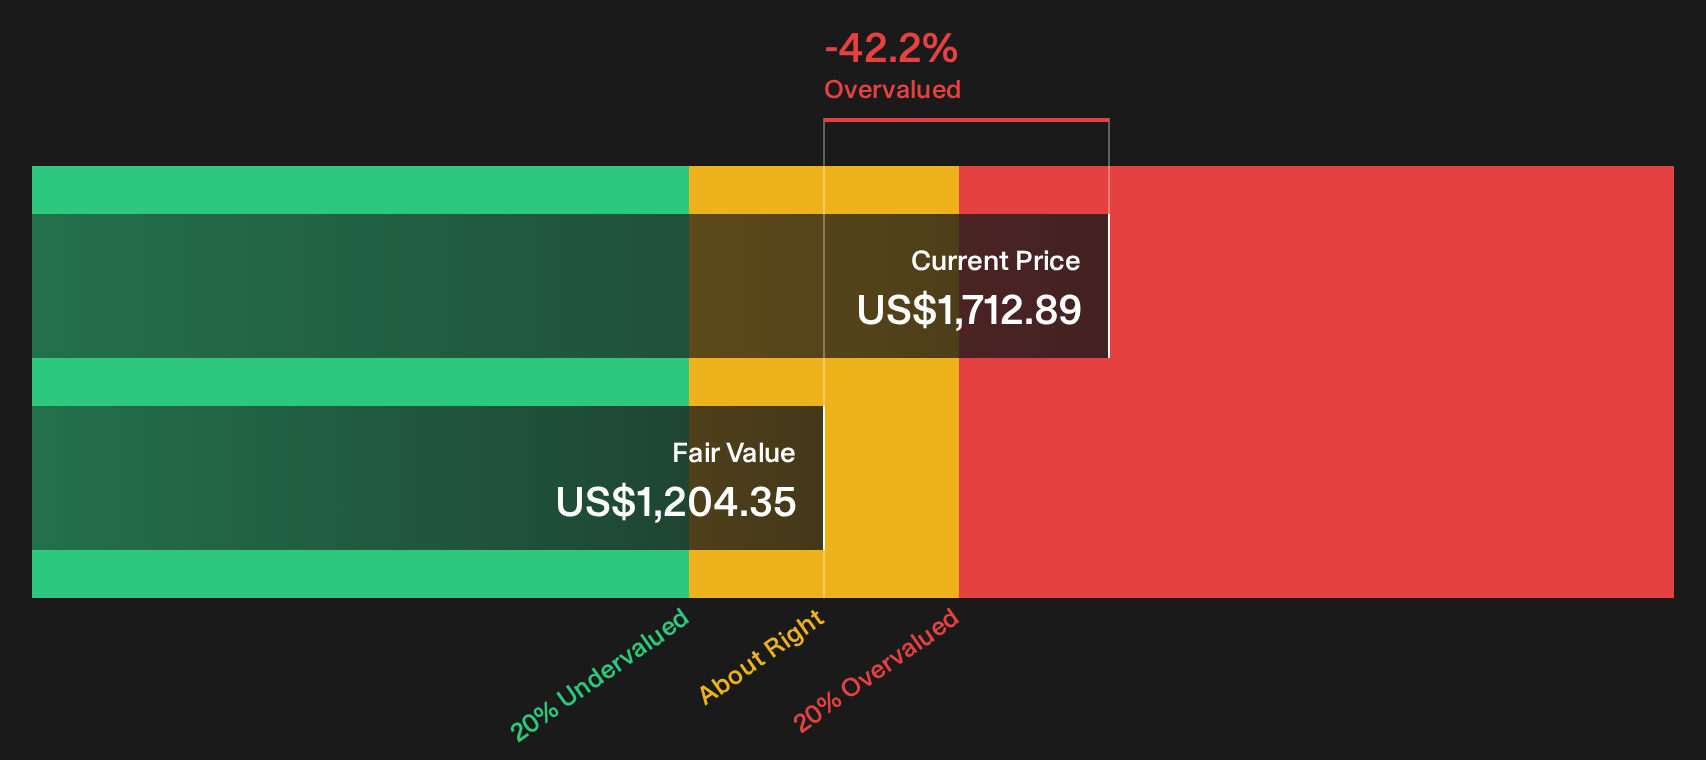
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sandisk for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Sandisk is split. This is exactly when doing your own homework counts most, so move quickly, weigh the data, and stress test both the 3 key rewards and 1 important warning sign
Looking for more Sandisk investment ideas?
Do not stop with Sandisk. Use the Simply Wall St Screener to uncover a broader watchlist so you are not relying on a single AI storage story.
- Target resilient compounding by scanning a 32 high quality undervalued stocks basket that combines stronger fundamentals with prices that screens flag as potentially cheap.
- Prioritize staying in the game by filtering for 30 resilient stocks with low risk scores that may better match a steadier, sleep at night profile.
- Chase under followed potential by sorting through a 16 high quality undiscovered gems list where fundamentals already look solid but attention is still catching up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com