
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is McCormick (MKC) Fully Priced On Earnings Today?
McCormick has seen a long slide in its share price, and with the stock now at US$48.46 the real question for investors is whether that market value still lines up with the earnings behind the seasoning giant. After several years of lacklustre returns, the focus has shifted from the brand story to the income statement.
- Over the past 5 years, the stock has fallen 32.7%, which puts real pressure on the idea that McCormick's current earnings profile can still support the price investors are paying today.
- With UK regulators reviewing the planned US$44.8b deal for Unilever's food assets and the parties agreeing to sell the Colman's mustard brand, the eventual structure and timing of that acquisition may shape how quickly McCormick can convert its scale ambitions into sustained earnings power.
- The analysts covering McCormick have run their own numbers. See what analysts think McCormick's shares could be worth.
The stock's next move may depend on whether McCormick's current share price is properly supported by the earnings it is generating today.
To see whether McCormick's earnings story is unique or part of a broader pattern, compare it with a wider field using the 32 high quality undervalued stocks.
Where Does McCormick Sit on Earnings?
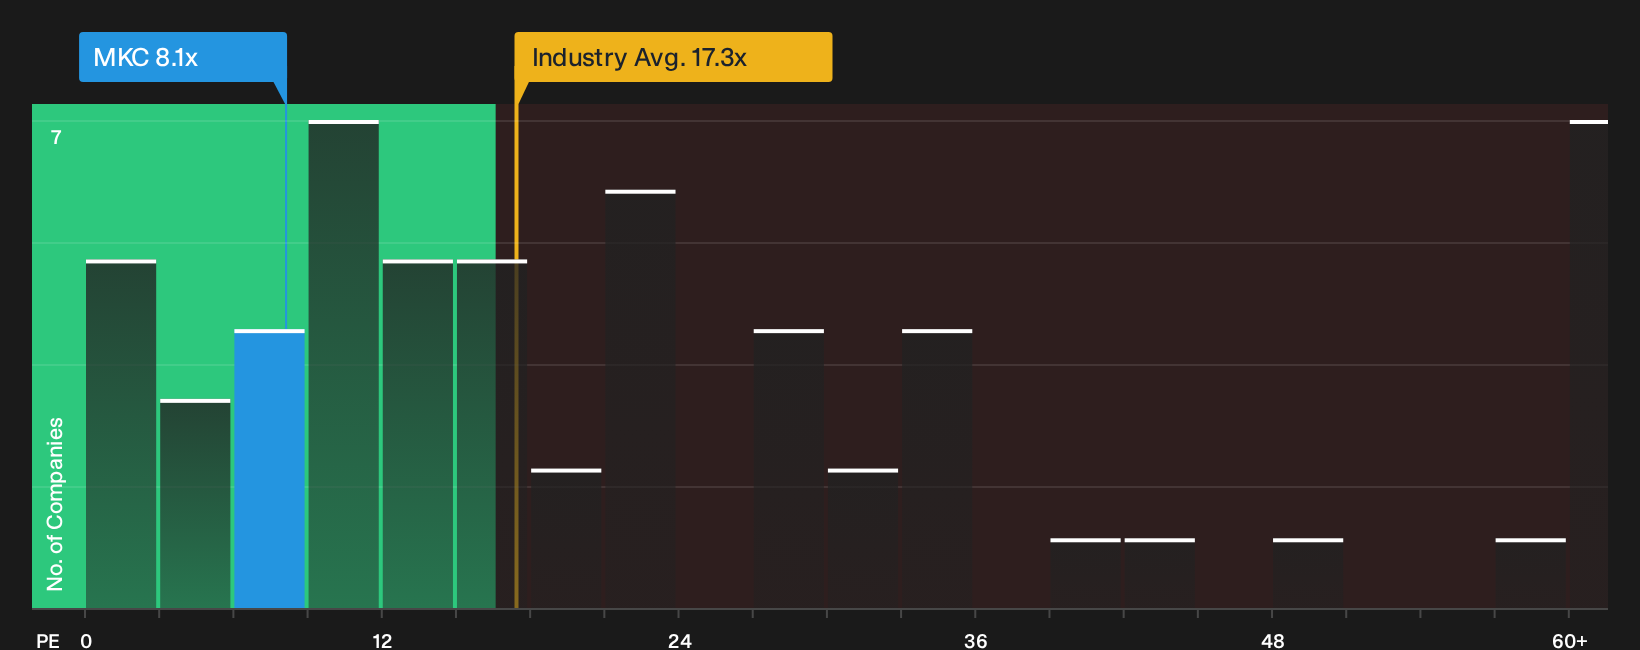
The P/E ratio is a useful fit for a mature consumer staples group like McCormick, where earnings power tends to anchor how investors think about value. McCormick trades on a P/E of 8.1x, which is far below the Food sector average of 17.3x and also well under the peer group at 32.6x. For a stock that has been under pressure, that kind of gap points to a market that is already pricing in a fair amount of caution on future profit quality and growth.
Within this framework, the tailored fair multiple sits close to where McCormick trades today. As a result, the shares appear broadly in line with this measure rather than clearly cheap or expensive on earnings alone. Despite the scrutiny around the planned Unilever food assets deal and the potential reshaping of the product mix, the current P/E still leaves McCormick valued at a marked discount to the wider peer set, which puts the burden back on the underlying earnings story to justify any rerating. Explore the numbers behind McCormick's P/E valuation.
The McCormick Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where McCormick's valuation puzzle leaves off by spelling out what future growth, margin profile and earnings path would need to look like for the seasoning group's share price to move meaningfully higher or lower from here, and they sit on the Community page. Each one treats fair value as a hypothesis about McCormick's business that you can watch over time, rather than a single frozen estimate.
One of the top community narratives on McCormick: 19% undervalued
"The main thing that has to go right is execution on integration and productivity, including delivery of the planned Unilever Foods cost synergies…"
Discover why this Narrative puts McCormick at 19% undervalued.
One more McCormick check that belongs beside the price chart
Before you stop at the P/E and deal headlines, pause and look at who actually steers McCormick, how their incentives are structured and whether those rewards truly line up with your interests. See who runs McCormick and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com