
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Everyone Is Watching ASML Holding (ENXTAM:ASML) Today
ASML’s role in the AI equipment cycle
ASML Holding (ENXTAM:ASML) is in focus as investors track how AI chip demand, large fab buildouts, and government incentives like the US CHIPS Act shape orders for its semiconductor tools.
Recent trading captures that tension between excitement around AI equipment demand and profit taking after a strong run. The share price is up 55.83% year to date with a 1-year total shareholder return of 87.41%. However, the past 90 days include a 10.71% decline in share price return that tempers shorter term momentum, while longer term total shareholder returns over 3 and 5 years remain strong.
Scan beyond ASML Holding and identify other equipment players exposed to the same AI capex wave using our curated 87 AI infrastructure stocks.
After a sharp run this year and a recent pullback, ASML Holding trades at a sizeable discount to analyst price targets yet above some intrinsic value estimates. Is the market applying healthy caution, or mispricing a pivotal AI equipment supplier?
Most Popular Narrative: 67.1% Overvalued
ASML Holding last closed at €1,537, while the leading narrative fair value sits at €920, so the story framing the stock is that investors are paying well above what this framework calls reasonable based on its own assumptions and discount rate of 6.46%.
ASML’s story is one of quiet dominance at the heart of global tech. Founded in the Netherlands in 1984, ASML started as a joint venture between Philips and ASM International. Over the decades, it evolved into the sole supplier in the world of extreme ultraviolet (EUV) lithography machines, which are essential for manufacturing the most advanced semiconductor chips (like those powering AI, smartphones, and data centers). These machines are marvels of engineering, costing up to €350 million each, with components sourced globally and assembled with near-impossible precision. Only a handful of customers, TSMC, Intel, Samsung, can afford and operate them, giving ASML a notable technological moat.
See why 51 investors see ASML Holding as 67% overvalued.
Result: Fair Value of €920 (OVERVALUED)
Still, the ASML Holding story can quickly reset if export controls tighten further or if a handful of key customers slow multi-year equipment spending.
Find out about the key risks to this ASML Holding narrative.
Another View on ASML Holding’s valuation
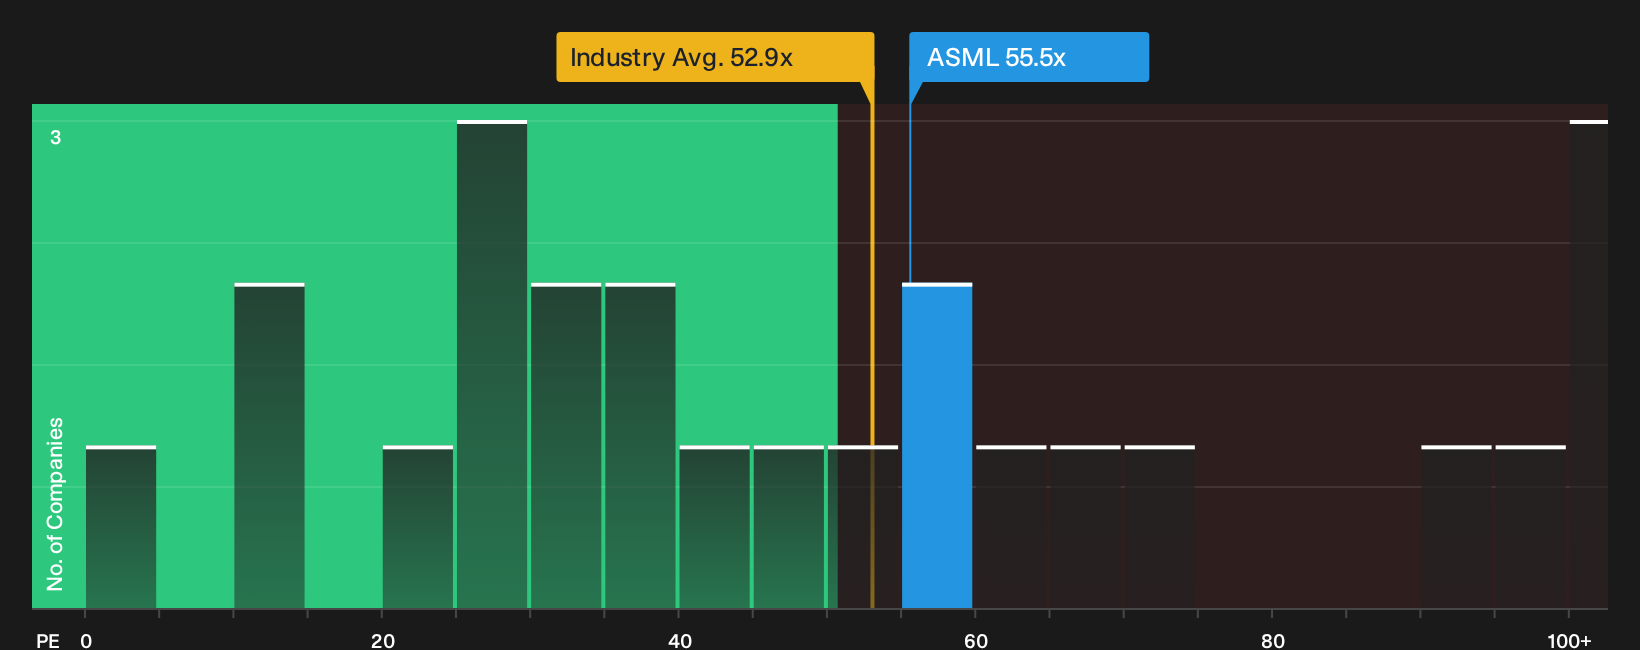
A different lens paints ASML Holding in a less stretched light. The stock trades on a P/E of 55.5x, compared with a fair ratio of 61.6x, even though that multiple is higher than both peer and European semiconductor averages of 51.5x and 52.9x. That mix of premium and slight discount raises a simple question: Is this pricing compensating you enough for the risk that sentiment swings back toward those lower benchmarks?
For a closer look at how these valuation gaps line up with peers in practical terms, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around ASML Holding is mixed, which creates room for disagreement and opportunity. Act before the next narrative shift and weigh both sides of the story by checking the 2 key rewards and 1 important warning sign.
Looking for more ASML-inspired investment ideas?
If you only focus on ASML Holding, you could miss other compelling setups. Use the Simply Wall Street Screener to surface fresh ideas before everyone else.
- Spot potential bargains early by scanning a curated 198 high quality undervalued stocks that filters for quality first, then price.
- Strengthen your downside protection by reviewing a 223 resilient stocks with low risk scores that focuses on businesses with more resilient profiles.
- Hunt for future market leaders by searching a 618 high quality undiscovered gems built around strong fundamentals rather than hype.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com