
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Third Quarter Earnings Change Lennar (LEN) Narrative
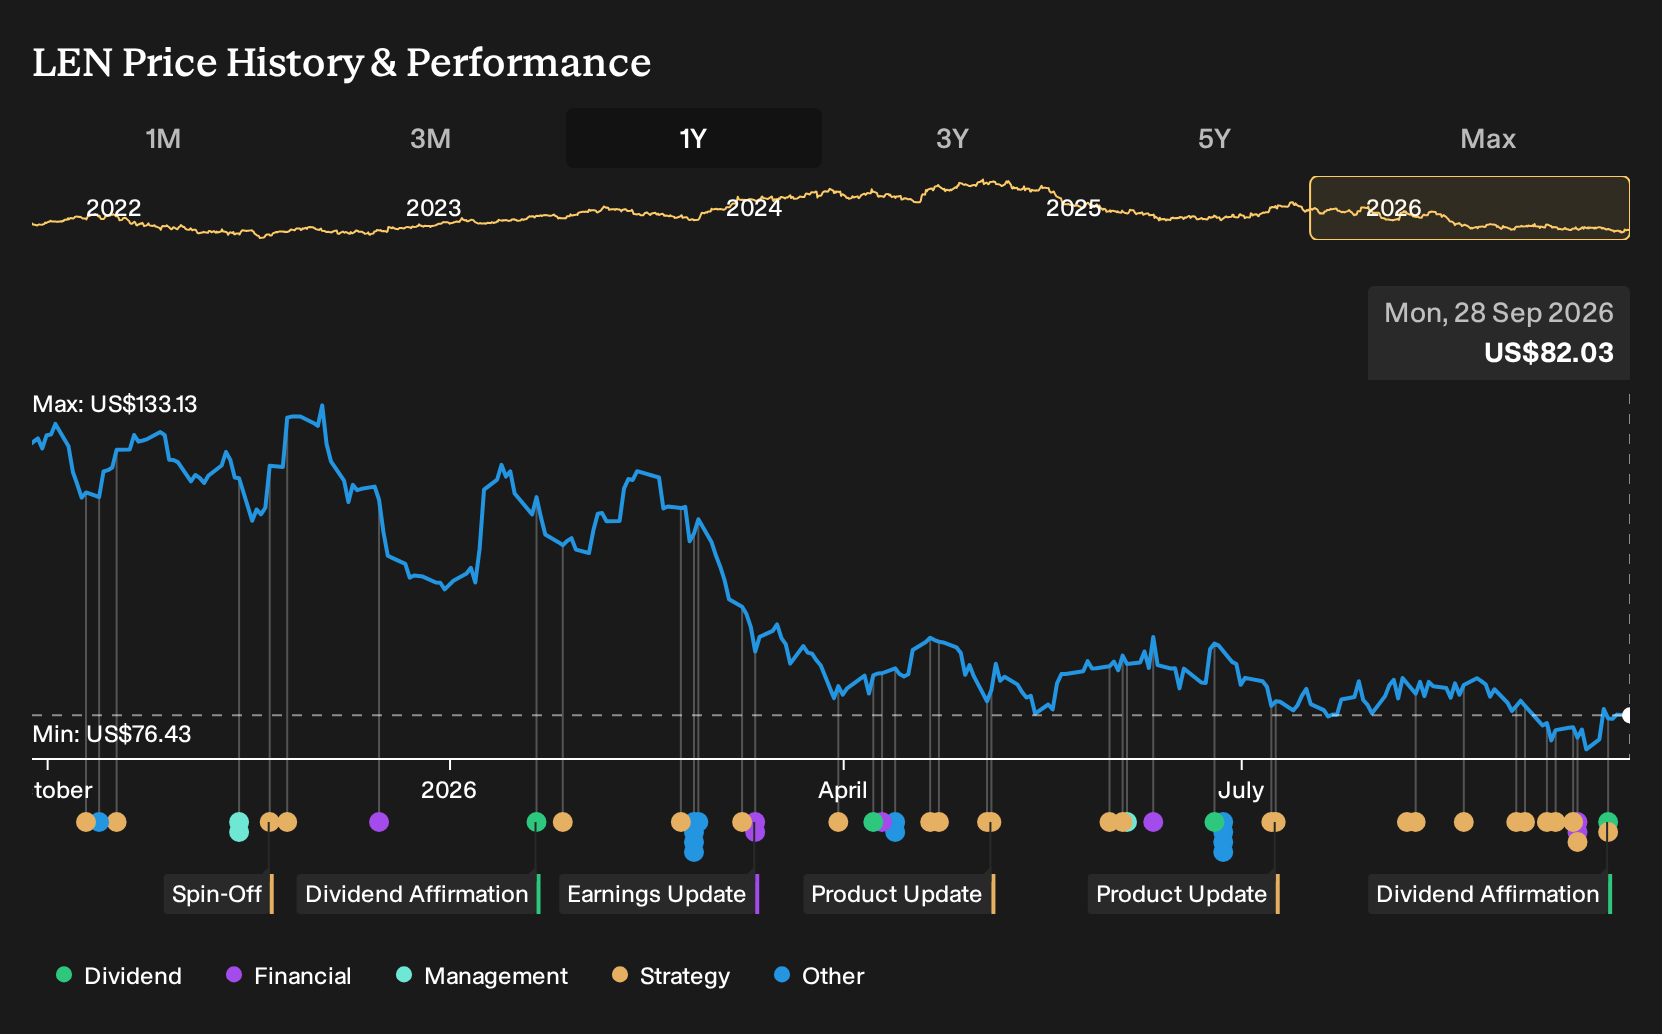
- Lennar reported third quarter 2026 results with revenue of US$8.05b and net income of US$283.88m, updated fourth quarter order and delivery guidance, and affirmed a US$0.50 quarterly dividend payable on October 22, 2026.
- Alongside softer earnings, Lennar continued returning capital through buybacks, repurchasing 3,000,000 shares between June and August 2026 and completing a multi year program totaling 52,005,201 shares.
- This article examines how Lennar's softer third quarter earnings and updated order guidance influence the broader investment narrative around the business.
Scan how Lennar's softer earnings and firm dividend compare with peers by jumping into our curated list of 32 high quality undervalued stocks for a broader view of potential opportunities.
Lennar Investment Narrative Recap
Lennar appeals to shareholders who buy into a simple idea. The builder focuses on keeping homes affordable, runs an asset light model, and aims for steady volume even when demand cools. Softer third quarter earnings and thinner margins highlight how dependent that approach is on incentives, mortgage availability, and build costs in the near term.
The key short term swing factor is whether Lennar converts its fourth quarter order outlook of 19,500 to 20,500 into profitable deliveries while keeping incentives contained. The largest risk is that higher rates and pressured buyers could lead to deeper discounting, which would prolong the impact on margins already visible in the 4% net profit level.
The dividend affirmation at US$0.50 per share for October 22, 2026, sits at the center of this story. Management is signaling a willingness to continue returning cash even while earnings and net income for the quarter and nine month period are below last year’s levels. That matters for investors who focus on total return rather than only headline growth.
As a potential catalyst, the payout can help keep income focused investors engaged while Lennar works through margin pressure and executes on its asset light, just in time build approach. The risk is that persistent weakness in profitability or a prolonged need for sales incentives could eventually test how sustainable dividend growth and buybacks are relative to the firm’s operating cash generation.
Lennar Earnings Outlook And Analyst Assumptions
Lennar's narrative projects US$40.8b revenue and US$2.7b earnings by 2029. This implies 8.5% yearly revenue growth and an earnings increase of about US$1.4b from the US$1.3b earnings level today.
Uncover why Lennar's fair value indicates Lennar is approximately in line with its current price.
Exploring Other Perspectives
Some of the lowest Lennar analysts frame the real swing factor differently. They focus on prolonged margin pressure from incentives, not community openings or the affirmed US$0.50 dividend. Before this earnings update, that group was only penciling in about US$34.3b of revenue and roughly US$1.2b of earnings by 2029. That is a far more cautious story than the consensus US$40.8b and US$2.7b view. Use that gap as a prompt to stress test your own expectations and explore several possible paths for Lennar as the latest results and new projects filter into analyst models.
Explore 3 other Lennar fair value estimates, including one that suggests there could be as much as 20% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and instincts.
- A great starting point for your Lennar research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lennar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lennar's overall financial health at a glance.
Looking For More Investment Ideas Beyond Lennar?
If Lennar's story has you thinking about portfolio balance and where the next opportunity might come from, it can help to scan a wider set of companies using clear, rules based filters.
- If you want potential growth with a smaller price tag, review a curated set of higher risk, higher potential stocks through 7 elite penny stocks with strong financials.
- For investors who care most about quality at a reasonable price, narrow the field to companies with stronger fundamentals using our broader 32 high quality undervalued stocks.
- If stability and staying power matter more than rapid gains, focus on resilient balance sheets and solid fundamentals via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com