
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To QBE Insurance Group (ASX:QBE) Australia Pacific CEO Appointment
- QBE Insurance Group has appointed Jonathan Groves as Chief Executive Officer, Australia Pacific, effective 1 November 2026, with a seat on the Group Executive Committee and a direct reporting line to Group CEO Andrew Horton, subject to regulatory approvals.
- Groves brings over 30 years of insurance experience and deep internal knowledge from roles including Chief Risk Officer and CEO of QBE Pacific. This background may influence how QBE balances its growth ambitions with underwriting discipline across the Australia Pacific portfolio.
- We will now look at how QBE Insurance Group's investment narrative could be influenced by Groves' expanded leadership remit in Australia Pacific.
QBE Insurance Group Investment Narrative Recap
To hold QBE Insurance Group, you need to be comfortable with a global insurer that leans heavily on underwriting discipline, reinsurance and digital projects to manage claims volatility and expenses. The key short term swing factor remains pricing versus inflation. The Groves appointment does not materially change that near term, but it does reinforce continuity in how the Australia Pacific arm is run.
The biggest current risk still sits in soft premium trends and large loss volatility, where aviation, property and catastrophe events can move the combined ratio quickly. Groves’ risk background may help how the regional portfolio is steered, yet the underlying exposure to weather, competition and claims inflation remains the core issue to watch.
In the absence of other fresh announcements around capital or underwriting, the most relevant context for this leadership move is QBE Insurance Group’s existing focus on digital transformation and cost efficiency. Management has already flagged that technology investment is slowing the pace of expense ratio improvement. That matters for you because Australia Pacific is a big operational hub.
Groves has been close to those programs as CEO and Managing Director of QBE Pacific, which links this news directly to execution on systems, risk and pricing tools. If those projects deliver smoother claims handling and sharper underwriting across Australia Pacific, they could support the catalysts analysts highlight around earnings quality and consistency, while the familiar leadership profile may help limit disruption as those plans continue.
QBE Insurance Group's current narrative focuses on revenue growth of 4.8% a year and current earnings of $2.1b, with consensus forecasts also pointing to $2.1b of profit in 2029. This implies no earnings change between current earnings and the 2029 forecast, alongside an analyst view that revenues would reach $21.6b by that year.
Uncover why QBE Insurance Group's fair value indicates a 3% potential upside to its current price that could close sooner than many investors expect.
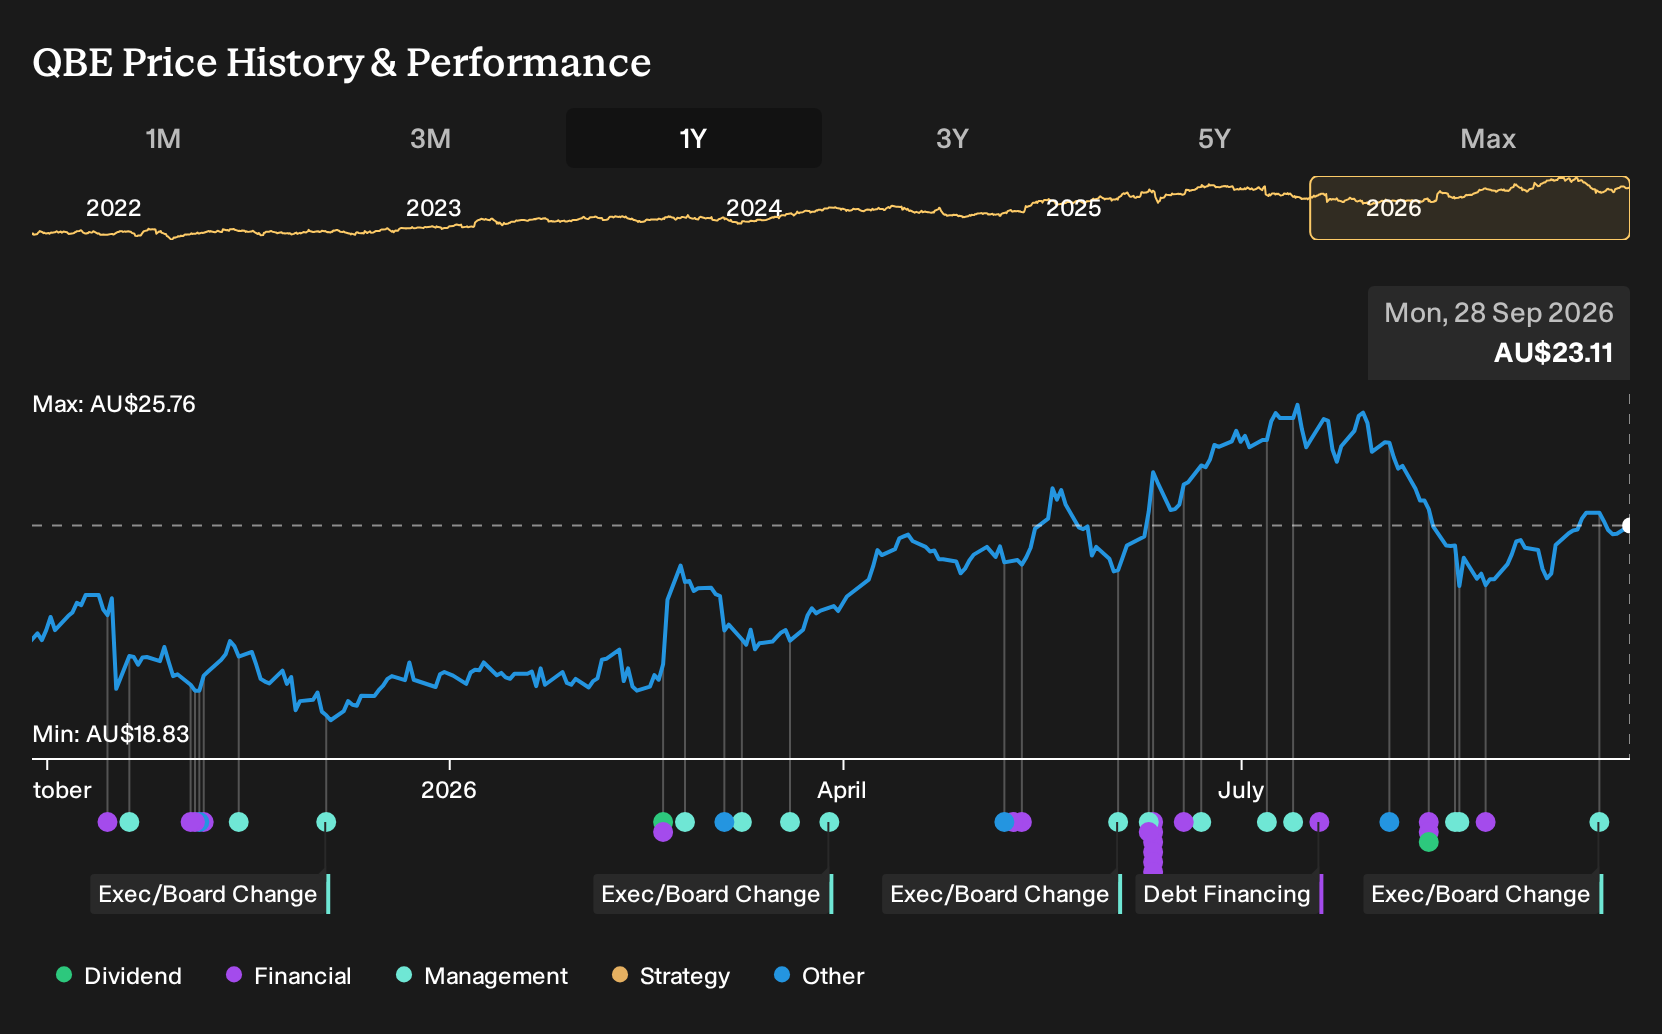
Exploring Other Perspectives
You can look at Jonathan Groves' appointment through a different lens. The most pessimistic analysts already expected QBE Insurance Group's earnings to fall from about $2.2b to $1.7b by 2029, even with revenue near $22.1b. They worry about catastrophe risk and reinsurance complexity. This leadership shift could eventually prompt those views to adjust.
Explore 5 other QBE Insurance Group fair value estimates, including one that suggests as much as 23% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your QBE Insurance Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QBE Insurance Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QBE Insurance Group's overall financial health at a glance.
Looking for more investment ideas beyond QBE Insurance Group?
If this QBE Insurance Group update has sharpened your thinking about risk, capital and leadership, it can be useful to compare it with other businesses facing different trade offs. The Simply Wall St Screener lets you filter by balance sheet strength, earnings profile and income potential so you can build a watchlist that fits how you like to invest.
- For investors who want potential upside with tight risk controls, start with a 7 resilient stocks with low risk scores that prioritises resilient business models and lower volatility profiles.
- If reliable income is a priority, scan a 3 dividend fortresses focused on higher yielding companies where shareholder payouts play a central role in the investment case.
- To widen the opportunity set beyond well known stocks, consider a 16 high quality undiscovered gems built around companies with solid fundamentals that are less crowded by attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com