
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Home Depot (HD) Following Its Pro Expansion Story Does The Stock Still Look Undervalued
Mortgage rates near 7.5% have hit homebuilding stocks and renovation activity, and Home Depot (HD) has been pulled into that downdraft as shoppers shift toward smaller, lower-ticket projects.
Recent trading reflects that pressure. Home Depot’s share price is down 12.21% over the past 30 days and 16.17% year to date, contributing to a 1 year total shareholder return decline of 26.72% as enthusiasm has cooled compared with the modestly positive 3 year and 5 year total shareholder returns.
Scan how other housing-sensitive businesses are reacting to the same mortgage shock by reviewing our curated list of 39 power grid technology and infrastructure stocks that could be next in line for a sentiment reset.
Home Depot now trades well below its recent levels after a long run as a market favorite. Has most of the premium already bled out, or is the real upside still ahead?
Most Popular Narrative: 25% Undervalued
Relative to the latest close at $289.89, the most followed narrative on Home Depot argues for a fair value near $385, which points to a sizeable valuation gap in the eyes of that analysis.
Home Depot is evolving from a traditional big-box home improvement retailer into a comprehensive supplier ecosystem for professional contractors (“Pros”), while continuing to serve DIY customers through stores, digital tools, and faster fulfillment. Recent acquisitions (including SRS Distribution and GMS) expand its reach into specialty distribution for roofing, drywall, HVAC, and other complex project categories, enlarging the addressable market toward roughly $1.2 trillion and the Pro segment opportunity near $700 billion.
See why 4 investors see Home Depot as 25% undervalued.
Result: Fair Value of $385 (UNDERVALUED)
Still, the Home Depot narrative can break if housing turnover stays weak for longer, or if recent acquisitions drag on margins instead of scaling efficiently.
Find out about the key risks to this Home Depot narrative.
Another View: Home Depot Through A Cash Flow Lens
The narrative crowd sees Home Depot as roughly 25% undervalued at a fair value of $385. Our DCF model tells a cooler story. On that framework, the shares at $289.89 sit above an estimated future cash flow value of $276.31, which points to mild overvaluation instead of a discount.
That gap reflects different beliefs about how much cash Home Depot can generate and how those dollars should be discounted back to today. It leaves a practical question for investors sizing positions: Is the market already paying up for cash flows that some models treat as fairly rich, or is the narrative view closer to how this stock will ultimately be priced?
Look into how the SWS DCF model arrives at its fair value.
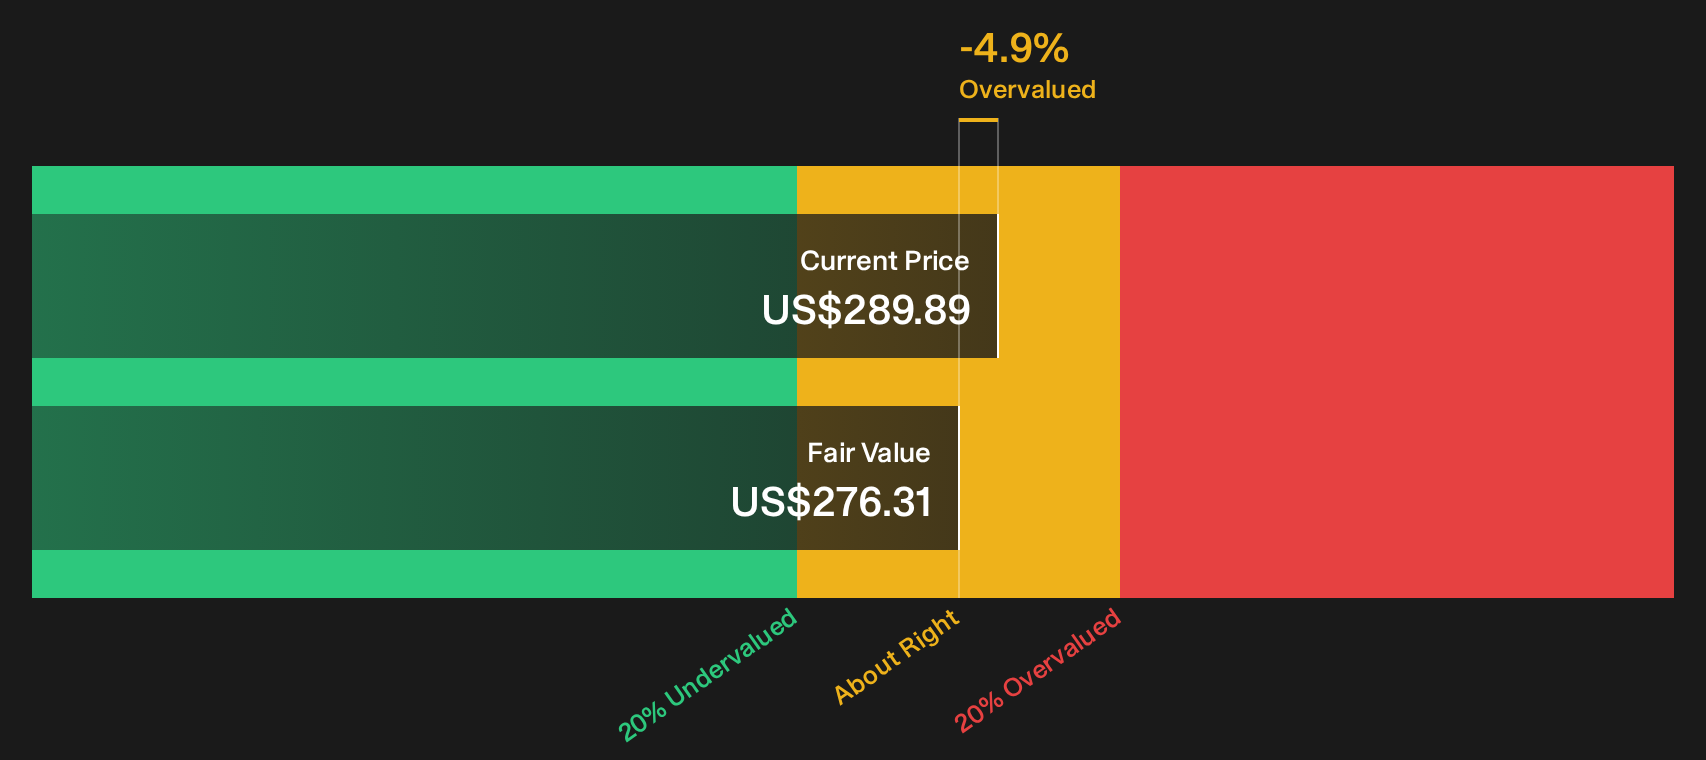
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Home Depot for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
There is a sense that opinions on Home Depot are moving in different directions. Consider acting before the next move and weigh the trade offs yourself with 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Home Depot?
If the Home Depot story has you thinking about portfolio upgrades, now is the time to widen your search before the next wave of opportunities gets crowded.
- Target resilient cash generators by scanning a 32 high quality undervalued stocks that combines quality fundamentals with pricing that still signals potential mispricing.
- Lock in income potential with a curated 6 dividend fortresses that can help you focus on higher yield opportunities with robust payout profiles.
- Protect your downside by zeroing in on a 30 resilient stocks with low risk scores that highlights companies with sturdier financial health and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com