
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did EBITDA Miss Just Shift PENN Entertainment (PENN) Stock Investment Narrative?
- PENN Entertainment recently reported quarterly revenue of US$1.86b, up 5.2% year on year and broadly matching expectations, while earnings per share came in ahead of analyst estimates.
- The key concern was a substantial EBITDA shortfall, which pointed to ongoing pressure on underlying profitability despite headline revenue growth and an earnings beat.
- We will now see how PENN Entertainment's investment narrative could be affected by this revenue growth paired with a sharp EBITDA miss.
PENN Entertainment Investment Narrative Recap
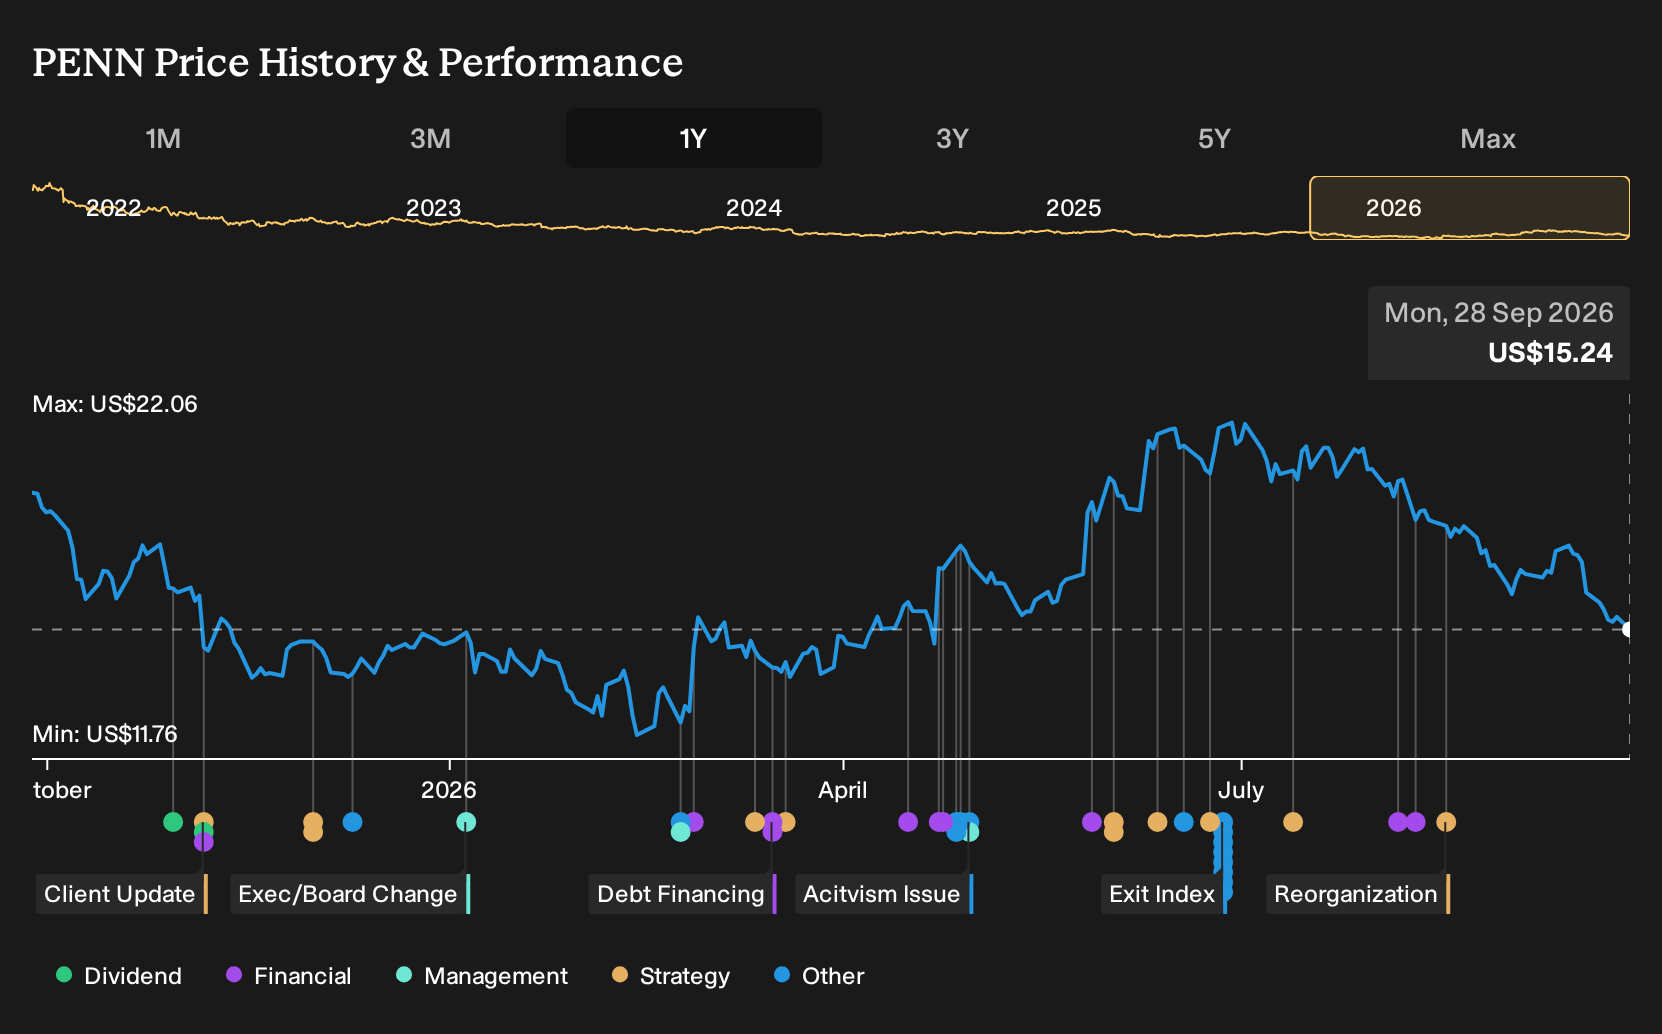
To stay invested in PENN Entertainment, you need to believe the mix of regional casinos and the Interactive arm can eventually translate solid revenue into healthier cash profits. The latest quarter complicates that story. Revenue landed where the market expected, but the EBITDA shortfall and the stock’s 20.3% drop to US$15.64 put near term execution under the microscope.
Right now, the key short term catalyst is whether management can tighten costs in both retail and digital so that future quarters do not repeat this gap between revenue and EBITDA. The biggest risk is that loss making Interactive operations, higher gaming taxes, and leverage keep absorbing cash even as top line trends hold steady.
With no fresh corporate announcements tied directly to this earnings release, the most relevant context is PENN Entertainment’s ongoing push around ESPN BET and omnichannel integration that was already in focus before this quarter. The latest results stress test that plan. Investors now have to watch whether user growth and engagement can translate into operating leverage rather than further EBITDA strain.
This is where execution risk meets the current share price move. A US$1.86b revenue base, an Interactive unit that is still loss making, and higher state tax burdens leave little room for sloppy spending or delays on tech and product improvements. Any future update on ESPN BET performance, cross sell from casinos, or capital allocation will likely be read directly against this recent EBITDA miss.
PENN Entertainment’s narrative projects US$8.3b revenue and US$466.8m earnings by 2029, based on analysts’ models. That profile rests on 4.9% yearly revenue growth and an earnings swing of about US$1.37b, from earnings today of a US$906.7m loss to the forecast US$466.8m profit.
Uncover why PENN Entertainment's fair value indicates a 60% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest PENN Entertainment forecasts lean hard into regulatory risk. Those analysts were only pencilling in about 1.9% annual revenue growth to roughly US$7.6b and earnings of around US$336.3m by 2029 before this EBITDA miss. That is a much harsher story, and it shows how far opinions can spread. Use this shock as a prompt to compare several viewpoints before deciding what feels reasonable to you.
Explore 4 other PENN Entertainment fair value estimates, including one that suggests it could be worth just $24.39!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PENN Entertainment research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for PENN Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PENN Entertainment's overall financial health at a glance.
Looking For More Investment Ideas Beyond PENN Entertainment?
If PENN Entertainment's latest results have sharpened your focus on risk, reward, and execution, it can help to compare this story with other stocks that share the traits you care about most. Use that same lens across a broader watchlist so you are not relying on a single turnaround to carry your portfolio.
- For investors who want upside without ignoring quality, start with a curated set of 16 high quality undiscovered gems that pair solid fundamentals with less crowded ownership.
- If capital preservation matters just as much as return potential, narrow your search to a 30 resilient stocks with low risk scores that filters for resilient balance sheets and milder volatility profiles.
- When you care most about financial strength supporting long term compounding, focus on a list of solid balance sheet and fundamentals (25 results) that screens for robust cash positions and manageable debt loads.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com