
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Trip.com Group Stock After A Return To Net Loss
- Trip.com Group reported Q2 2026 revenue of CNY 15,663 million and a net loss of CNY 2,458 million, with basic and diluted loss per share of CNY 3.89.
- Across the first half of 2026, Trip.com Group recorded CNY 31,871 million in revenue but only CNY 41 million in net income, indicating significant cost or margin pressure despite higher sales.
- This raises questions about how Trip.com Group's investment narrative holds up when rising revenue coincides with a sharp swing to a quarterly loss.
Compare Trip.com Group's sharp earnings swing with other travel and consumer stocks by scanning our hand picked list of 32 high quality undervalued stocks, which may offer a stronger balance between revenue and profitability.
Trip.com Group Investment Narrative Recap
To stay invested in Trip.com Group, you need to believe its scale in Asian travel and heavy digital focus can turn higher bookings into consistently healthy earnings again. The latest quarter complicates that story. Revenue reached CNY 15,663 million, yet the firm reported a net loss of CNY 2,458 million, which puts the near term spotlight squarely on cost control.
The key short term catalyst is whether management can stabilise profitability while keeping share in a crowded online travel market. The biggest risk is that marketing, promotions and possibly softer pricing keep eating into margins, so higher sales do not translate into solid net income. This earnings print directly highlights that pressure.
The most relevant data point for this earnings release is the six month picture. Trip.com Group generated CNY 31,871 million in revenue for the first half of 2026, but only CNY 41 million in net income. That tiny profit pool next to a large top line highlights where the current debate sits. It is not about demand. It is about what falls through to the bottom line.
That context matters when you weigh the existing catalysts, such as growing digital bookings and exposure to Asia Pacific travel. These drivers still rely on the platform being able to earn a reasonable return after heavy marketing, technology spend and any pricing pressure from airlines, hotels and rival apps. Until the gap between revenue and earnings closes meaningfully, the operational risk side of the Trip.com Group story remains central for investors.
Trip.com Group's current analyst narrative points to forecast revenue of CNY 84.7b and projected earnings of CNY 17.5b by 2029, based on assumed yearly top line growth of 9.4% and an earnings decline of CNY 14.0b from estimated earnings today of CNY 31.5b.
Uncover why Trip.com Group's fair value indicates a 50% potential upside to its current price that may not last much longer.
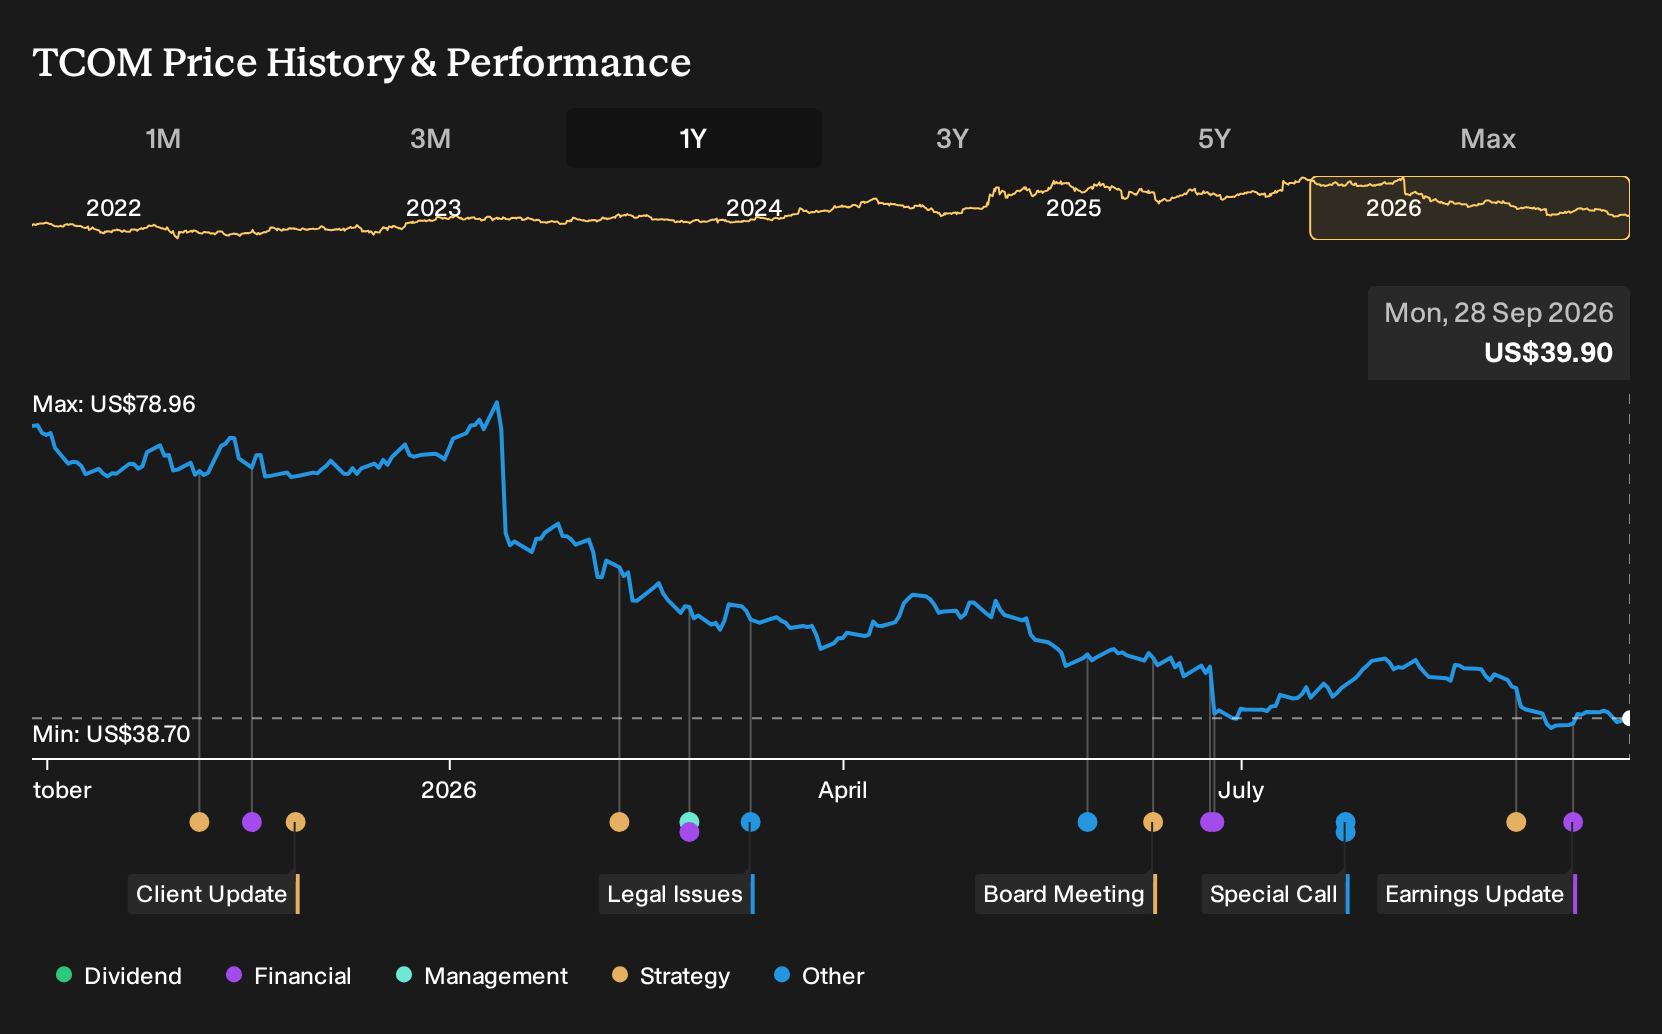
Exploring Other Perspectives
Some of the most optimistic analysts lean hard on Trip.com Group’s AI build out as a potential earnings driver. Before this earnings release, the bullish side was sketching out revenue of about CNY 91.8b and earnings near CNY 18.8b by 2029. That is a very different story. Treat this quarter as a prompt to compare those views for yourself.
Explore 4 other Trip.com Group fair value estimates, including one that suggests potential upside of up to 267% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Trip.com Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Trip.com Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trip.com Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Trip.com Group?
Trip.com Group might be the focus today, but your watchlist probably needs more than one potential opportunity. Use the Simply Wall St Screener to line up other businesses that better fit your risk tolerance, income needs, or preference for stronger balance sheets.
- If capital preservation matters most to you, start with companies that our models flag as relatively steady through 30 resilient stocks with low risk scores.
- If you care more about resilient finances than headline stories, filter for businesses with healthier balance sheets using our list of solid balance sheet and fundamentals (25 results).
- If you are hunting for future leaders that are not yet crowded trades, widen your research with our curated pool of 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com