
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
IDC: Global humanoid robot shipments in the first half of the year were close to 25,000 units, up 432.1% year-on-year
The Zhitong Finance App learned that the latest global humanoid robot tracking report released by the International Data Corporation (IDC) shows that in the first half of 2026, global humanoid robot shipments were close to 25,000 units, an increase of 432.1% over the previous year, and industrial development further moved from technology verification to commercial application exploration stage. Application scenarios continue to expand, accelerating expansion to industrial manufacturing, retail, transportation and logistics, leisure travel, and household consumption; at the same time, industry competition is also gradually shifting from intrinsic performance to integrated intelligent capabilities. IDC expects global shipments of humanoid robots to exceed 750,000 units in 2030, and the market will enter a stage of accelerated development of large-scale applications.
The global humanoid robot market continues to explode and is expected to exceed 750,000 units in 2030
Since 2026, the global humanoid robot market has continued its rapid growth trend, and industrial development has further moved from technical verification to commercial application exploration. According to IDC data, in the first half of 2026, global humanoid robot shipments were nearly 25,000 units, up 432.1% year on year; the market size exceeded 740 million US dollars, up 322.7% year on year.
At the same time as the market is growing rapidly, both the supply and demand sides of the humanoid robot industry are also undergoing positive changes: on the one hand, exploration of industrial and logistics applications continues to accelerate, leading manufacturers continue to expand production capacity; on the other hand, small humanoid robots for individual consumers have begun to appear in the Chinese market, and the home and individual markets are gradually becoming new potential growth spaces. In addition, large models of embedded intelligence are rapidly iterated, and the robot's ability to understand, make decisions, and perform tasks in complex environments continues to improve, providing technical support for humanoid robots to expand more application scenarios.
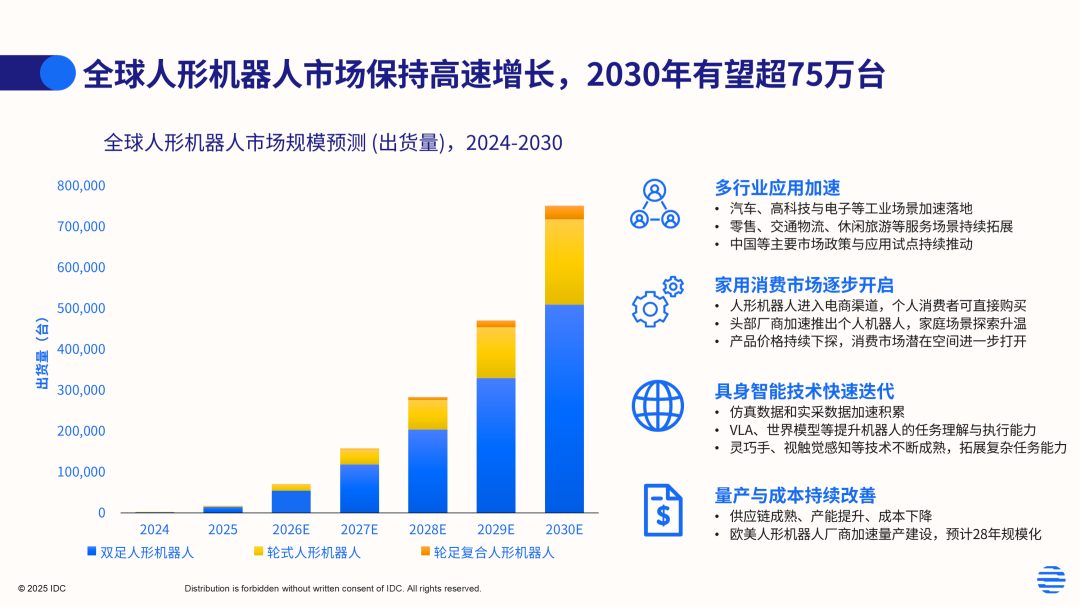
Based on the continuous increase in supply capacity, the acceleration of application scenarios, and the gradual opening up of the consumer market, IDC raised its long-term global humanoid robot market forecast. It is estimated that global humanoid robot shipments will exceed 750,000 units in 2030, an increase of about 50% compared to the previous forecast. IDC believes that in the future, the global humanoid robot market will gradually form a growth pattern driven by diversified industrial applications, commercial services and consumer markets, and the market will also move further from “technologically feasible” to “large-scale application and commercial value verification.”
China has become an important engine for the growth of the global humanoid robot market
According to IDC data, in the first half of 2026, China's humanoid robot market continued to grow rapidly, with shipments exceeding 19,000 units, up 426.3% year on year, accounting for about 77.9% of the global market, becoming an important driving force for the growth of the global humanoid robot market.
The rapid development of the Chinese market has, on the one hand, benefited from continued policy promotion. Since 2026, local governments, industrial parks and state-owned enterprises have continued to increase their support for the humanoid robot industry, and accelerate humanoid robots from technology research and development to practical application by building innovative platforms, publishing application scenarios, and promoting procurement and deployment.
On the other hand, China has a relatively complete humanoid robot industry chain and an active manufacturer ecosystem. Machine manufacturers, parts companies, AI model companies and system integrators accelerate collaboration to promote continuous iteration of robot core components, machine manufacturing and intelligent capabilities, and continuous improvement in product costs and mass production efficiency.
At the same time, Chinese manufacturers are becoming an important force in the growth of the global humanoid robot market. In the first half of 2026, Chinese manufacturers accounted for more than 95% of the global market's shipments. Many Chinese manufacturers entered the leading group of global shipments, and leading manufacturers maintained rapid progress in product iteration, mass production delivery, and application implementation.
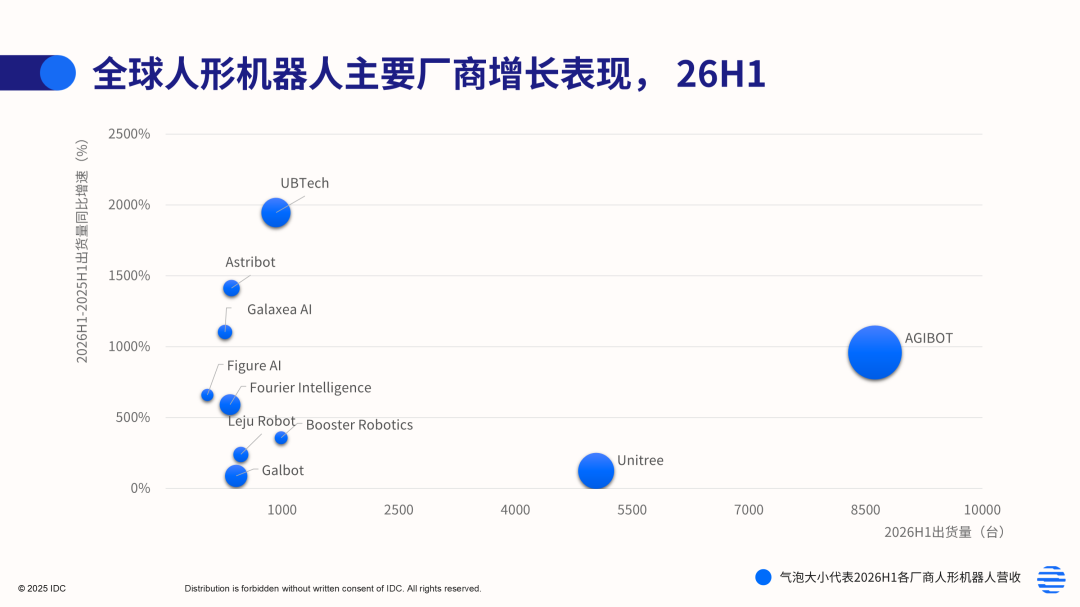
Judging from the market development path, China is forming a market development model co-driven by “policy promotion, industrial collaboration and application traction”. As applications in the automotive, 3C, logistics, energy and other industries continue to advance, China is expected to continue to maintain an important growth position in the global humanoid robot market and become a key market for large-scale development of the global industry.
Application scenarios continue to expand, and humanoid robots accelerate their entry into multiple industries and household consumer markets
As the maturity of humanoid robot products increases and application exploration continues to deepen, the market application boundaries are constantly expanding. In the first half of 2026, the total share of shipments for application scenarios such as scientific research and education, performance display, and government (digital acquisition center) dropped from 83.8% in 2025 to 69%, and the application structure was further diversified. Among them, the scientific research and education scene continues to sink, gradually extending from scientific research in colleges and universities to artificial intelligence education in vocational colleges, primary and secondary schools; the share of performance display applications has declined; and the construction of government digital collection centers is still an important shipping direction at present.
At the same time, humanoid robots have begun to accelerate their expansion into more industries such as industrial manufacturing (automobile manufacturing, high-tech and electronics, other industrial manufacturing, aerospace, etc.), retail, transportation and logistics, leisure and tourism, etc., and manufacturers and industry users continue to advance scenario verification and commercial application exploration.
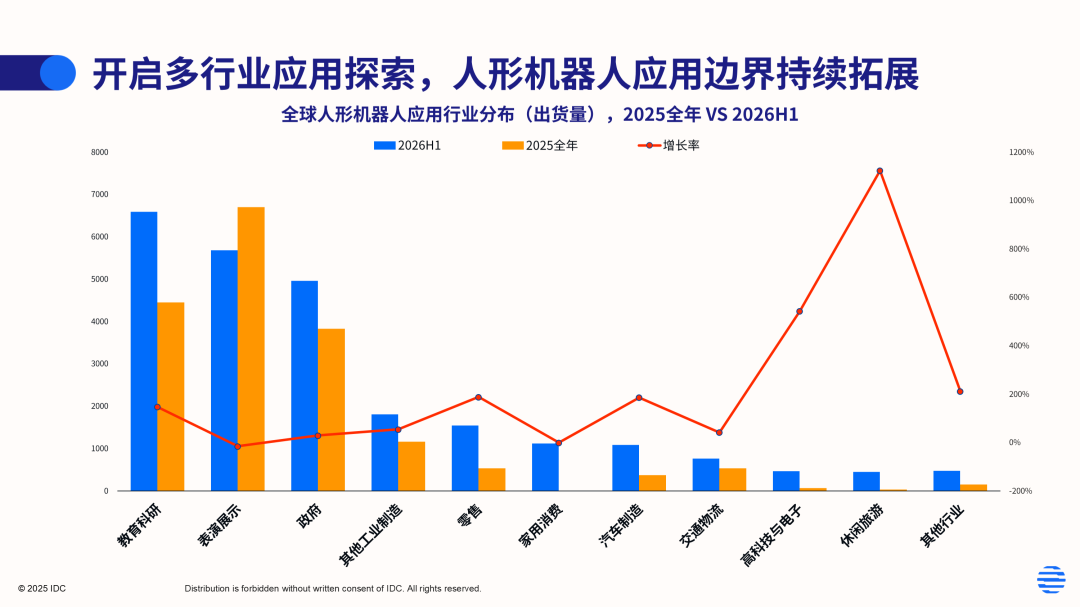
Industrial manufacturing is an important direction in the current exploration of humanoid robot applications. Industries such as automobile manufacturing, high-tech and electronics, and other industrial manufacturing have clear intelligent requirements and semi-structured operating environments, providing many opportunities for humanoid robots to enter real production processes. Manufacturers such as Zhiyuan Robotics AGIBOT, Preferably Ubtech, and Galaxy GM Galbot focus on the industrial sector.
At the same time, service industries such as retail, transportation and logistics, leisure and tourism are beginning to explore more applications, and humanoid robots are further expanding into service-oriented work scenarios.
It is worth noting that the household consumer market is also beginning to see actual shipments. The manufacturer launched a small-sized, low-cost humanoid robot and reached individual consumers through e-commerce and other channels, providing functions such as child education and personal companionship. With the further launch of personal companion robots in the second half of 2026, consumer-grade products are expected to drive the expansion of the user base of humanoid robots from enterprises and institutions to individual consumers.
Overall, humanoid robots are gradually entering more industries and terminal consumption scenarios from technical verification in a few industries. The continuous expansion of the scope of application is becoming an important factor driving the growth of the market size, and has further broadened the market boundaries of humanoid robots.
Embodied intelligence technology evolves at an accelerated pace, and vendor competition extends from ontology to intelligent capabilities
Humanoid robots are entering a critical stage of transformation from “hardware capability competition” to “integrated ability competition with embodied intelligence.” With the rapid development of large models, world models, visual language action models (VLA), and closed-loop technology for robot data, the focus of industry competition is gradually shifting from robot structural design, motion performance, and hardware parameters to the comprehensive ability of robots to understand the physical world, task planning, operation execution, and continuous learning.
Judging from the development of technology, the physical intelligence capabilities of humanoid robots are not a single model ability, but are composed of multiple dimensions, mainly including:
Cognitive Intelligence (Cognitive Intelligence): the ability to sense, understand, reason and plan tasks in the physical world;
Motion Intelligence (Motion Intelligence): motion generation, full body coordination, dynamic movement, and ability to adapt to complex environments;
Operational Intelligence (Operational Intelligence): Closed loop of perception and action, dexterous operation and ability to use tools;
Interaction Intelligence (Interaction Intelligence): human-computer interaction, environmental interaction, and multi-agent coordination capabilities;
Data Intelligence (Data Intelligence): Real data collection, simulation data, data governance and continuous learning capabilities;
AI engineering capabilities (AI engineering): model deployment, software and hardware collaboration, and AI system engineering capabilities;
AI Ecosystem (AI Ecosystem): model, data, development tools, hardware and application partner ecosystem;
AI Deployment Maturity (AI Deployment Maturity): From laboratory verification to real-world scenario deployment, continuous operation, and large-scale application capabilities.
As technologies such as VLA and world models continue to evolve, the integration of these capabilities is accelerating. Manufacturers are also beginning to break through a single technology and gradually build a complete technical system covering models, data, engineering, and applications, and promote the evolution of robots from executing pre-set procedures to understanding the environment, planning independently, and completing complex tasks.
Currently, different manufacturers are showing differentiated development in terms of embedded intelligent technology routes and capacity building accumulation. Some manufacturers pay more attention to basic models and cognitive capabilities, some strengthen motion control intelligence, and others continue to invest in closed data loops, AI engineering, and actual deployment. However, as the technology system gradually matures, it will be difficult for single-dimensional capability advantages to form long-term competitive barriers, and manufacturers will need to gradually supplement multi-dimensional capabilities such as cognition, movement, operation, interaction, data, AI engineering, ecology, and deployment. In the future, the competition among humanoid robot manufacturers will gradually move from the current differentiated technology route to full-scale competition with intelligent multi-dimensional comprehensive capabilities and large-scale implementation capabilities. ”
Li Junlan, research manager at IDC China, believes that overall, the global humanoid robot market continued its rapid growth trend in the first half of 2026, and the industry is moving further from technology verification to commercial application exploration. With policy promotion, industrial collaboration and application guidance, China has become an important engine for global market growth; application scenarios continue to expand from scientific research and education, performance and display to industrial manufacturing, retail, transportation and logistics, leisure travel, and household consumption; manufacturer competition is also gradually shifting from intrinsic performance to integrated intelligent capabilities. With the rapid iteration of large models of embodied intelligence, supply chain maturity, and continuous cost improvement, humanoid robots are expected to complete commercial value verification in more real scenarios and enter a stage of accelerated development of large-scale applications around 2030. In the future, whoever can break through the closed loop of “technology - data - engineering - scenario” faster will have a better chance of taking the initiative in the next stage of competition.