
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Boss (XTRA:BOSS) SDAX Addition
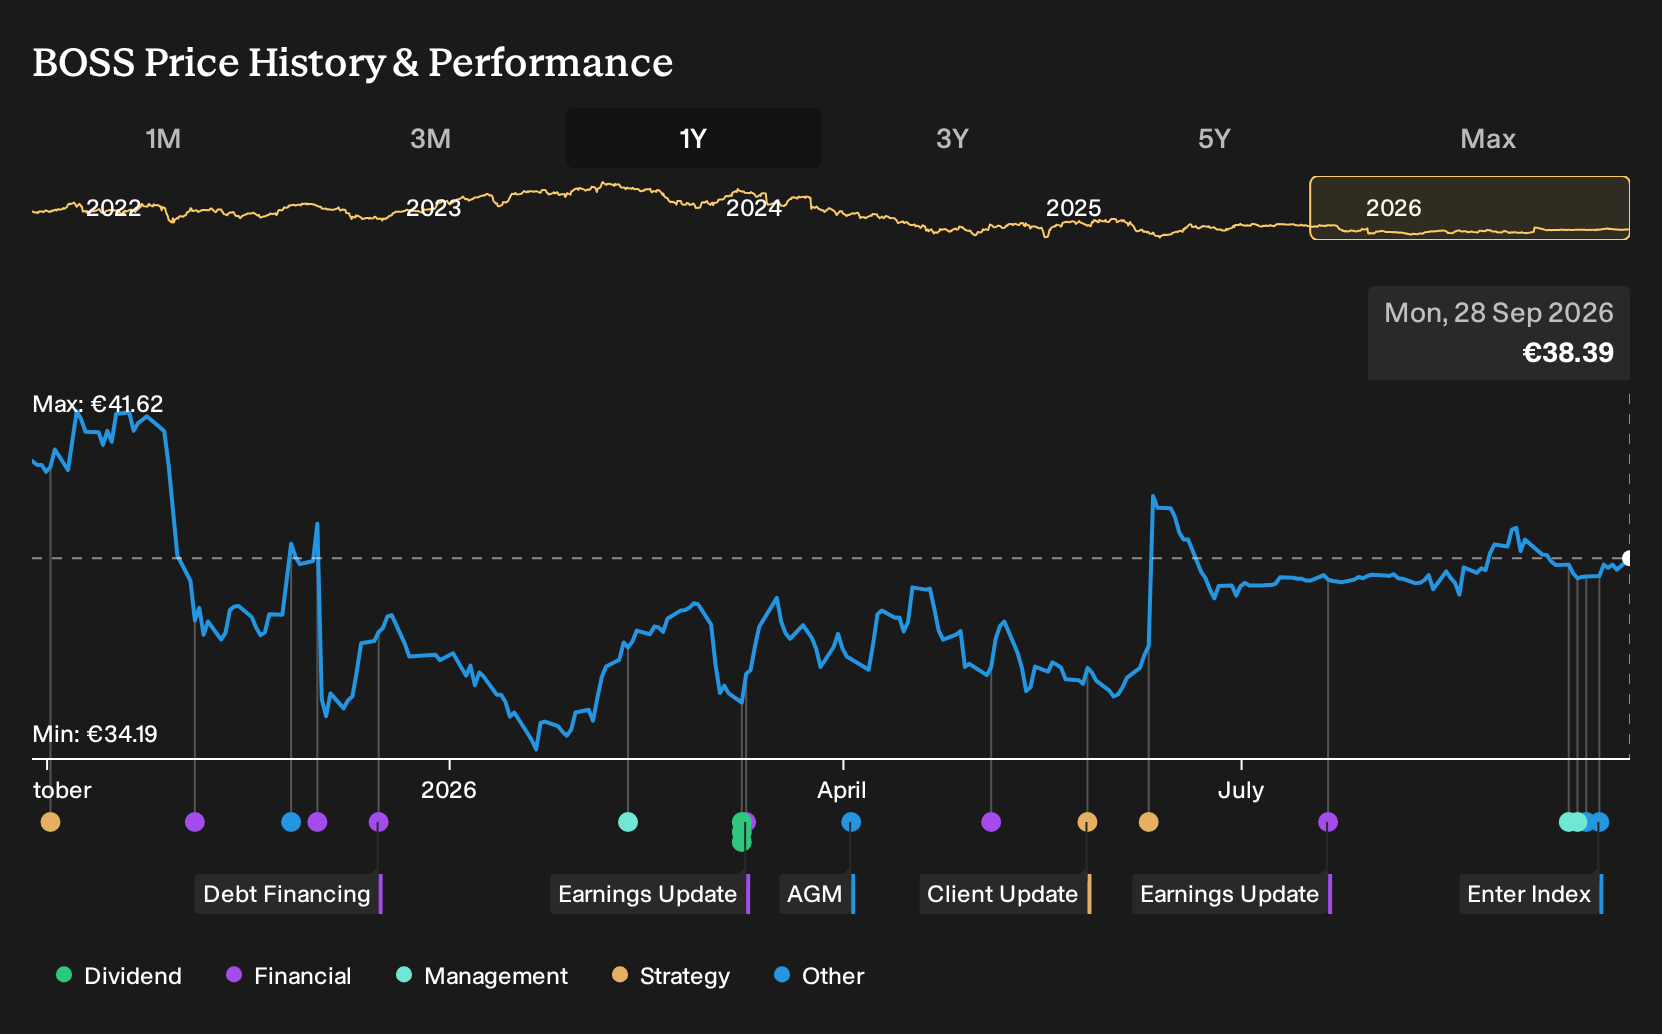
- Hugo Boss AG was added to the Germany SDAX (Total Return) Index on 21 September 2026 and recently appointed Michael Murray as Supervisory Board Chairman, following the resignation of Stephan Sturm.
- The SDAX inclusion can affect index fund demand, while the new chairman and expected Supervisory Board appointment may influence Hugo Boss governance priorities and execution focus.
- We will now look at how Hugo Boss's investment narrative could be affected by SDAX inclusion and a new Supervisory Board Chairman.
Scan how Hugo Boss compares with other potential movers in its space by checking the hand picked 196 high quality undervalued stocks that combine quality fundamentals with attractive pricing signals.
Hugo Boss Investment Narrative Recap
To own Hugo Boss you need to be comfortable with a fairly steady fashion business that is working to squeeze more value from digital, premium product lines and cost control while dealing with weaker demand in some regions and categories. The key short term swing factor is how well it can keep volumes and pricing balanced as consumer sentiment stays soft in the U.S. and China.
The biggest operational risk remains pressure on smaller brands and store traffic, which could make revenue growth patchy even if margins hold up. The recent SDAX move and governance changes do not materially alter that near term story. However, they may sharpen focus on execution and capital discipline.
The Supervisory Board changes sit closest to the real catalyst for Hugo Boss right now. That catalyst is execution on its premium, direct to consumer and cost efficiency agenda. Michael Murray stepping in as Supervisory Board Chairman, with Robert Palmer expected to join, concentrates more oversight experience around financial controls and long term capital allocation.
For you, the question is whether this refreshed board can support management in handling inventory, pricing and brand mix risks without diluting the focus on digital investments and emerging market expansion. Any shift in governance that tightens scrutiny on returns, cash generation and risk management could influence how confidently the market treats those existing catalysts.
Hugo Boss' narrative projects €4.2b revenue and €245.8 million earnings by 2029. This reflects relatively flat yearly revenue trends and an earnings increase of about €14.3 million from €231.5 million today.
Uncover why Hugo Boss' fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Another angle on Hugo Boss is digital execution rather than governance. The most bearish analysts already saw slow online progress as a key drag, with revenue assumptions near €4.1b and earnings around €206.8 million by 2029. Those views were set before the SDAX move and board reshuffle, so your own take may shift as fresh information lands.
Explore 3 other Hugo Boss fair value estimates, including one that suggests it could be worth just €36.50.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Hugo Boss research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Hugo Boss. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which helps you evaluate Hugo Boss' overall financial health at a glance.
Looking For More Investment Ideas Beyond Hugo Boss?
If Hugo Boss has sharpened your thinking about quality, pricing power and governance, it can be useful to compare it with a wider set of potential opportunities using the Simply Wall St Screener.
- For investors focused on resilient balance sheets and solid fundamentals, review the list of solid balance sheet and fundamentals (202 results) that meet tighter financial quality filters.
- If you prefer companies where valuation signals look more appealing, scan the 196 high quality undervalued stocks that combine stronger fundamentals with cheaper pricing.
- Income focused readers who want yield with support from the underlying business can check out the 165 dividend fortresses that target higher payouts backed by established operations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com