
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Australian Undervalued Stocks Trading At Least 21% Below Fair Value
Global trade has held up despite protectionism and shipping disruptions, which keeps cash flowing through many Australian businesses even as headlines focus on risk. When sentiment is cautious, companies that quietly generate solid cash but trade at a discount can be overlooked. This article highlights three Australian stocks that our cash flow valuation screen flags as priced below estimated fair value for investors hunting mispriced opportunities.
The three stocks below are just a starting sample from this cash flow valuation idea, and the full screen surfaced 3 more companies with equally compelling stories that are not covered here. To see the wider opportunity set, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and focus on the cash flow plays that best match your criteria.
Greatland Resources (ASX:GGP)
Greatland Resources is a gold and copper producer whose Havieron project in Western Australia anchors its cash flow story, with the Telfer Havieron segment generating about A$2.3b in revenue, and the stock valued at roughly A$7.1b by the market.
For this screener, Greatland Resources matters because its future cash generation is tightly linked to one flagship orebody. This gives investors a clear way to think about how production, costs, and the gold price might translate into long term cash flows.
"The primary driver of Greatland’s future is the gold price. As a single-asset developer moving toward production, it offers significant operational leverage to gold."
The real test will come if one unresolved pressure on future returns shifts sharply just as that leverage to results starts to bite.
If that pressure point matters to your thesis, read the full narrative for Greatland Resources to see how Greatland Resources might accelerate or stall as conditions shift.
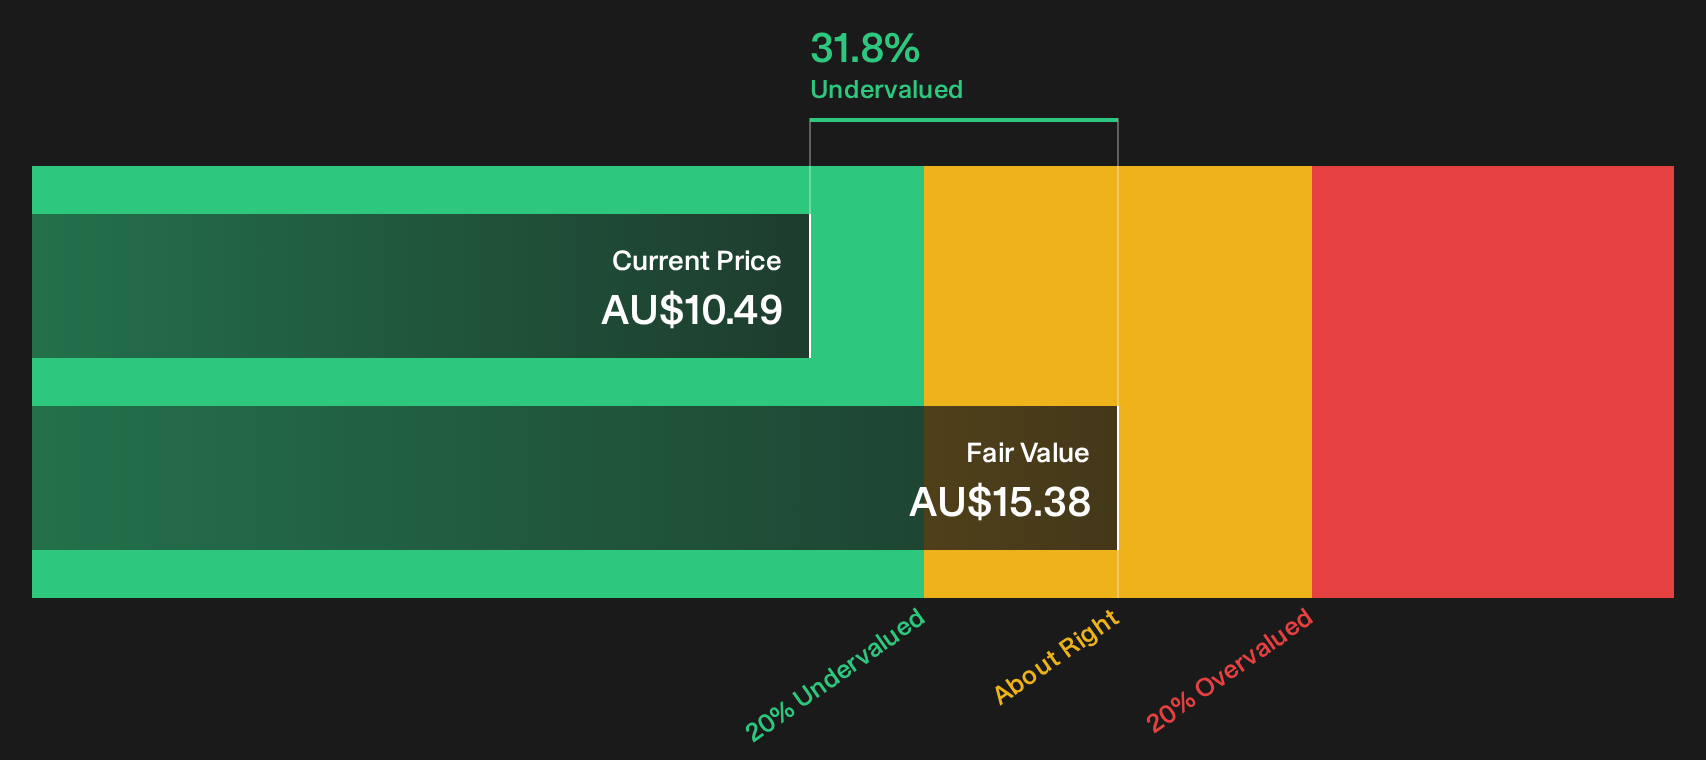
Woodside Energy Group (ASX:WDS)
Woodside Energy Group is a global hydrocarbon producer where large LNG projects such as Pluto, North West Shelf, Wheatstone and Scarborough underpin the cash flow story that lands it in an undervalued cash flow screen.
Woodside Energy Group generates most of its income from Australia at about $7.3b, with a further $4.6b from International operations and $1.9b through Marketing, and the stock is valued at roughly A$60.4b by the market.
For investors focused on cash flow strength, Woodside Energy Group brings a mix of big-ticket LNG projects, conventional oil and gas output, and newer lower carbon initiatives that all feed into long term projections of what those assets might throw off.
"Investor optimism appears driven by expectations for long-term demand growth in Asian and emerging markets, with Woodside's global LNG expansion (Louisiana, Scarborough) positioned to capture this demand. However, these assumptions may underestimate the potential for rapid decarbonization policies or renewable adoption, which could affect future revenue and volume growth if LNG demand softens in key markets."
The real swing factor is whether one crucial assumption about future energy demand holds up long enough for those cash flows to fully materialize.
If that demand wildcard matters to you, read the full narrative for Woodside Energy Group to see how Woodside Energy Group could still accelerate if LNG expectations and policy paths decouple.

Westgold Resources (ASX:WGX)
Westgold Resources is a Perth based gold miner whose cash flow story is built on producing assets rather than early stage prospects, with Murchison generating about A$1.7b of revenue and Southern Goldfields about A$732 million, and the stock valued near A$5.0b.
For the Undervalued Stocks Based On Cash Flows theme, Westgold Resources matters because its producing Murchison and Southern Goldfields hubs already generate the operating cash that underpins DCF estimates, rather than relying mainly on distant projects or blue-sky assumptions.
"The integration of the Karora transaction has significantly increased Westgold's production scale and operational flexibility. This positions the company to benefit fully from sustained global monetary instability and rising geopolitical tensions, with upside leverage to higher gold prices directly feeding into revenue and earnings."
The main question for investors is what happens if a single pressure on costs and margins shifts just as that extra scale takes effect.
If that cost reset is what you are watching, read the full narrative for Westgold Resources to see whether Westgold Resources looks primed for accelerating upside or stalled gains.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the strongest breakout stories rarely stay quiet for long. Scan fresh ideas with real momentum before they get fully caught by the crowd. Act now.
- Spot cash rich giants quietly building momentum by running the list of solid balance sheet and fundamentals (11 results) while these under the radar players are still priced as if nothing has changed.
- Target income streams that keep paying even when sentiment cools by reviewing the 3 dividend fortresses before payouts and resilient balance sheets attract late money.
- Hunt for producers tied directly to real assets by using the 36 elite gold producer stocks while these operators remain priced as if gold strength will not last.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com