
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
House Foods Group (TSE:2810), What Is Behind The Fresh Attention?
House Foods Group (TSE:2810) is back in focus after UBS highlighted potential changes around its Ichibanya curry restaurant chain, as well as broader efforts to lift capital efficiency and sharpen the group’s spice centered business mix.
At a share price of ¥4,073, House Foods Group has logged a 1 month share price return of 8.93% and a year to date share price return of 40.09%, while the 1 year total shareholder return of 43.67% hints that momentum has been building in connection with the latest UBS driven restructuring story.
Scan other potential restructuring and capital return stories alongside House Foods Group with our hand picked list of 74 high quality undiscovered gems for investors watching this theme closely.
House Foods Group has already sprinted higher on the UBS restructuring story, so the real tension is whether you pay up now or wait for a cooler entry as the valuation picture comes into focus.
Price-to-Earnings of 33.7x: Is it justified?
House Foods Group now trades on a P/E of 33.7x, which is a punchy tag when set against both its own earnings profile and peers in the Japanese food sector.
The P/E ratio compares the current share price to per share earnings, so a higher multiple usually signals that investors are paying up for earnings quality, stability or expected profit growth. For a consumer staples group that spans spices, processed foods, health products and the Ichibanya restaurant chain, that premium often reflects the appeal of steady cash generation rather than rapid expansion.
In this case the market is assigning a much richer P/E to House Foods Group than to the JP Food industry average of 16.8x and the peer group average of 24.3x. The implied fair P/E from Simply Wall St’s fair ratio framework is 21.9x. This is well below the current 33.7x level and suggests a valuation that could move closer to that fair ratio if sentiment around growth, returns on equity or restructuring outcomes cools down.
Explore the SWS fair ratio for House Foods Group.
Result: Price-to-Earnings of 33.7x (OVERVALUED)
Still, the UBS story around House Foods Group can stall if restructuring of the Ichibanya chain underwhelms, or if capital allocation shifts away from shareholder returns.
Find out about the key risks to this House Foods Group narrative.
Another View on House Foods Group's value
The earlier P/E work portrays House Foods Group as expensive. The SWS DCF model points the other way. At ¥4,073, the shares sit around 34.1% below an estimated future cash flow value of ¥6,176.32, which presents the stock as undervalued on this measure.
That is a big gap. It raises a simple question for investors: Is the P/E premium a warning sign, or is the DCF suggesting that the market may still be underrating what House Foods Group can earn over time?
Look into how the SWS DCF model arrives at its fair value.
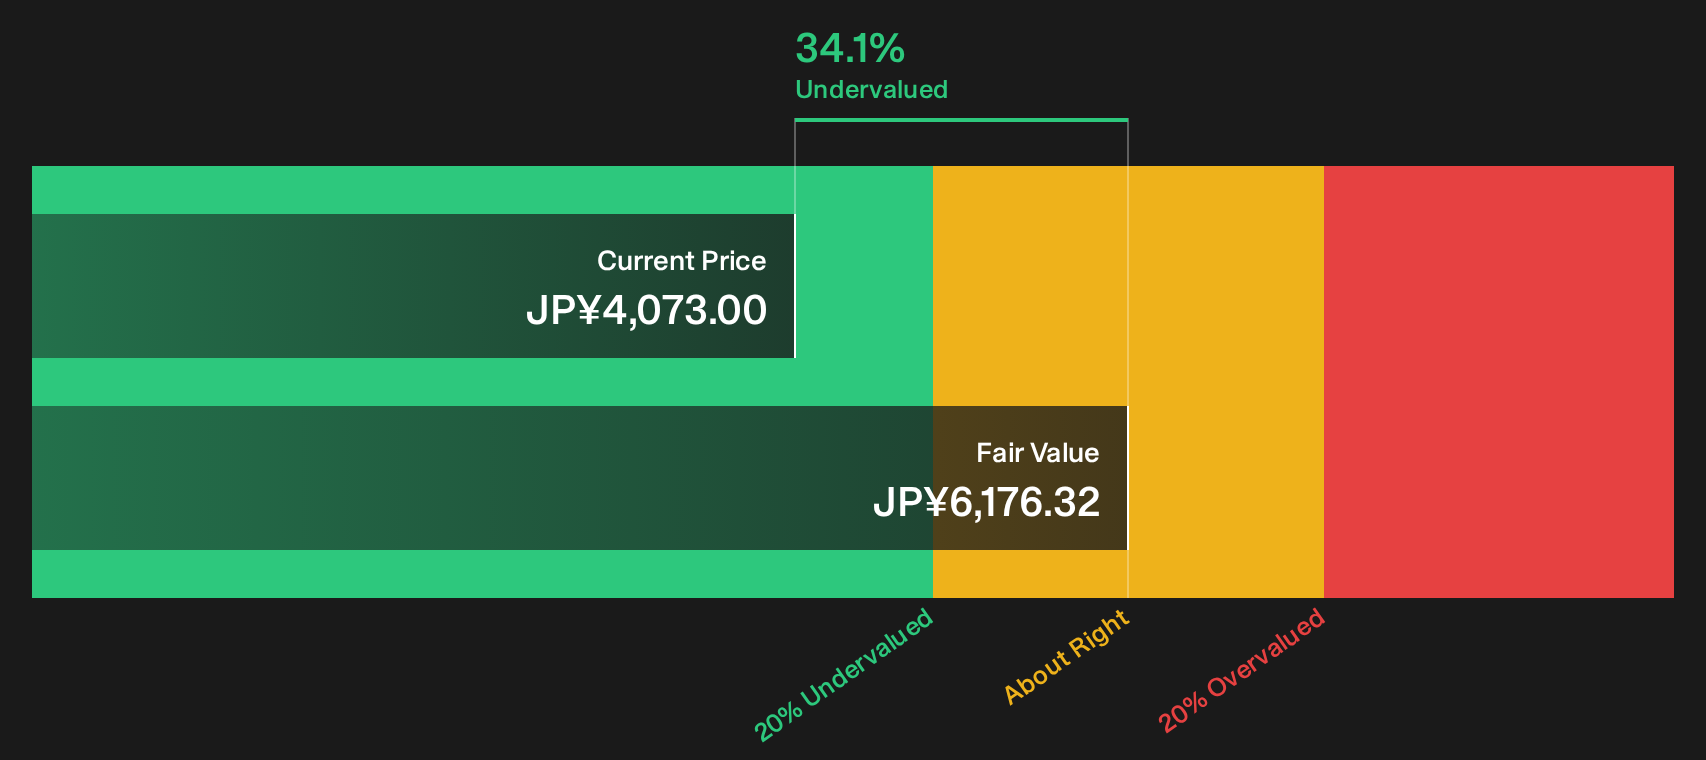
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out House Foods Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of optimism and caution around House Foods Group feels hard to balance, move quickly and test the numbers against your own expectations. To see what the market is currently rewarding, take a closer look at its 3 key rewards.
Looking for more House Foods Group style ideas?
Do not stop your research with House Foods Group. Broaden your watchlist now so you are not chasing the next opportunity after it has already moved.
- Target potential mispricing early and scan companies trading below their implied worth with the 18 high quality undervalued stocks.
- Strengthen your defensive side and focus on businesses built to weather shocks through the 20 resilient stocks with low risk scores.
- Hunt for tomorrow's stories before the crowd by reviewing the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com