
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Goodyear Stock’s Sales Slump Means For Shareholders
- Goodyear Tire & Rubber has been dealing with difficult end markets, with sales declining over the last two years and earnings per share falling each year despite revenue growth.
- Ongoing cash burn and shareholder dilution are raising questions about Goodyear Tire & Rubber’s ability to turn its current operating footprint into sustainable long term growth.
- We will now look at how Goodyear Tire & Rubber’s investment narrative is affected by continued end market pressure on sales and earnings.
Goodyear Tire & Rubber Investment Narrative Recap
For an investor to stay with Goodyear Tire & Rubber, there needs to be confidence that weak end markets and cash burn can eventually give way to a steadier, self funding tire business. The near term swing factor is whether pricing, mix, and utilization can stabilize enough to slow earnings pressure despite ongoing competition and tariff related cost strain.
The biggest risk right now is simple: persistent losses and continued shareholder dilution erode the value of any future recovery. The latest news on softer sales and falling earnings per share reinforces that concern rather than changing it. The core question remains whether current restructuring and mix efforts can meaningfully close the profitability gap.
Recent commentary around the Goodyear Forward restructuring program is the clearest operational reference point for this backdrop. Management is targeting cost savings from plant closures, supply chain upgrades, and a tighter manufacturing footprint. Those actions are designed to address the very issues investors are worried about, such as cash burn and underused capacity.
For you as a shareholder, the link to catalysts is direct. Any evidence that Goodyear Tire & Rubber is actually reducing manufacturing inefficiencies, improving product mix toward larger rim size and premium tires, and keeping tariff and inflation headwinds in check will matter more than short term market noise. Failure to execute on these restructuring and cost actions would leave the business exposed to the same competitive and demand pressures already visible in the recent results.
Goodyear Tire & Rubber's narrative projects US$19.1b revenue and US$1.1b earnings by 2029. This assumes 2.6% yearly revenue growth and an earnings increase of about US$3.6b from a loss of US$2.5b today.
Uncover why Goodyear Tire & Rubber's fair value indicates a 49% potential upside to its current price that could narrow quickly.
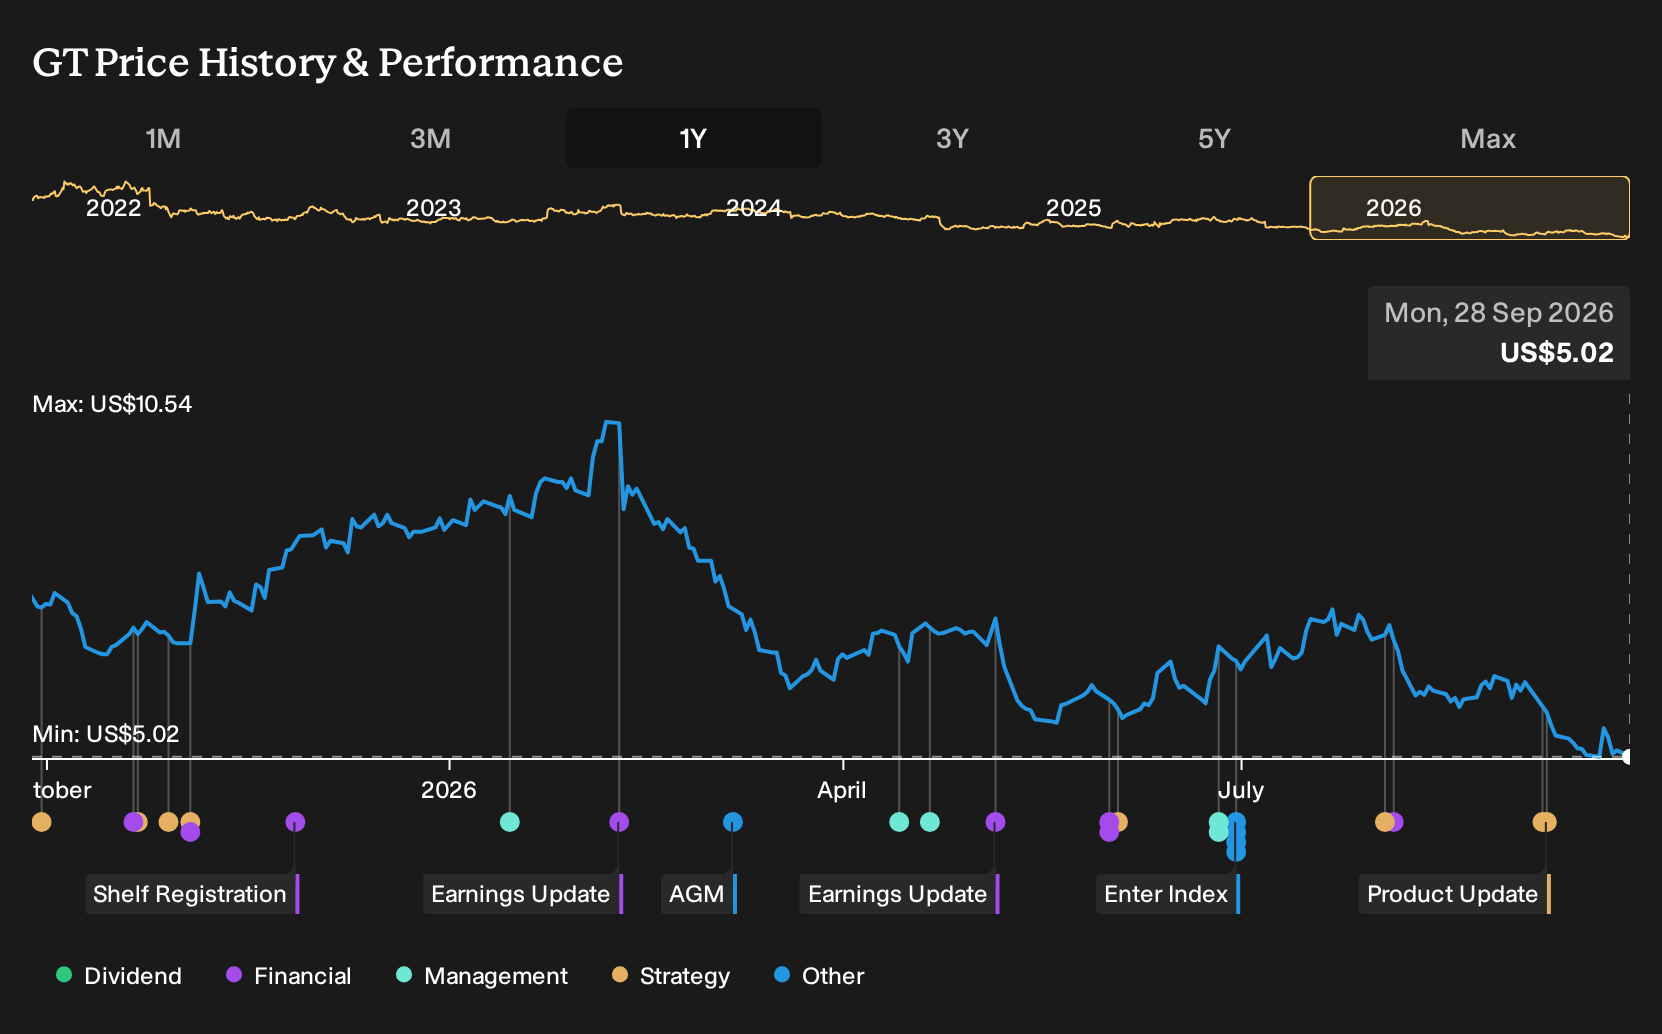
Exploring Other Perspectives
One alternate view puts Goodyear Tire & Rubber’s weak demand risk front and center. The most pessimistic analysts were only looking for revenue of about US$18.6b and earnings of US$117.0m by 2029 before this news. That is a much thinner recovery path, and fresh information could easily push those expectations lower or higher.
Explore 3 other Goodyear Tire & Rubber fair value estimates, including one that suggests it could be worth just $7.46!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Goodyear Tire & Rubber research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Goodyear Tire & Rubber. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Goodyear Tire & Rubber's overall financial health at a glance.
Looking For More Ideas Beyond Goodyear Tire & Rubber?
If the current Goodyear Tire & Rubber setup feels finely balanced, it can help to widen your watchlist to other businesses with different risk profiles and balance sheet characteristics.
- For investors who want value combined with quality fundamentals, consider reviewing 32 high quality undervalued stocks that meet strict cash flow and balance sheet criteria.
- If income is your priority, you can focus on companies that aim to pair higher yield with resilience by scanning 6 dividend fortresses.
- For a broader shortlist of financially robust businesses, filter for stronger balance sheets and cleaner fundamentals using our curated 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com