
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
JCDecaux (ENXTPA:DEC) Could Be 25% Undervalued As Momentum Tests Valuation
JCDecaux (ENXTPA:DEC) has drawn fresh attention after a strong recent run in the share price, with the stock showing solid positive moves over the past month and past 3 months. Investors are now reassessing the advertising specialist’s fundamentals.
The recent move is part of a much stronger trend, with JCDecaux posting a 90 day share price return of about 30%, a year to date share price return of roughly 62%, and a 1 year total shareholder return of around 71%. This points to clear positive momentum as investors reassess both growth prospects and risks around the current €25.0 price.
Scan JCDecaux's momentum against hand-picked peers by reviewing our curated list of 197 high quality undervalued stocks that also show strong share price interest.
The jump in JCDecaux could signal investors are warming to the underlying outdoor advertising business, or it could simply reflect a burst of optimism in the share price. That difference is what the valuation now needs to test.
Most Popular Narrative: 25% Undervalued
JCDecaux's most followed narrative pegs fair value at about €33.49, which sits well above the recent €25.0 close and suggests investors are weighing a stronger medium term earnings profile against the current price.
JCDecaux's unique ownership of both DSP and SSP programmatic platforms, combined with its integrated international footprint, allows for monetization of both direct-to-brand and long-tail advertisers, capturing a much larger share of the $300 billion global digital advertising pool, which could unlock multiple new recurring revenue streams far beyond traditional expectations.
See why 1 investors see JCDecaux as 25% undervalued.
Result: Fair Value of €33.49 (UNDERVALUED)
Still, the bullish JCDecaux narrative runs into two clear pressure points: slower than expected digitisation in regulated markets and heavy capital spending that could weigh on margins.
Find out about the key risks to this JCDecaux narrative.
Another View on JCDecaux’s Valuation
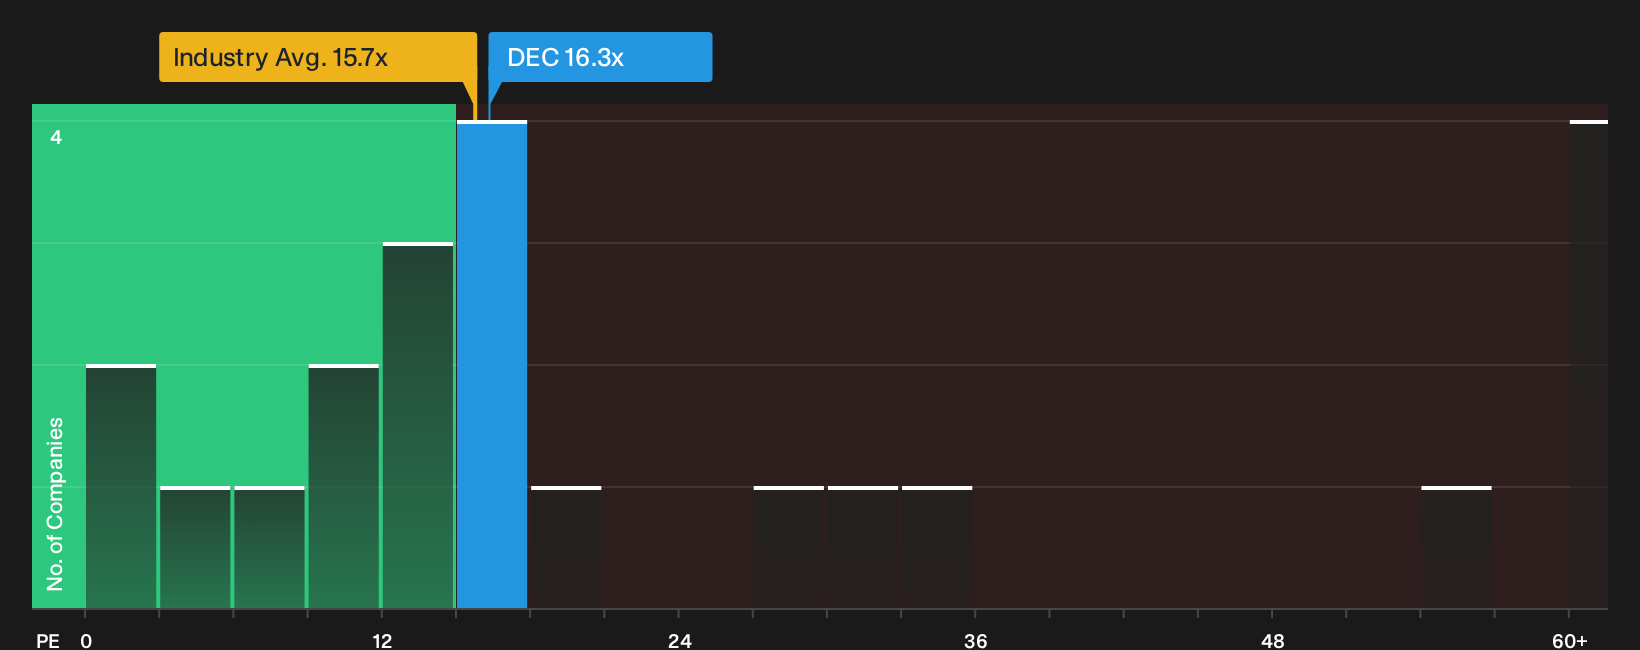
There is a very different reading of JCDecaux when the focus shifts from analyst fair value to what the current P/E implies. At about 16.3x earnings, the stock trades above both the French Media sector on 15.7x and the peer average on 9.1x. The fair ratio is 14.2x, which points to a richer pricing that leaves less room for error if earnings or sentiment soften.
For investors who rely on ratio-based checks, that gap raises a simple question: Is this a premium you are comfortable paying for JCDecaux today, or a signal to wait for more evidence before supporting the bullish story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around JCDecaux is clearly split, which makes this a useful moment to check the underlying data yourself and decide how comfortable you are with the current pricing. To weigh both the upside debate and the concerns that some investors are flagging, take a closer look at the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond JCDecaux?
If JCDecaux has sharpened your focus on pricing and quality, expand your watchlist with a few targeted stock ideas built from Simply Wall St’s powerful screener tools.
- Target reliable cash flows by scanning companies that combine strong fundamentals with a resilient financial position through this curated list of solid balance sheet and fundamentals (202 results).
- Hunt for mispriced opportunities by zeroing in on businesses that pair quality metrics with attractive valuations using our focused 197 high quality undervalued stocks.
- Prioritise stability and income by reviewing a carefully filtered 221 resilient stocks with low risk scores that may help anchor your portfolio when markets turn choppy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com