
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
EU Hybrid Import Cap Could Be A Game Changer For Forvia Stock
- EU policymakers have been weighing a cap on Chinese hybrid vehicle exports. This puts Forvia's role as a key interiors and electronics supplier to European automakers under fresh scrutiny because trade rules can alter supply chains and pricing power for its customers.
- The focus now lands on Forvia's electronics operations, where any change in hybrid competition could influence the mix of new orders, the profitability of its backlog, and how much pricing discipline the business can maintain with both Chinese and Western carmakers.
- We will now assess how Forvia's investment narrative is affected by potential EU limits on Chinese hybrids and resulting supply chain shifts.
Track how EU trade rules ripple through the auto supply chain by scanning a curated set of resilient manufacturing and supplier stocks in our list of solid balance sheet and fundamentals (202 results).
Forvia Investment Narrative Recap
For an investor to stay in Forvia, the key belief is that its broad exposure to seating, interiors, electronics and lighting can turn heavy transformation work into healthier margins and cash flow. The potential cap on Chinese hybrid exports mostly affects the electronics order mix rather than the whole group, so the wider thesis around portfolio simplification and deleveraging remains intact.
The near term swing factor is still execution on restructuring and asset disposals, which influence interest coverage and balance sheet resilience. The biggest risk remains high transformation expenses, especially if cost savings and Hella synergies arrive slowly or if trade changes increase pricing pressure rather than easing it.
There have been no fresh company announcements directly tied to the EU discussion on Chinese hybrids. That puts even more emphasis on the existing plan investors already know. The focus is still on order intake in advanced electronics and interiors, the quality of the backlog and the timetable for Project Simplify savings and portfolio sales.
In that context, the most relevant information is the ongoing push to streamline operations and dispose of non core assets to reduce leverage. Those actions matter even more if trade rules alter volume patterns between Chinese and Western OEMs. Balance sheet progress, interest coverage and how Forvia prices new electronics programs sit at the center of the near term catalyst mix.
Forvia Forecasts and What They Assume
Forvia's analyst narrative points to revenues of €21.3 billion and earnings of €484.8 million by 2029, with consensus assuming revenue stays broadly flat over the next three years, an earnings shift from a loss of €1.5 billion today to that 2029 level, and profit margins moving from a 7.0% loss to a 2.3% margin.
Uncover how Forvia's fair value indicates a 70% potential upside to its current price, which could narrow quickly.
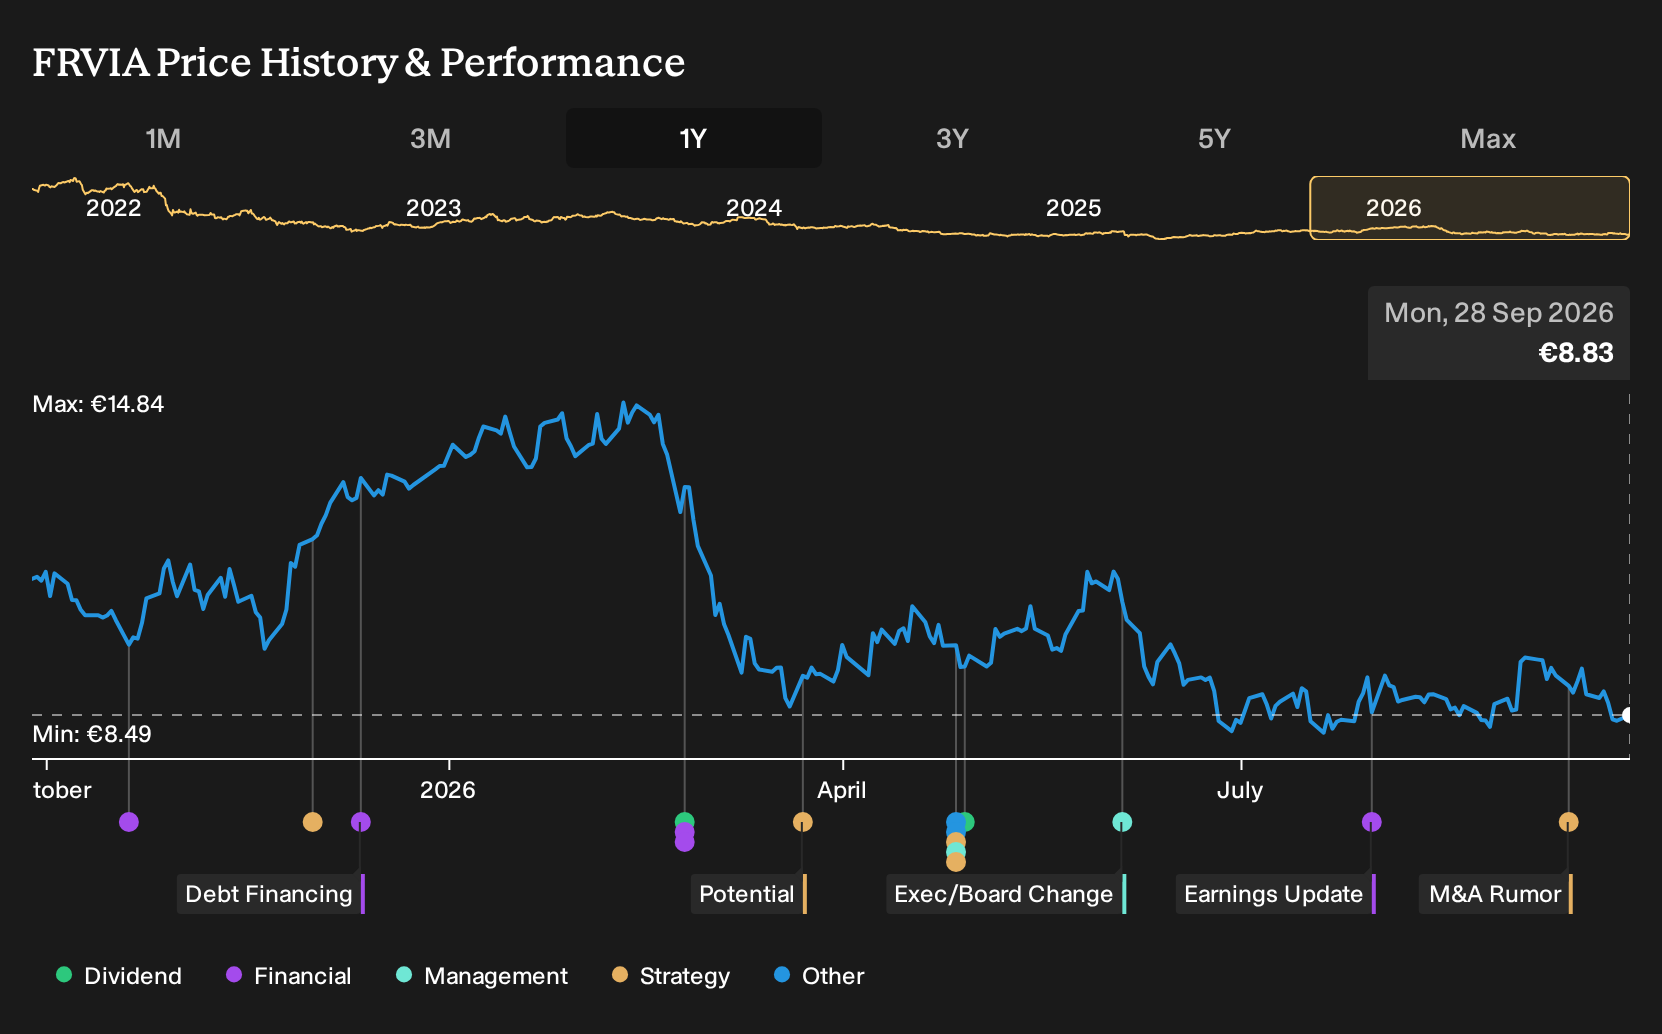
Exploring Other Perspectives
One bullish angle on Forvia puts much more weight on Chinese partnerships as a potential growth engine, which contrasts sharply with worries about trade frictions. Those optimistic analysts were pencilling in revenue of €29.6b and earnings of €914.9m by 2028 before this EU hybrid debate. Use that spread to stress test your own view, especially because fresh rules could reshape both stories.
Explore 2 other Forvia fair value estimates, including one that suggests potential upside of up to 183% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Forvia research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Forvia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Forvia's overall financial health at a glance.
Looking For More Ideas Beyond Forvia?
Once you have a view on Forvia, it can help to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener gives you a quick way to scan focused groups of businesses that share the traits you care about most.
- For investors hunting for value with quality in mind, review a curated 197 high quality undervalued stocks that combine stronger fundamentals with more attractive pricing.
- If capital preservation matters just as much as upside, consider a basket of 221 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- When you want to get ahead of the crowd, check a focused set of 618 high quality undiscovered gems that pair solid financials with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com