
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Could Playocity Partnership Just Shift Hasbro (HAS) Investment Narrative?
- On 16 September 2026, BAAN Holding Group Company reported that implementation works had begun for Playocity, a 2,600 square meter family entertainment project at Westfield Center in Jeddah, developed in partnership with Hasbro and built around Hasbro’s global characters and brands.
- The Playocity partnership gives Hasbro another physical outlet for its intellectual property in Saudi Arabia, tying branded experiences to a growing leisure market and potentially widening the audience for its toys, games, and content in the region.
- We will examine how Hasbro's investment narrative is influenced by the Playocity partnership in Jeddah as a branded experiential footprint.
Scan how Hasbro’s Playocity tie up fits into a wider push toward branded family entertainment by reviewing our hand picked 92 robotics and automation stocks building the next generation of themed experiences.
Hasbro Investment Narrative Recap
To hold Hasbro, you need to believe management can keep turning its toy and game brands into higher margin entertainment, digital and licensing income while keeping debt in check. The main near term swing factor still sits in how consistently Wizards of the Coast and broader licensing perform, because that mix matters more to earnings quality than a single themed venue.
The Playocity news looks incremental rather than central to that near term catalyst. It extends Hasbro’s characters into a physical attraction but does not change the key risk areas that analysts already flag, such as reliance on a few blockbuster franchises and exposure to tariffs and retailer caution in Consumer Products.
Among recent context, analysts still frame Hasbro around earnings that are forecast to grow 6.9% a year with revenue at 4% a year and a business that only recently returned to profitability. The Playocity agreement fits alongside that narrative as another way to license characters instead of a shift in the core digital and tabletop engine.
For you as a shareholder, the useful question is how consistently Hasbro can repeat deals like Jeddah while managing the costs and royalty structures that come with heavier licensing and external partnerships. Execution on cost rationalisation, supply chain diversification and SKU pruning remains a bigger operational catalyst than any single entertainment destination using the brands.
Hasbro's narrative projects US$5.5b revenue and US$1.0b earnings by 2029. This projection is based on 4.7% yearly revenue growth and an earnings change of about US$1.2b from a loss of US$222.6m today.
Uncover why Hasbro's fair value indicates a 23% potential upside to its current price, which could close faster than many investors expect.
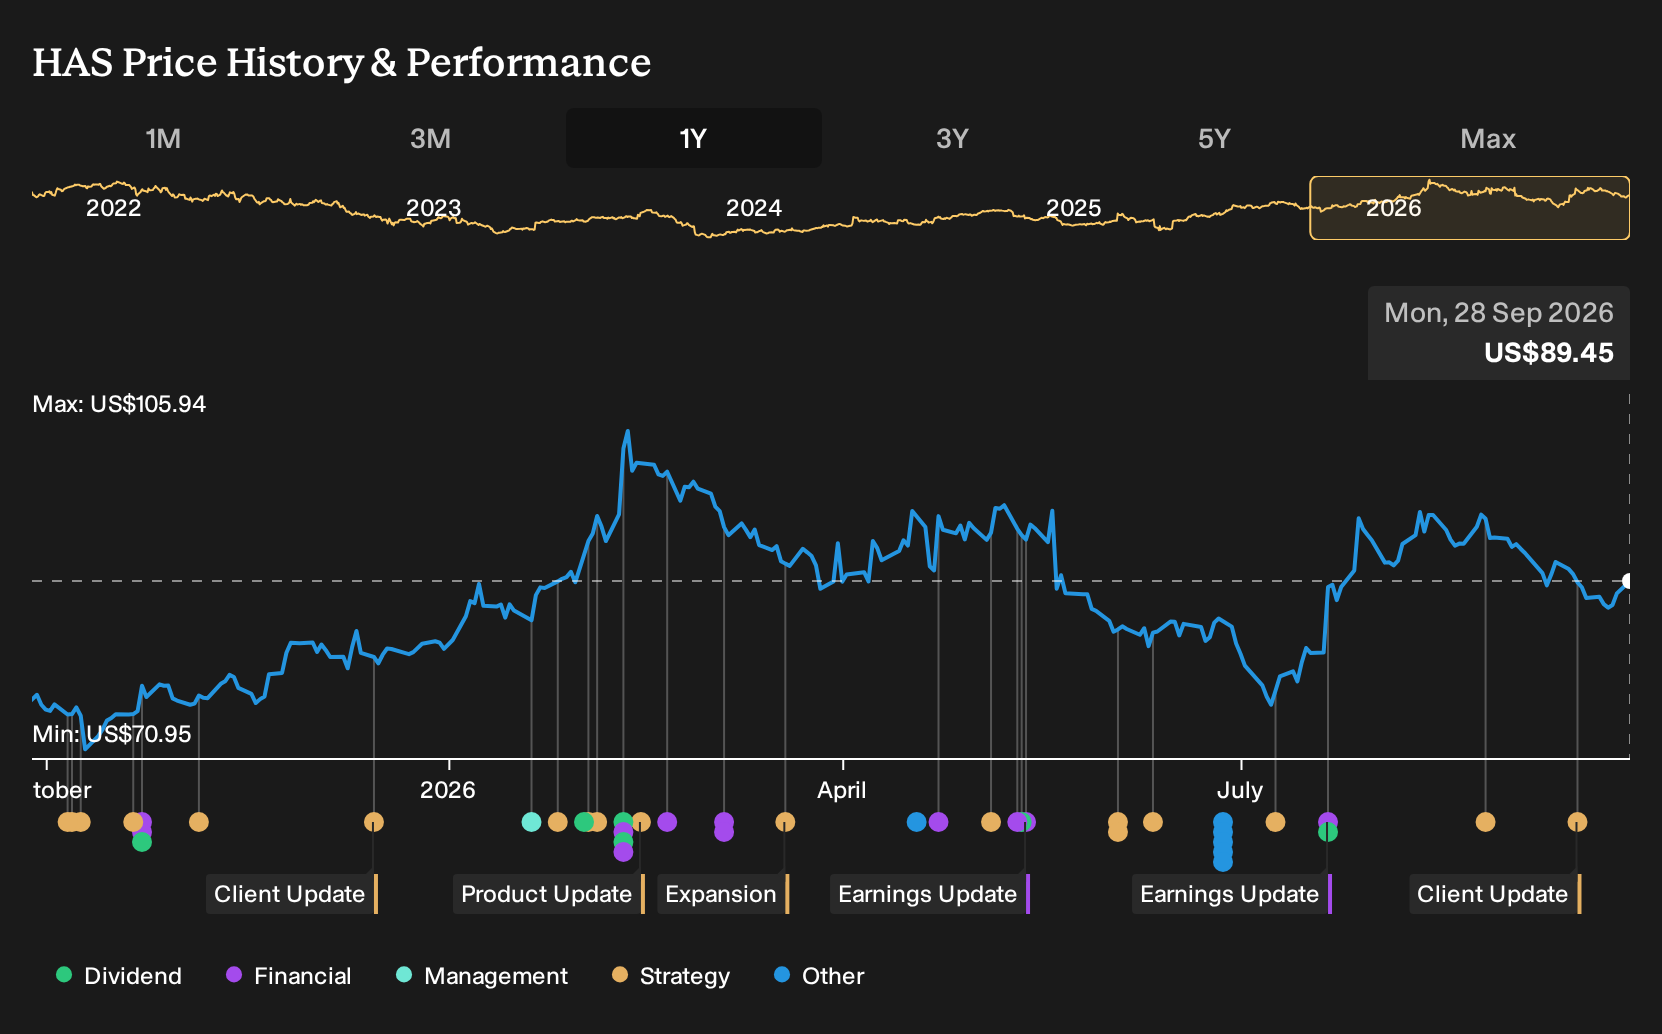
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$110 and US$156, which already shows how far opinions on Hasbro can spread. When you set that against risks like reliance on a handful of blockbuster franchises and rising tariff exposure, you have strong reasons to compare multiple viewpoints before deciding your own stance.
Explore another Hasbro fair value estimate, including one that suggests as much as 74% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hasbro research is our analysis highlighting 6 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hasbro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hasbro's overall financial health at a glance.
Looking For More Ideas Beyond Hasbro?
If the Hasbro story has sharpened your thinking but you want a broader watchlist, it can help to scan other companies that match specific traits rather than trawling through thousands of tickers one by one.
- If you are hunting for value with quality in mind, start with a focused set of 33 high quality undervalued stocks that already clear basic balance sheet and cash flow hurdles.
- For readers who care more about resilience and capital preservation, narrow your search to 30 resilient stocks with low risk scores that score well on financial strength and volatility checks.
- If you prefer backing strong fundamentals with less crowd attention, widen your research to a curated 16 high quality undiscovered gems that might not yet be on every investor’s radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com