
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Great Dividend Stocks To Own In September 2026
Bond yields are rising as oil climbs above US$108 and borrowing costs move to levels last seen in 2007. That puts pressure on rate sensitive assets and pushes investors to look harder at what actually pays them to wait. Reliable dividend payers offering more than a 3% yield can help turn volatility into regular cashflow. This article breaks down three income focused stocks from that group.
The three dividend stocks in this article are a starting sample only, and the full Dividend Powerhouses screen surfaced another 171 companies with income profiles and business stories that are not covered here.
If you want to identify, analyze and sort those extra opportunities by yield strength and payout quality, head straight to the Dividend Powerhouses (3%+ Yield) screener
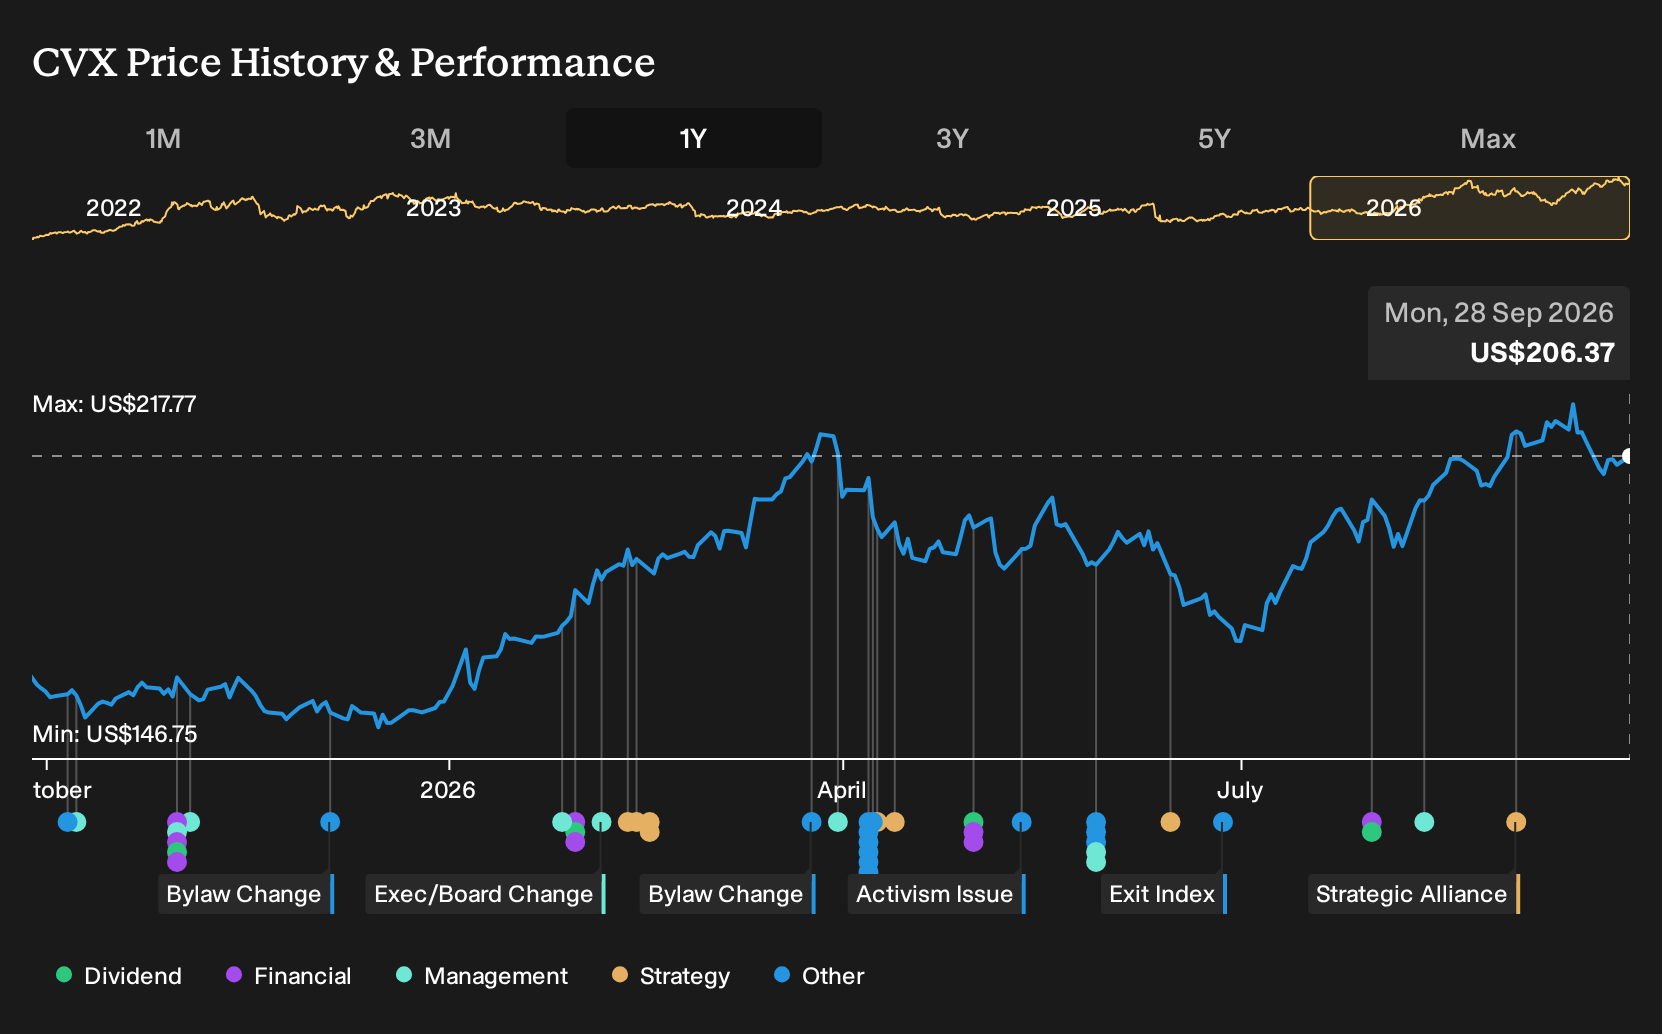
Chevron (CVX)
Chevron matters for a 3%+ yield screen because its integrated model throws off cash from both oil production and fuel sales, while the downstream arm gives investors a clearer line of sight to regular payouts backed by real world energy demand.
Chevron runs an integrated energy and chemicals operation, with sizeable revenue from US$55.1b in international upstream, US$52.6b in US upstream, and even larger downstream activities that total about US$161.2b across fuel refining, marketing, and lubricants. This supports a dividend focused profile at a roughly US$401.0b market value.
"Record production growth, especially in the Permian and from the Hess acquisition in areas such as Guyana and the Bakken, now sits on top of capital and drilling programs that aim to keep Permian volumes around 1 million barrels per day with lower CapEx per barrel, which supports future revenue and free cash flow."
The real swing factor for Chevron’s income story now rests on how one pressure on long term profitability and cash conversion ultimately plays out.
That pressure point is exactly what the full narrative for Chevron unpacks, showing where Chevron’s cash engine could accelerate, stall, or be quietly masked by headline oil prices.
United Parcel Service (UPS)
United Parcel Service gives this 3%+ yield screen a logistics backbone, since its regular dividend is tied directly to the cash it earns moving parcels for retailers, exporters, and e-commerce players rather than more cyclical or speculative revenue streams.
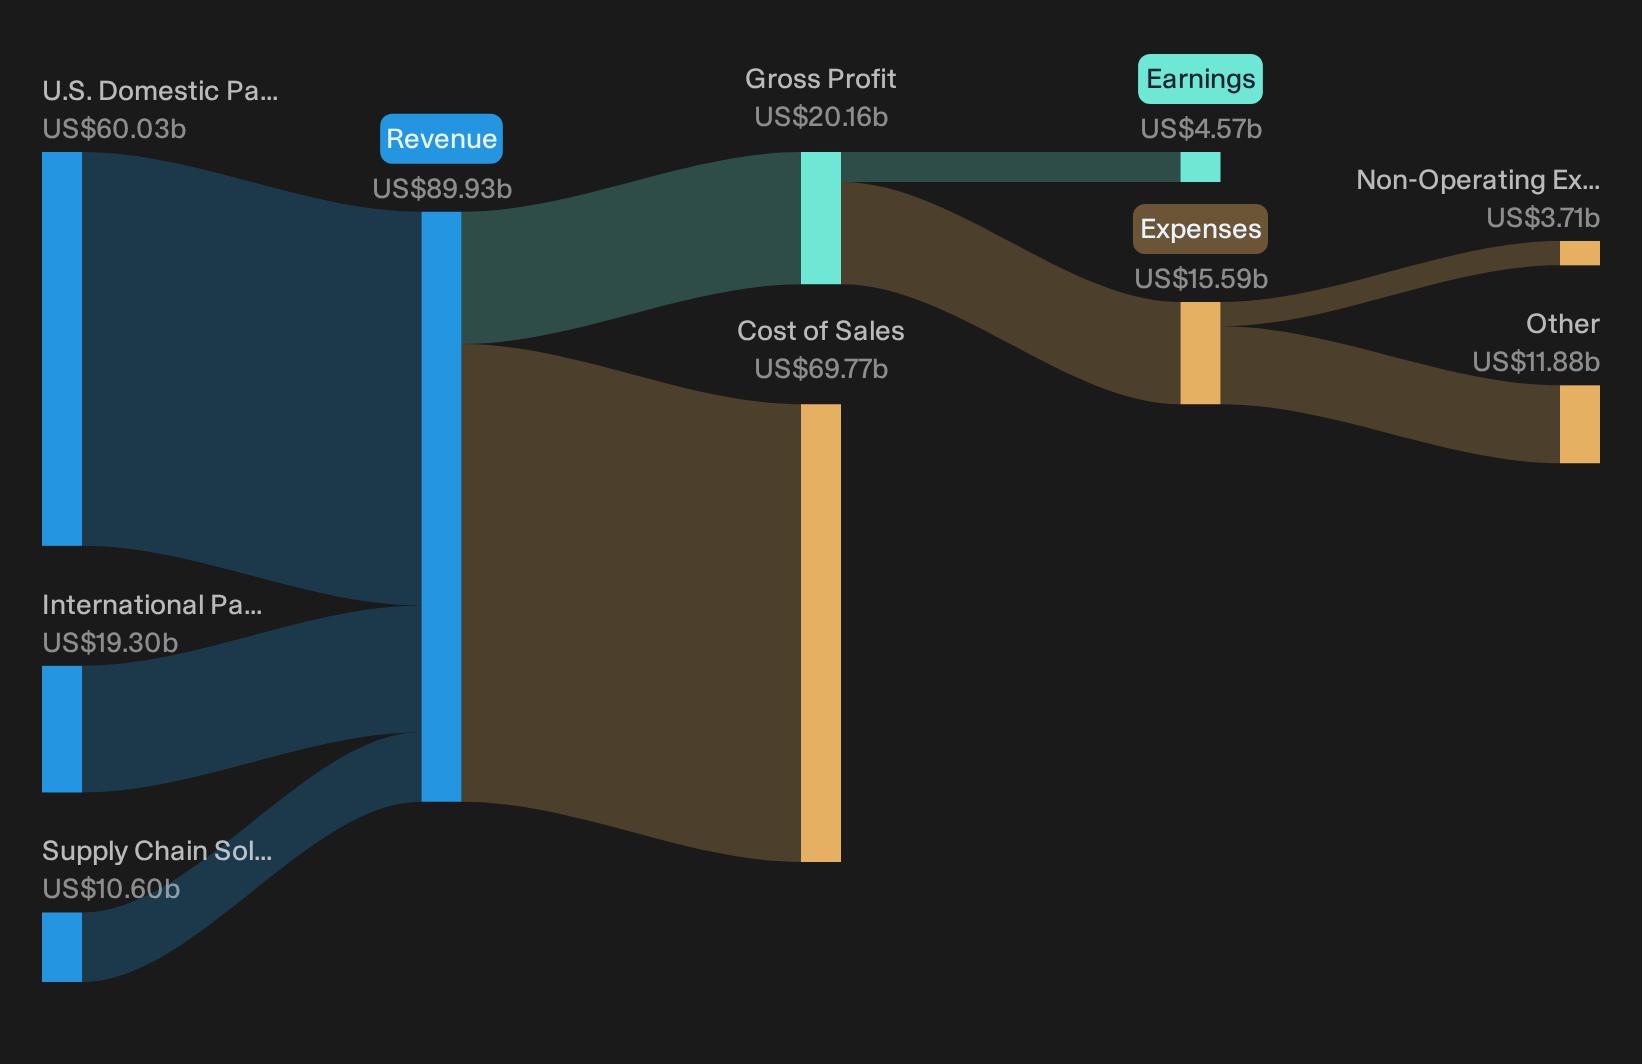
United Parcel Service runs global package delivery and logistics, with its dividend linked to cash flow from U.S. Domestic Package services generating about US$60.0b, International Package adding roughly US$19.3b, and Supply Chain Solutions contributing around US$10.6b in revenue, supporting a market value near US$79.9b.
"Launched in early 2025, UPS's "Efficiency Reimagined" outlined the company’s largest network overhaul in company history. This multi-year initiative presents management's goals to streamline domestic operations."
What really matters for dividend investors now is how one unresolved cost and efficiency squeeze shapes future cash coverage of that rich payout.
That cost squeeze is exactly what the full narrative for United Parcel Service unpacks, showing where UPS’s cash engine could be accelerating, stalling, or quietly masked by headline parcel volumes.
VICI Properties (VICI)
VICI Properties gives this Dividend Powerhouses screen a pure play on long-term, triple-net leased casino real estate, with rental income from 63 gaming properties and other experiential venues in the US underpinning a US$4.1b real estate revenue base and a market value near US$25.9b.
"Given the historical data presented, my assumption is that the company will be able to growth its revenues ~3.5-4.5% during Year 1 and ~3.5-5.5% each year from Year 2-5."
For dividend focused investors, what happens to that cash flow once one quiet pressure on leverage and funding costs really starts to bite will matter most.
Once that funding pressure starts to bite, the full narrative for VICI Properties shows where VICI Properties’ cash engine could be quietly accelerating or masked by headline rent growth.

Seeking Fresh Alternatives Before They Fly
Some of the most interesting ideas quietly build momentum before anyone notices. Spot potential breakouts while they are still under the radar for now, and get in early.
- Target income potential with established businesses that still have balance sheet strength by reviewing the curated 6 dividend fortresses before yields start dropping.
- Hunt for future enablers of AI capacity and data traffic by scanning the focused 84 AI infrastructure stocks while these picks are still building momentum.
- Track the build out of next generation electricity networks by reviewing the curated 39 power grid technology and infrastructure stocks before grid upgrade stories get fully caught by the crowd.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com