
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Index Removal Altering The Investment Case For Protector Forsikring Stock (OB:PROT)?
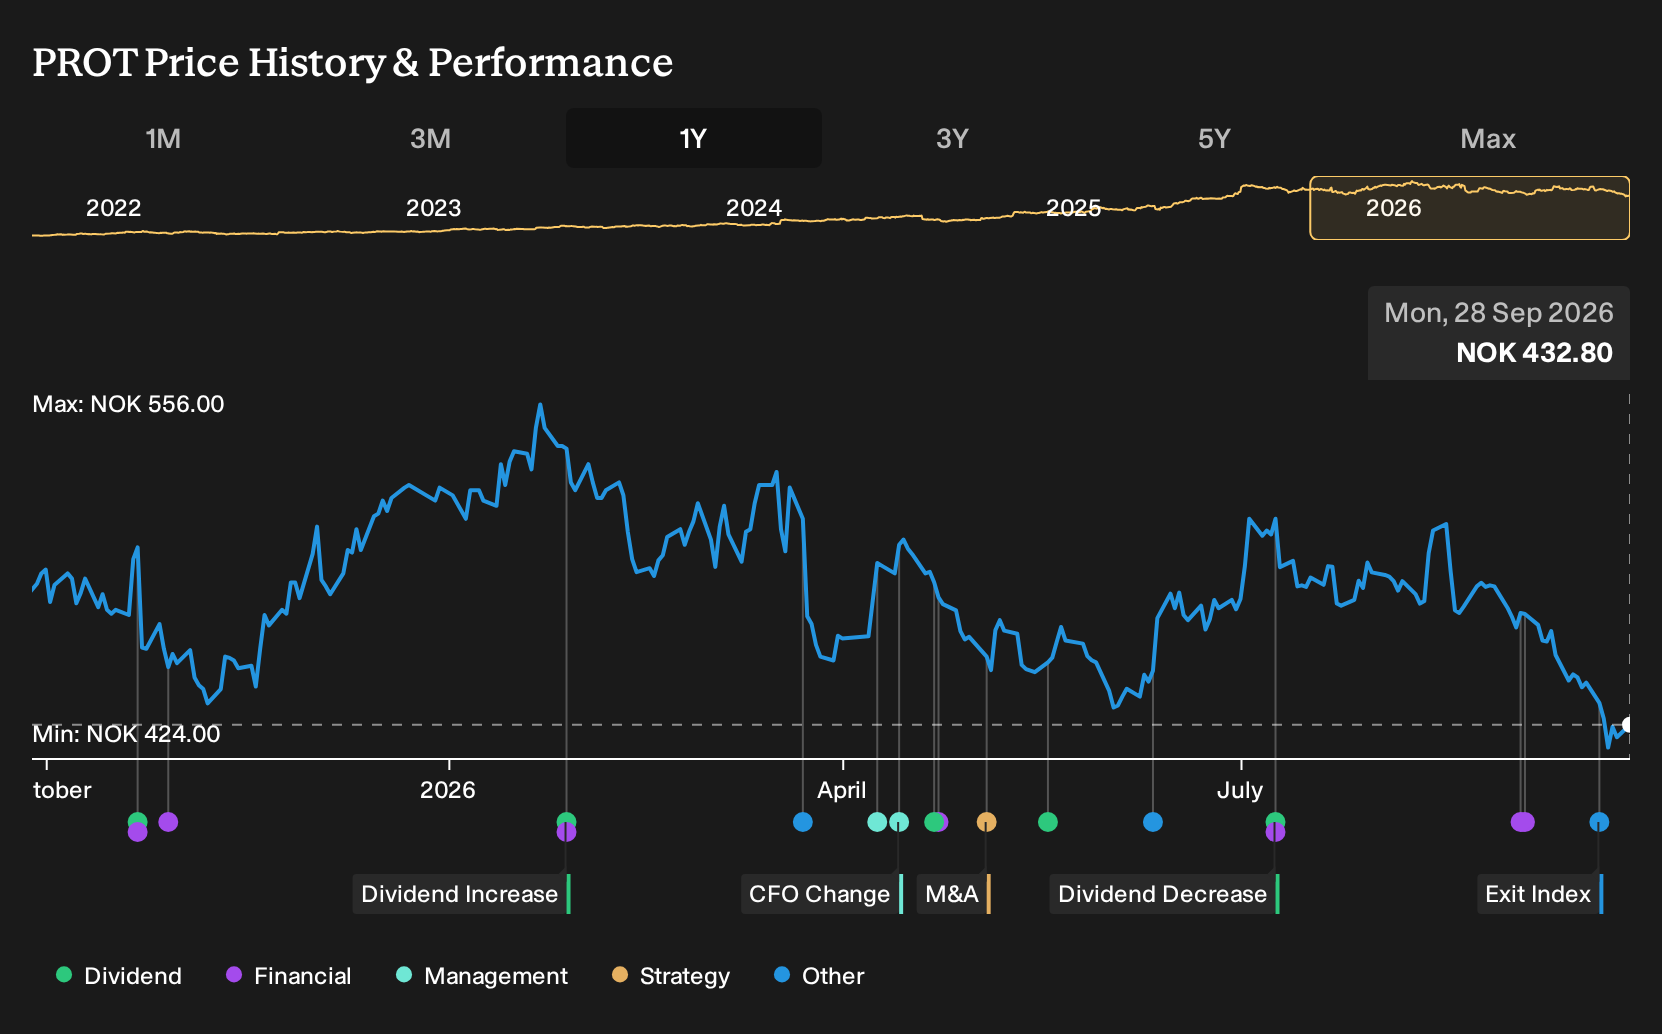
- Protector Forsikring ASA was removed from the Oslo OBX Total Return Index on 21 September 2026, following the latest index rebalancing.
- The index exclusion highlights how Protector Forsikring's access to passive capital and trading liquidity can shift, even while its underlying insurance operations remain unchanged.
- We will now see how Protector Forsikring's index removal could reshape its investment narrative, especially around liquidity and institutional ownership.
Scan beyond Protector Forsikring and compare this index removal story with other hand-picked insurers and financials screened for liquidity and balance-sheet strength in the list of solid balance sheet and fundamentals (202 results).
Protector Forsikring Investment Narrative Recap
To hold Protector Forsikring, you need to be comfortable with a fairly focused non life insurer that leans on data, technology and selective market expansion. The big swing factor in the near term remains how pricing and churn develop in Sweden and the U.K. The index removal itself does not change underwriting, claims or reinsurance decisions, so the business drivers are intact.
The more meaningful risk still sits in execution. Swedish motor competition, early stage costs in France and customer reactions to price moves in the U.K. can all pressure margins. Reinsurance dependence also matters. If pricing or terms shift, earnings volatility could increase, regardless of where Protector Forsikring sits in any index.
With no fresh operational announcements tied directly to the OBX exit, the most relevant reference point is Protector Forsikring's existing capital position. The earlier Tier 2 bond placement left the insurer with strong solvency and room to fund ongoing market entries or tech investments, even if equity liquidity tightens somewhat after index exclusion.
For investors, the link back to catalysts is straightforward. A solid buffer gives management scope to keep pushing its AI and data tooling, refine pricing in Sweden and the U.K., and absorb the early cost load in France. Execution on those fronts, not index status, is likely to shape how the Protector Forsikring story develops over the next few years.
Protector Forsikring's narrative projects NOK 18.8b revenue and NOK 2.5b earnings by 2029. This assumes 9.6% yearly revenue growth and a NOK 0.5b earnings increase from NOK 2.0b today.
Uncover why Protector Forsikring's fair value indicates a 34% potential upside to its current price and what could close that gap faster than expected.
Exploring Other Perspectives
The four fair value estimates from the Simply Wall St Community cluster between NOK 581.25 and about NOK 786.77 per share, so private investors are clearly not aligned on Protector Forsikring. That gap reflects real world risks around Swedish and U.K. pricing pressure, reinsurance costs and French expansion, which could all sway future performance.
Explore 3 other Protector Forsikring fair value estimates, including one that suggests it could be worth just NOK581.25!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Protector Forsikring research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Protector Forsikring. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Protector Forsikring's overall financial health at a glance.
Looking For More Investment Ideas Beyond Protector Forsikring?
If Protector Forsikring has sharpened your thinking about risk, liquidity and long term execution, you can use that same lens to scan a broader watchlist. The Simply Wall St Screener can help you build a shortlist of candidates that match your preferences on quality, balance sheet strength and income potential.
- For investors who want potential growth at lower entry prices, review the 124 elite penny stocks with strong financials that pass fundamental checks rather than relying on hype.
- If quality and valuation matter most to you, start with a curated set of companies filtered as 197 high quality undervalued stocks based on cash flows and balance sheet strength.
- For readers focused on income and resilience, scan a hand picked pool of 164 dividend fortresses that combine higher yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com