
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 British Dividend Stocks With Yield Over 3%
Higher interest rates are already pressuring parts of the global economy, which makes reliable income from established UK dividend payers feel more valuable. When cash yields compete for your attention, investors who can lock into robust dividends above 3% with solid coverage and a track record of stability gain a clear edge. This article picks out three higher yielding British dividend stocks from that group.
The three stocks highlighted next are only a sample from this income theme. The full Dividend Powerhouses screen surfaced 63 more companies with similar yield strength and coverage that do not fit into this short article.
If you want to identify and analyze the income ideas that best match your risk profile, head straight to the Dividend Powerhouses (3%+ Yield) screener.
MONY Group (LSE:MONY)
MONY Group runs MoneySuperMarket, MoneySavingExpert, Quidco and several other UK comparison and cashback sites, with insurance and money platforms generating recurring lead fees that directly support its dividend. The group produced about £236.9 million from Insurance, £110.5 million from Money and £49.3 million from Cashback, and is valued at roughly £894 million.
For income investors, MONY Group brings something more interesting than a headline yield. Its core comparison brands supply repeatable, fee based revenue that anchors dividend payments, while a growing member ecosystem adds another layer of potential resilience and upside.
"Expansion of member-based propositions like SuperSaveClub and frequent launches of reward schemes are driving customer acquisition, retention, and higher average revenue per user (ARPU). This positions the business to benefit from the continued accumulation of wealth and a broadening addressable market, which is expected to strengthen recurring revenue over time."
The real swing factor is how one emerging pressure on profitability and cash generation ultimately shapes that steady income profile investors care about.
That swing factor is exactly what the full narrative for MONY Group unpacks, showing where MONY Group’s cash generation could be accelerating and where income risk might be quietly building.

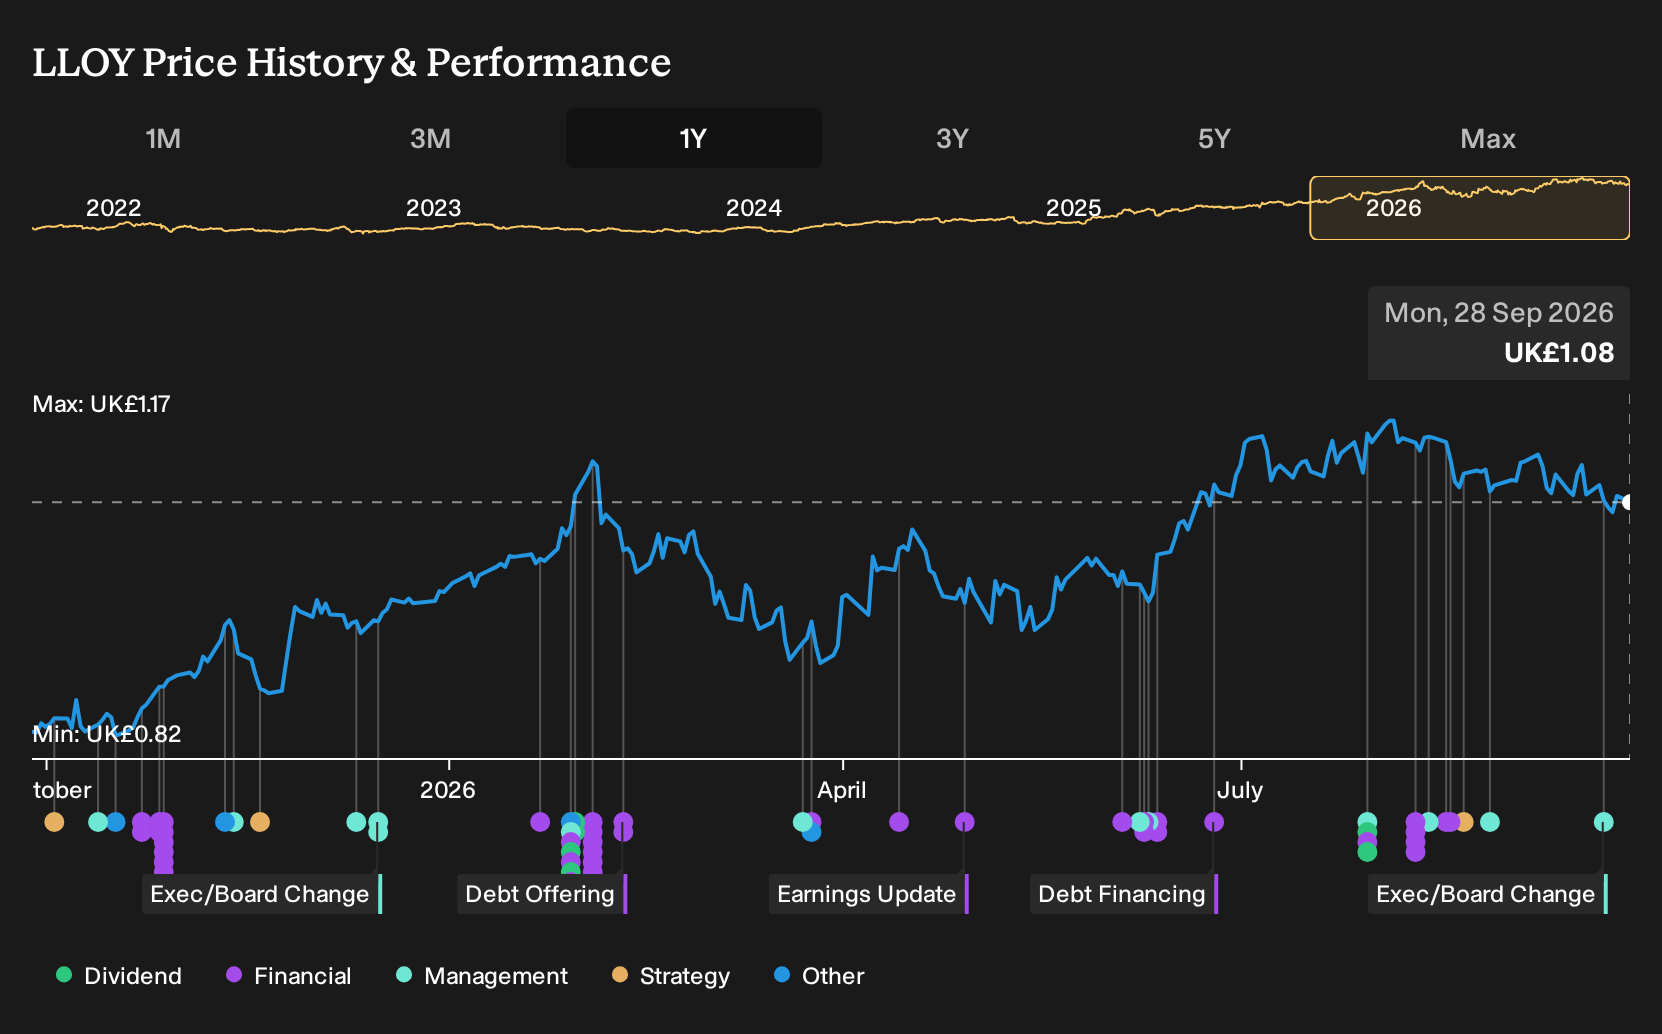
Lloyds Banking Group (LSE:LLOY)
Lloyds Banking Group is a UK focused lender built around everyday current accounts, savings and mortgages, which fits cleanly with the Dividend Powerhouses theme because that retail deposit base supports recurring cash flows and dividend capacity. Retail generated about £11.9b, Commercial Banking £5.7b and Insurance, Pensions and Investments £1.4b, with the group valued at roughly £62.1b.
Lloyds Banking Group offers something income investors often look for in a bank: a large pool of relatively sticky UK retail deposits supporting mortgage and everyday lending, plus an active buyback and dividend program backed by a sizeable earnings base.
"Digital transformation and AI adoption are reducing costs and driving efficiency, supporting margin expansion and improved earnings quality."
What really matters now is how one emerging pressure on credit quality and capital buffers shapes the room Lloyds has to keep rewarding shareholders.
That trade off between credit risk and shareholder returns is exactly what the full narrative for Lloyds Banking Group unpacks, highlighting where Lloyds Banking Group may still be quietly accelerating.
HSBC Holdings (LSE:HSBA)
HSBC Holdings is a global banking group whose dividend appeal in this screen rests on steady net interest income and fee flows from large retail and wealth franchises. Most revenue comes from Corporate & Institutional Banking at about US$27.5b, followed by Hong Kong at US$15.2b and International Wealth & Premier Banking at US$14.4b. The stock is valued at roughly £260b.
Among the bigger yield stories in UK finance, HSBC Holdings offers something different for this screen. Income investors are not just watching a single local mortgage book, but a broad mix of retail, wealth and institutional earnings that support its dividend framework.
"The bank is intensifying investment in Asian wealth management and private banking, leveraging a strong brand and local presence in fast-growing wealth markets such as Hong Kong, mainland China and Southeast Asia. This positions HSBC to capture rising affluence and middle class expansion, which could influence the trajectory of fee income and earnings resilience."
The real test for those future margins and dividend comfort will come if any pressure on credit quality and capital release moves in the wrong direction.
If those capital swings worry you, read the full narrative for HSBC Holdings to see where HSBC Holdings could still be accelerating and which risks might be quietly fading.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities move fast. Breakout stories gain momentum, stay under the radar for a time, then get noticed once the crowd piles in. Be selective, move while it matters, and act with discipline.
- Find cash rich businesses before they are widely followed by scanning the curated list of solid balance sheet and fundamentals (10 results), which focuses on balance sheet strength and resilient fundamentals.
- Follow structural shifts in automation and manufacturing efficiency by tracking the hand picked companies inside 92 robotics and automation stocks that are contributing to the next wave of industrial innovation.
- Explore potential beneficiaries of infrastructure projects by screening the curated 39 power grid technology and infrastructure stocks, which highlights companies linked to grid upgrades and electrification demand.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com