
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To OUTFRONT Media Stock As Creative Chief Appointed
- OUTFRONT Media recently named Mariano Jeger as Chief Creative Officer of IRL Studios, the unified unit that now brings together its Creative Studios and XLabs teams in New York to work across enterprise brands and commercial clients.
- The hire brings agency-side experience from Droga5, TBWA\Media Arts Lab and R/GA directly into OUTFRONT Media’s in-house IRL Studios. This experience could influence how effectively the business converts its out of home footprint and ad tech investments into differentiated creative campaigns for advertisers.
- We will now look at how OUTFRONT Media’s investment narrative might shift as Mariano Jeger takes charge of the unified IRL Studios.
Scan how OUTFRONT Media compares with other advertising and media plays by reviewing a hand-picked 16 high quality undiscovered gems that are quietly building strong fundamentals.
OUTFRONT Media Investment Narrative Recap
To own OUTFRONT Media, you need to believe the shift in out of home advertising toward digital screens and better ad tech can offset structural pressure on static billboards and transit posters. The near term focus is still on filling digital inventory at solid rates and keeping occupancy healthy. Mariano Jeger joining IRL Studios looks helpful, but not a major short term catalyst on its own.
The bigger swing factor remains execution on digital conversion and cost discipline after exits from lower margin contracts in New York and Los Angeles. The key risk is that high fixed lease costs and CapEx meet softer demand for traditional formats. In that setup, creative leadership has value, but financial leverage and utilization matter more.
There are no fresh financial announcements tied directly to the IRL Studios move right now. That puts the emphasis back on the existing drivers that analysts already watch closely. These include the pace of digital rollouts, the impact of past restructuring, and whether OUTFRONT Media keeps converting earnings into stronger coverage of interest costs.
Analysts expect earnings to grow 8.8% a year and see the shares trading well below both their price target and some intrinsic value estimates. For that to occur, advertising clients would need to continue using OUTFRONT Media’s digital and programmatic tools. The Jeger hire fits that narrative by aiming to turn those tools into campaigns that justify premium pricing and better asset utilization.
OUTFRONT Media's narrative projects US$2.2b revenue and US$317.7m earnings by 2029. This assumes 4.0% yearly revenue growth and an earnings increase of about 32% from US$241.2m today.
Uncover why OUTFRONT Media's fair value points to a 36% potential upside to its current price, a discount that could narrow quickly.
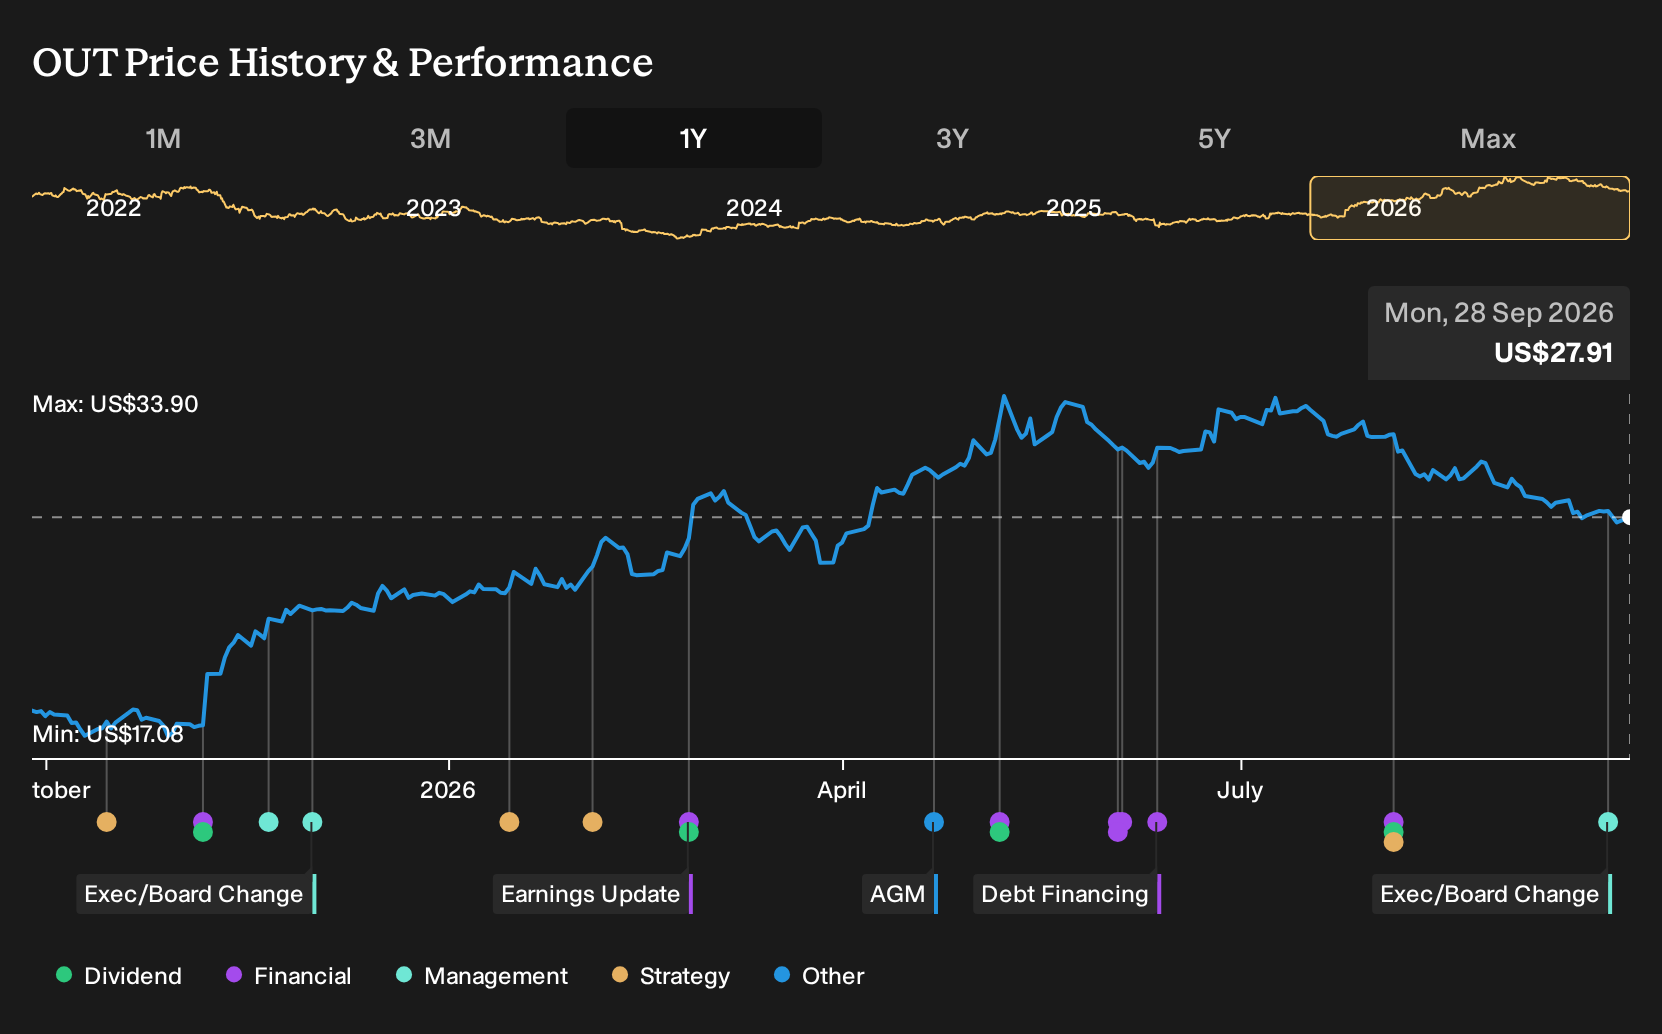
Exploring Other Perspectives
The most optimistic analysts frame OUTFRONT Media around a transit surge. They were already penciling in roughly US$2.2b of revenue and US$342.4m of earnings by 2029 before this hire. You might see the Mariano Jeger appointment as a creative spark that either reinforces that upbeat transit story or forces a rethink.
Explore 2 other OUTFRONT Media fair value estimates, including one that suggests there could be as much as 96% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your OUTFRONT Media research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for OUTFRONT Media. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OUTFRONT Media's overall financial health at a glance.
Looking For More Investment Ideas Beyond OUTFRONT Media?
If the OUTFRONT Media story has you thinking about what else might be mispriced or overlooked, it can help to scan a wider field of companies that share some of the qualities you care about most.
- For investors who want quality at a discount, review a hand picked 33 high quality undervalued stocks that may be trading below what their fundamentals suggest.
- If balance sheet strength is your priority, focus on a targeted list of solid balance sheet and fundamentals (25 results) to find businesses with sturdier finances backing their operations.
- For those who care most about resilience, filter for a curated 30 resilient stocks with low risk scores that screens for companies with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com