
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Aritzia (TSX:ATZ) Joins The FTSE All World Index, Is The Pullback A Buying Opportunity?
Aritzia (TSX:ATZ) just joined the FTSE All-World Index in US dollar terms, a move that can draw fresh attention from global index followers and raise questions about how the stock is currently valued.
Index inclusion comes after a mixed stretch for Aritzia, with the share price up 2.31% year to date but giving back ground recently, including a 23.34% decline over the past 90 days and an 8.26% fall over the past month.
At the same time, longer-term investors have seen very different results, with a 1-year total shareholder return of 38.12% and a 3-year total shareholder return of more than 4x. This signals that momentum has cooled in the short term even as the broader story that pushed Aritzia to CA$119.89 remains in focus.
The FTSE All-World Index add helps explain why attention has returned to the ticker, since index inclusion can shift how global funds assess both its growth potential and the risk profile they assign to the stock.
Scan beyond Aritzia and look for other potential index beneficiaries and momentum resets with our curated list of 7 high quality undervalued stocks.
Aritzia now trades at a steep discount to both analyst targets and intrinsic estimates after that sharp pullback. Is this cautious pricing warranted, or is the market leaning too far to the pessimistic side as the valuation math shows?
Most Popular Narrative: 37% Undervalued
Aritzia's most followed valuation storyline pegs fair value near CA$189.14, which sits well above the CA$119.89 last close and presents the recent pullback as a sizeable gap to that narrative estimate.
Analysts are assuming Aritzia's revenue will grow by 17.7% annually over the next 3 years. Analysts assume that profit margins will increase from 11.4% today to 13.2% in 3 years time.
See why 64 investors see Aritzia as 37% undervalued.
Result: Fair Value of CA$189.14 (UNDERVALUED)
Still, that narrative faces pressure if Aritzia's U.S. boutique rollout underperforms, or if higher marketing and expansion costs squeeze the margin progress analysts are baking in.
Find out about the key risks to this Aritzia narrative.
Another Take On Aritzia’s Valuation
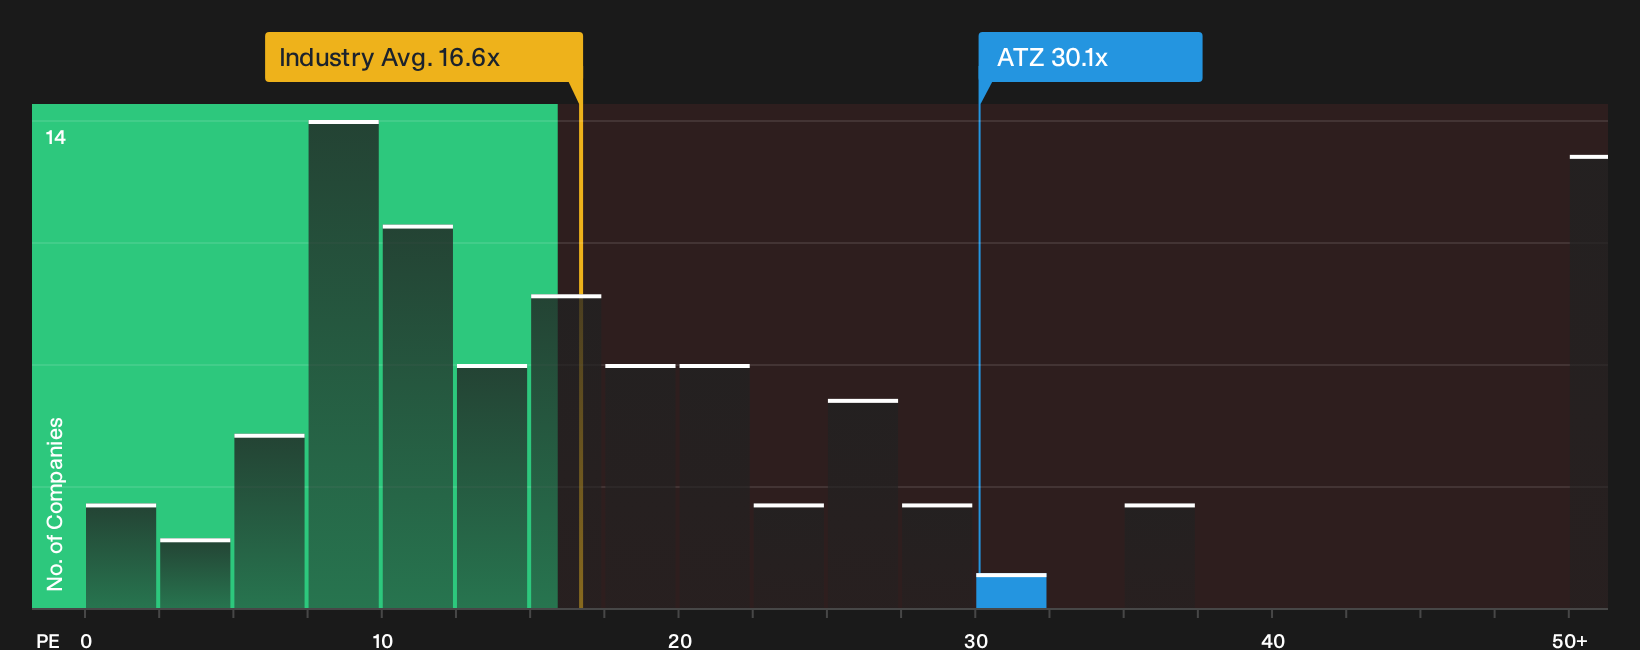
The story looks very different once price is compared with earnings. Aritzia trades on a P/E of 30.1x, which is far richer than the North American Specialty Retail average of 16.6x and slightly above its own 28.1x fair ratio estimate. That premium can reflect quality, or it can leave less room for mistakes if growth expectations ease.
For a closer look at how the current P/E compares with peers and that fair ratio, have a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Aritzia leaves you unsure, take time to examine the numbers yourself and pressure test the bullish angles. Then weigh those findings against the 4 key rewards
Looking for more investment ideas beyond Aritzia?
Put what you have learned from Aritzia to work. Test your thinking against fresh opportunities so you are not relying on a single story or sector.
- Target higher yield potential and assess income-focused opportunities using our list of 1 dividend fortresses.
- Hunt for quality at a discount by checking companies that screen well on valuation with the 7 high quality undervalued stocks.
- Reduce portfolio stress and prioritize resilience by scanning companies on the 8 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com