
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Wyndham Hotels & Resorts (WH) Expands In Luxury And Türkiye, Is The Stock Still Cheap?
Wyndham Hotels & Resorts (WH) has been active on the development front, introducing its upper upscale Dolce Nova concept, signing a luxury resort agreement in Udaipur, and adding new Wyndham Garden properties in Türkiye. These moves give investors fresh expansion milestones to track.
Despite the expansion headlines, Wyndham Hotels & Resorts shares have been under pressure, with the 90 day share price return down 15.89% and the 1 year total shareholder return down 10.48%. The 3 year total shareholder return of 10.48% points to a more mixed longer term picture, where recent momentum has faded.
Scan beyond Wyndham Hotels & Resorts and compare its recent pullback against a hand picked 33 high quality undervalued stocks that also pair expansion plans with solid fundamentals.
The share slide contrasts with growing revenue and net income, raising a blunt question about Wyndham Hotels & Resorts: Are investors reacting to weakening fundamentals, or has sentiment simply swung further than the underlying business justifies?
Most Popular Narrative: 29% Undervalued
Wyndham Hotels & Resorts last closed at $70.83, while the most followed narrative pegs fair value around $100.18. This frames the recent share pullback as a disconnect between price and long term cash flow assumptions built on a 9.56% discount rate.
Enhanced technology initiatives, including the rollout of AI-driven guest engagement, centralized Wi-Fi, and integrated booking/loyalty platforms, address growing consumer demand for branded, consistent asset-light lodging and should increase direct bookings, lower distribution costs, and support margin and earnings expansion over the long term.
See why 2 investors see Wyndham Hotels & Resorts as 29% undervalued.
Result: Fair Value of $100.18 (UNDERVALUED)
Still, Wyndham Hotels & Resorts faces real pressure points, including potential U.S. RevPAR softness and rising competition from alternative accommodations that could strain fees and brand power.
Find out about the key risks to this Wyndham Hotels & Resorts narrative.
Another View: What Wyndham Hotels & Resorts’ P/E Is Signaling
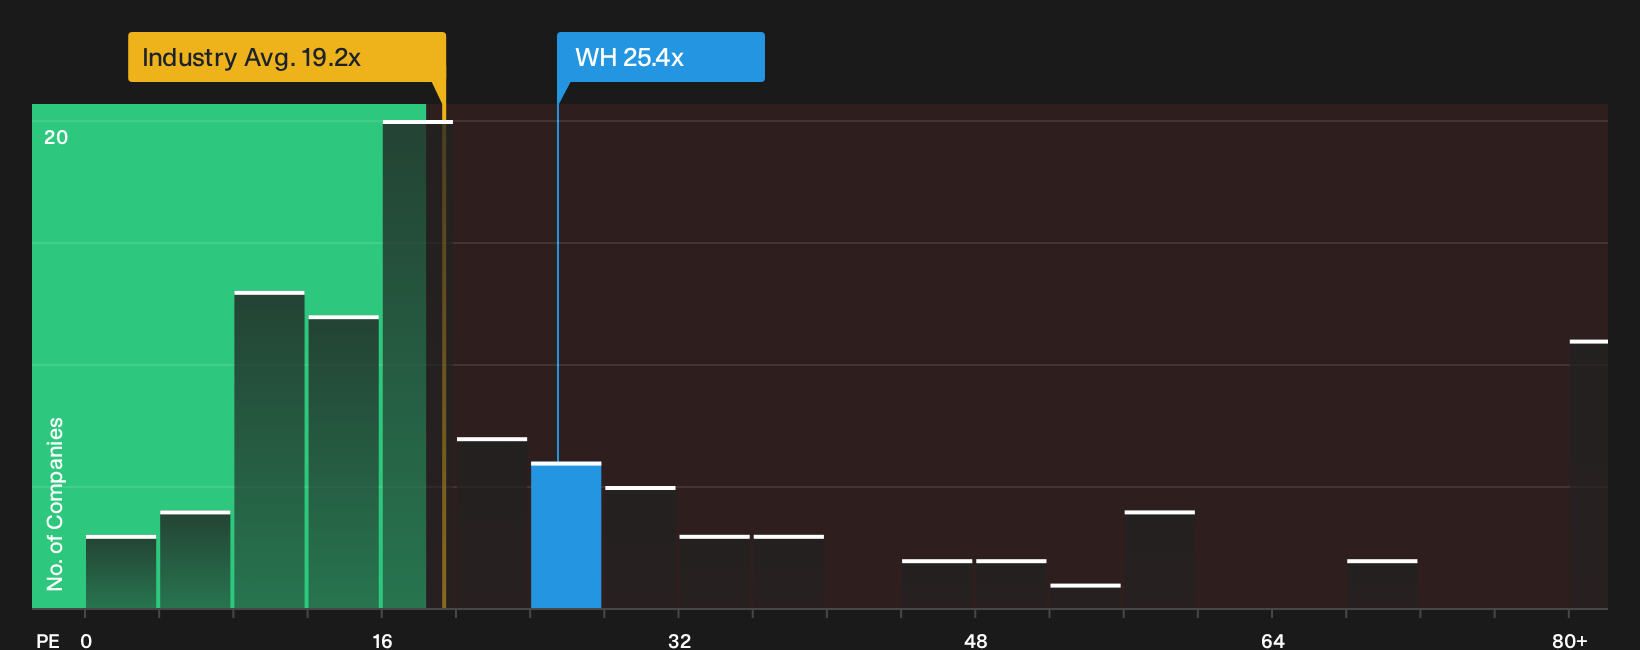
The fair value narrative around Wyndham Hotels & Resorts leans on long term cash flow, yet the current P/E ratio of 25.4x tells a different story. That multiple sits above both the US Hospitality industry at 19.2x and peers at 23.9x, and it also exceeds a fair ratio of 22.6x. This suggests the market could shift toward a lower earnings multiple over time. For investors, that gap can raise the risk that sentiment, not fundamentals, is doing more of the heavy lifting than the earlier valuation implies.
To pressure test that view against hard numbers, take a closer look at our valuation breakdown, including how the current earnings multiple stacks up against the fair ratio and sector peers, through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Wyndham Hotels & Resorts can make the story feel unclear, so move quickly, review the full data set, and decide where you stand using the 3 key rewards and 4 important warning signs.
Looking for more Wyndham Hotels & Resorts investment ideas?
If you are unsure about committing fresh capital to Wyndham Hotels & Resorts right now, consider broadening your watchlist with a few targeted stock ideas that match your risk and income preferences.
- Search for potential bargain opportunities by scanning companies that combine quality fundamentals with undemanding valuations through the 33 high quality undervalued stocks.
- Strengthen the income side of your portfolio by reviewing a focused set of higher-yielding payers via the 6 dividend fortresses.
- Dial down risk by filtering for businesses with healthier finances and sturdier balance sheets using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com