
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Northrail Locomotive Deal Will Impact Alstom (ENXTPA:ALO) Investors
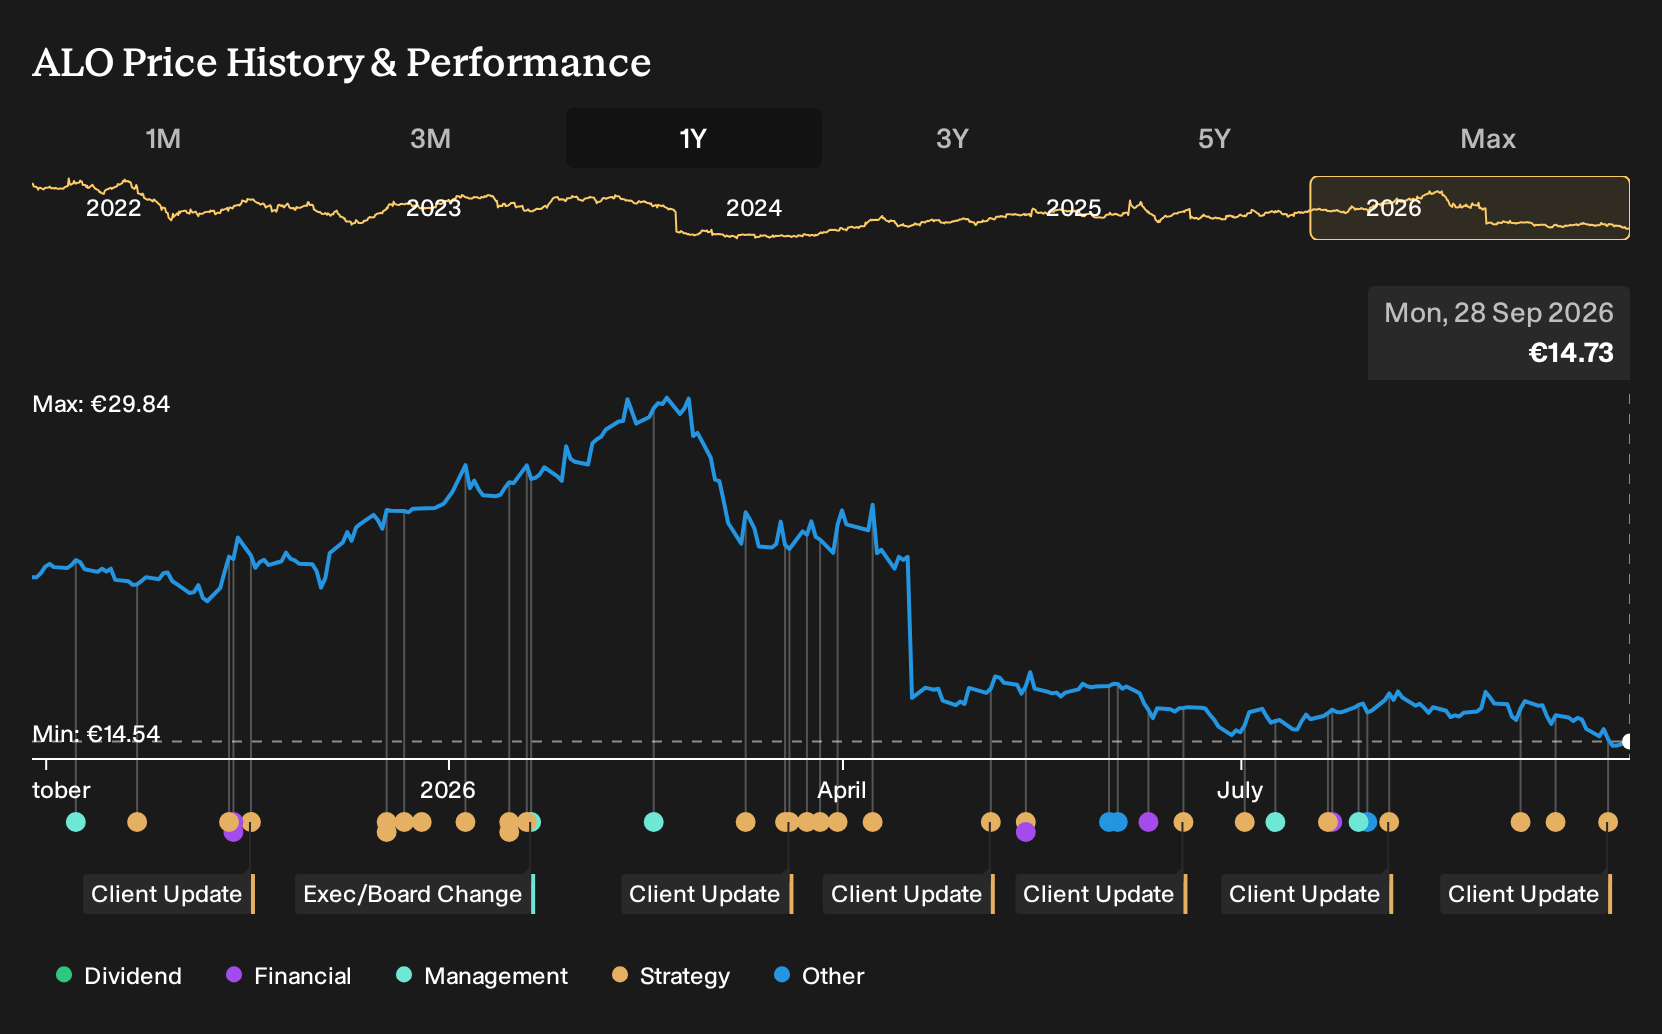
- Alstom and Northrail announced a framework agreement in September 2026 for up to 100 Traxx Shunter locomotives, with a firm order and 10 years of maintenance in Germany worth just under €100 million, and potential options lifting the total value to about €700 million including longer term service.
- The locomotives will be designed and assembled at Alstom’s Belfort centre of excellence and supported by long duration maintenance contracts, which points to a mix of manufacturing activity and recurring service revenue that matters for margins and capacity planning.
- The focus now shifts to how this sizeable Traxx Shunter framework with Northrail could reshape Alstom’s investment narrative around order quality and services.
Scan how this Alstom order fits within a wider rail and infrastructure theme by reviewing a hand-picked 39 power grid technology and infrastructure stocks that could benefit from similar long-term transport and energy upgrades.
Alstom Investment Narrative Recap
To own Alstom, you need to believe that a large installed base, a long project pipeline and a heavier tilt toward services can outweigh legacy contracts, supply bottlenecks and working capital strain. The Northrail locomotives and maintenance deal fits that story because it combines fresh hardware with recurring service work that can support margin repair if executed cleanly.
The near term swing factor still looks like project delivery and cash conversion, not this single framework. Production delays, immature supply chains around newer technologies and low margin backlog remain the key risk. If those pressures worsen, even attractive new orders become less helpful for earnings quality and balance sheet flexibility.
The Canadian Indigenous supplier registration portal is the clearest link to the same theme that runs through the Northrail agreement. Both point to Alstom trying to build deeper customer and supplier relationships around long duration contracts, from locomotives in Germany to subway and long distance fleet work in Canada.
For you as a shareholder, that matters because execution on these ecosystem style initiatives can influence win rates on future tenders and the mix of higher margin services that analysts already view as a core catalyst. Any slip in supplier depth or project delivery, especially on large Canadian programs, feeds back into the same risk set that investors are tracking in Europe.
Alstom's current analyst storyline points to revenues of €22.4b and earnings of €877.3m by 2029, based on an assumed 5.4% yearly revenue growth rate and an earnings increase of about €598.3m from €279.0m today.
Uncover why Alstom's fair value indicates a 43% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One contrasting catalyst in the bullish Alstom narrative is how aggressively some analysts were already baking in premium services growth. Before this Northrail deal, the most optimistic forecasts were calling for about €23.3b of revenue and €958.0m of earnings by 2029. You can treat those as one end of the opinion spectrum and decide whether this latest contract pushes expectations closer to that camp or not.
Explore 4 other Alstom fair value estimates, including one that suggests as much as 90% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Alstom research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alstom. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alstom's overall financial health at a glance.
Looking for more Alstom style investment ideas?
If this Alstom story has you thinking about where else long term themes and solid fundamentals might show up, the Simply Wall St Screener can help you quickly filter the market into a focused shortlist that matches your own risk and return preferences.
- For investors who care most about quality at a sensible entry point, scan a 198 high quality undervalued stocks that combine fundamentals with pricing that some might view as appealing on a risk adjusted basis.
- If resilience and balance sheet strength sit at the top of your checklist, narrow the field to a list of solid balance sheet and fundamentals (202 results) that may better handle funding cycles and project delays.
- Income focused investors can concentrate on payout durability by reviewing a 166 dividend fortresses that aim to pair higher yields with business models built for regular distributions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com