
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Raised Guidance Change Awa Bank Stock Narrative
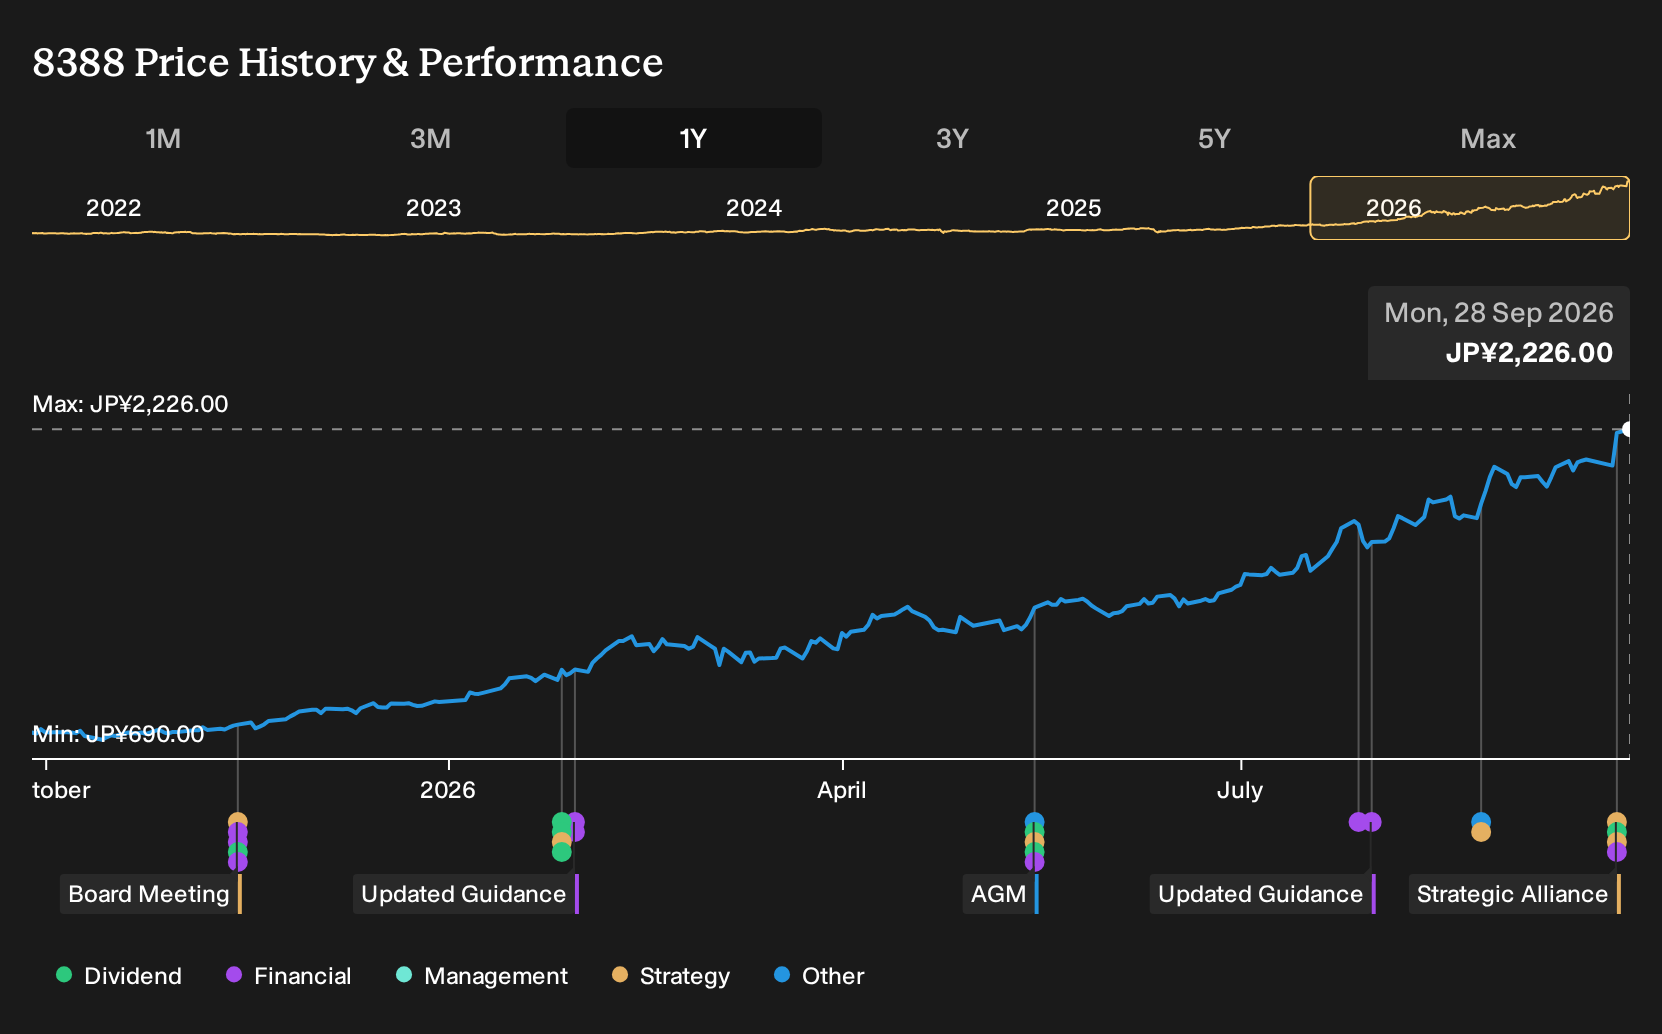
- Awa Bank raised its consolidated and non consolidated earnings guidance for the year ending March 31, 2027, and lifted its full year dividend forecast to ¥22.00 per share, along with a planned 5 for 1 share split effective October 1, 2026.
- The lender also approved a capital and business alliance tying Awagin Connect with Shikoku Broadcasting, aiming to support regional companies through e commerce, content production, and broader sales channel development in Tokushima.
- The focus now turns to how Awa Bank's higher earnings guidance might reshape the investment narrative that investors use to judge the stock.
What Is Awa Bank's Investment Narrative?
The big belief around Awa Bank is pretty simple. You need to trust that a regional lender can keep turning consistent earnings into shareholder returns while managing credit risk in a conservative way. The raised guidance to ordinary revenue of ¥134,800 million and profit of ¥20,000 million, plus higher EPS, points to management confidence in the current operations. The richer dividend forecast and 5 for 1 split speak to a shareholder friendly stance, yet they also increase pressure to keep cash generation steady.
In the short term, the key swing factors are credit quality, funding costs and the ability to translate the Awagin Connect and Shikoku Broadcasting alliance into fee income rather than just PR. Earnings have grown historically and the stock has moved strongly over 1 year, but the P/E of 24.6x versus the JP banks average of 16x means investors already pay up for that story. High bad loans at 2% and a low 37% allowance keep asset quality in focus as the dividend steps up.
That said, there is still one uncomfortable angle in the Awa Bank story that only really shows up when you look closely at ...
There's only one way to know the right time to buy, sell or hold Awa Bank. Head to Simply Wall St's company report for the latest analysis of Awa Bank's Fair Value.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Awa Bank research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Awa Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Awa Bank's overall financial health at a glance.
Looking For More Ideas Beyond Awa Bank?
If this update on Awa Bank has sharpened your thinking, it can be useful to compare it with other businesses that share similar financial traits. The Simply Wall St Screener lets you quickly surface stocks that fit the type of balance sheet strength, yield profile, or valuation tilt you care about most.
- For investors who want income that does not completely ignore quality, scan a group of income focused stocks through 22 dividend fortresses that may offer yields supported by underlying fundamentals.
- If capital preservation sits high on your checklist, filter for companies that score well on resilience and financial risk using the 20 resilient stocks with low risk scores to see which ones match that profile.
- When you are hunting for financially sound businesses with room to run, cast a wider net over a 74 high quality undiscovered gems that might not yet be widely followed but still show solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com