
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Indian Growth Stocks With Up To 58% Earnings Growth
Indian equities just saw a sharp sell off as the Sensex fell over 1,000 points and the Nifty50 slid below 22,850, which often pushes investors toward safety and away from growth ideas. That kind of broad retreat can create openings in fast growing businesses where insiders already have meaningful skin in the game. This article highlights three such high growth, high insider ownership stocks that investors may want to keep on their watchlist.
The three stocks below are only a starting sample. The full screen surfaced 106 more companies with similarly strong growth profiles and insider alignment that are not covered here.
If you want to identify and analyze more ideas with this profile, head straight to the Fast Growing Stocks With High Insider Ownership screener.
Rubicon Research (NSEI:RUBICON)
Overview: Rubicon Research is a specialty pharmaceutical developer focused on differentiated drug delivery platforms like RubiReten and RubiSRL across high-growth therapeutic areas.
Operations: Rubicon Research generates around ₹19,358 million in revenue from pharmaceutical products including generics, specialty formulations, APIs and related services.
Market Cap: ₹263.66 billion
Rubicon Research fits this screener because its proprietary drug delivery platforms sit alongside a management team and analyst community that both expect significant expansion from a growing speciality portfolio.
"Consistent R&D investment at roughly 10% to 11% of revenue, together with a track record of commercialising 88% of approved products, points to a deeper product basket that can support future revenue and earnings visibility."
The real swing factor is how one pressure on future pricing power plays out as the product mix tilts further toward complex therapies.
That pricing wildcard is exactly what makes the full narrative for Rubicon Research so important for judging how Rubicon Research could convert its R&D engine into durable, higher margin earnings power.

Astra Microwave Products (BSE:532493)
Overview: Astra Microwave Products designs and manufactures radar and radio frequency sub-systems for defense, space, meteorology, civil, and telecom customers in India.
Operations: Astra Microwave Products generates about ₹11,397 million in revenue from radio frequency and microwave products across its defense and space focused portfolio.
Market Cap: ₹151 billion
Astra Microwave Products plugs into this fast growing, high insider ownership theme through its radar and RF electronics. These products feed directly into long-cycle defense and space programs where management and insiders see a multi-year opportunity.
"Intensifying global adoption of commercial-off-the-shelf (COTS) solutions threatens Astra's future ability to win key defense and space contracts, undermining its core value proposition and eroding both revenues and future pricing power as end-customers opt for standardized, lower-cost alternatives."
What happens to Astra Microwave Products’ growth story depends heavily on how one underappreciated swing factor shapes demand and pricing power.
That pricing wildcard is exactly why the full narrative for Astra Microwave Products explores how Astra Microwave Products could still convert contract risk into accelerating long term earnings power.

Bajel Projects (NSEI:BAJEL)
Overview: Bajel Projects delivers turnkey EPC solutions for extra high voltage transmission lines and substations that support large scale electrification.
Operations: Bajel Projects generates about ₹27,508 million in revenue from power transmission and distribution EPC contracts and related infrastructure solutions.
Market Cap: ₹19.6 billion
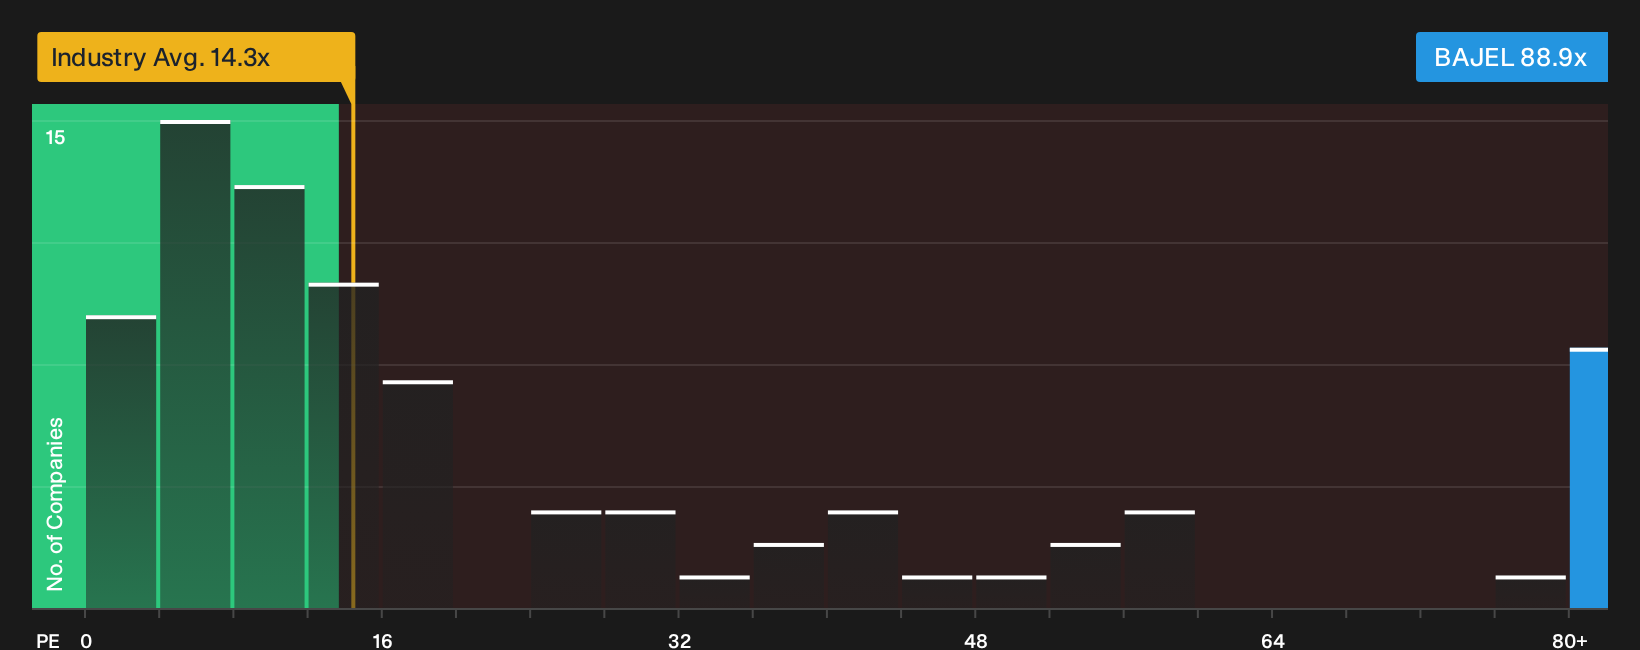
Bajel Projects aligns with this screener theme, with earnings forecast around 57.7% a year and revenue expected to advance about 27% annually from a growing book of ultra high voltage EPC work. The share price already reflects much of this optimism at an 88.9x P/E, so outcomes may depend significantly on how current funding pressures affect returns on these large projects.
That funding question makes the analysis report for Bajel Projects a quick way to see whether Bajel Projects’ rich P/E lines up with its project pipeline risk and reward.
Seeking Alternatives Before The Crowd Moves
Fresh opportunities can move from quiet to flying fast once momentum builds and prices start breaking out. Scan these under the radar ideas before the crowd and consider acting while conditions remain favorable.
- Target sturdier income streams by reviewing companies in the 166 dividend fortresses while yields still look appealing and prices have not fully caught up.
- Spot early pricing power by tracking the list of solid balance sheet and fundamentals (202 results) before stronger fundamentals get fully reflected in valuations and entry points start dropping away.
- Follow emerging infrastructure and electrification themes by scanning the 39 power grid technology and infrastructure stocks before capital flows concentrate on a limited group of tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com