
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Keysight Technologies (KEYS) Is Getting Attention Now
Keysight Technologies (KEYS) just tied its future a little closer to 6G research by backing a new over the air testing project at UC Berkeley’s Berkeley Wireless Research Center.
Keysight Technologies has ridden strong momentum into this collaboration, with the share price at US$359.74 and a year to date share price return of 74.13% alongside a 1 year total shareholder return of 107.61%. This comes even as the 1 day share price return declined 0.67% after a 12.43% 30 day gain, hinting that investors are weighing rapid recent gains against how much long term 6G exposure is already reflected in the valuation.
Scan beyond Keysight Technologies and spot other potential beneficiaries of the 6G and advanced testing build out with our hand picked 84 AI infrastructure stocks.
After a 74% year to date run and fresh 6G buzz around Keysight Technologies, the question now is whether the current price still offers a favourable trade off between risk and potential reward as valuation comes into focus.
Most Popular Narrative: 13% Undervalued
Keysight Technologies is trading at $359.74 against a widely followed fair value estimate of about $415, so the valuation debate now hinges on whether its earnings and cash flows can live up to that gap.
Adoption of AI across digital infrastructure is accelerating demand for advanced testing solutions in compute, memory, networking, and interconnect. Keysight's AI-focused investments have led to double-digit wireline and commercial communications growth. This trend is expected to influence top-line revenue as AI workloads expand into new customer segments and applications over the coming years.
See why 18 investors see Keysight Technologies as 13% undervalued.
Result: Fair Value of $415.08 (UNDERVALUED)
Still, the Keysight Technologies story can crack if new tariffs hit margins harder than planned or if AI driven test demand cools faster than analysts expect.
Find out about the key risks to this Keysight Technologies narrative.
Another View on Keysight Technologies Valuation
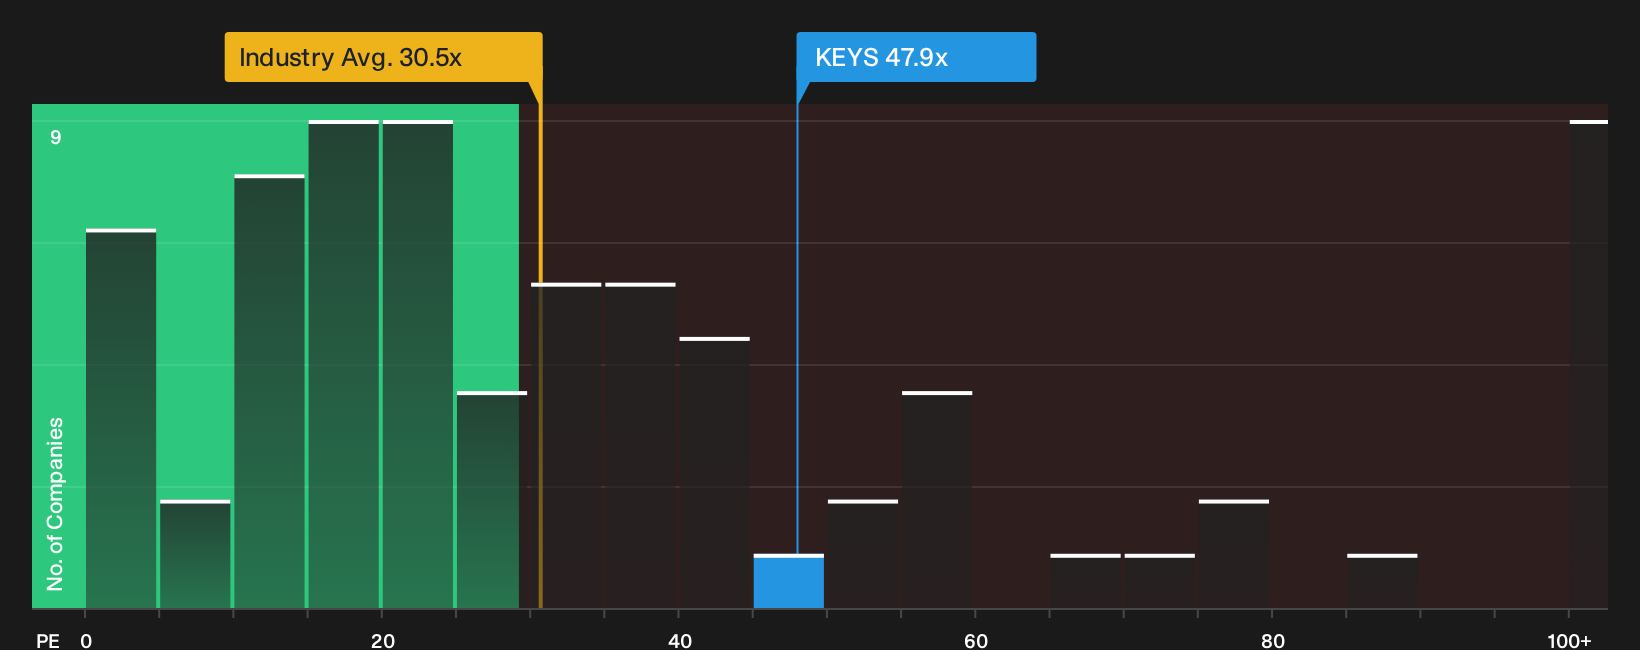
While the analyst fair value of about $415 points to Keysight Technologies trading at roughly a 1.8% discount, the current P/E of 47.9x tells a tougher story. That multiple is higher than the US Electronic industry at 30.5x, peers at 42.2x, and the fair ratio of 35.4x. This suggests less margin for error if growth or margins fall short. Which signal do you trust more when risk appetite tightens?
For a closer look at how this pricing compares with underlying earnings power, have a look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Keysight Technologies valuation and sentiment can be confusing. Move quickly, test the data yourself, and weigh both sides of the story by checking the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Keysight Technologies?
If Keysight Technologies has sharpened your interest, do not stop here. Cast a wider net now so you are not chasing opportunities after they move.
- Target underappreciated quality by scanning a focused list of companies that pair solid fundamentals with attractive pricing through the 16 high quality undiscovered gems.
- Strengthen portfolio resilience by screening for businesses with clean finances and dependable fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Zero in on potential mispricings by reviewing a curated group of attractively valued opportunities via the 33 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com