
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can CBIZ (CBZ) Justify Its Price Following This Interim Accounting Services Win?
CBIZ (CBZ) drew fresh attention after Enhanced Group Inc. said the firm will handle interim accounting and financial reporting while the client searches for a new principal accounting officer, with services reporting directly to its CFO.
For context, CBIZ shares trade at US$54.71, and while the 90-day share price return of 70.54% signals strong recent momentum, the 5-year total shareholder return of 63.95% points to a steadier longer-term journey that this fresh mandate may now be feeding into as investors reassess both growth potential and execution risk.
Spot opportunities with a similar profile to CBIZ by scanning our handpicked list of 33 high quality undervalued stocks, which may also be priced below what their fundamentals imply.CBIZ looks like a solid operator with fresh contract wins and long-running client ties, yet a 70% 90 day surge raises a sharper issue. Are you paying a fair price for that quality today?
Most Popular Narrative: 6% Overvalued
The most followed CBIZ valuation story pegs fair value at about $51.67 using an 8.6% discount rate. This sits below the $54.71 share price and frames that 90 day surge against a slightly richer tag.
The Marcum acquisition has significantly expanded CBIZ's client base, increased scale, and strengthened capabilities in core tax, accounting, and advisory services, enabling the firm to leverage cross-selling, deepen client relationships, and improve its competitive position in target middle-market segments; this is expected to fuel higher future revenue growth and structural margin expansion as integration synergies are realized.
See why 10 investors see CBIZ as 6% overvalued.
Result: Fair Value of $51.67 (OVERVALUED)
Still, CBIZ carries real pressure points, including integration risks from the Marcum deal and elevated leverage that could squeeze flexibility if conditions turn.
Find out about the key risks to this CBIZ narrative.
Another View On CBIZ Valuation
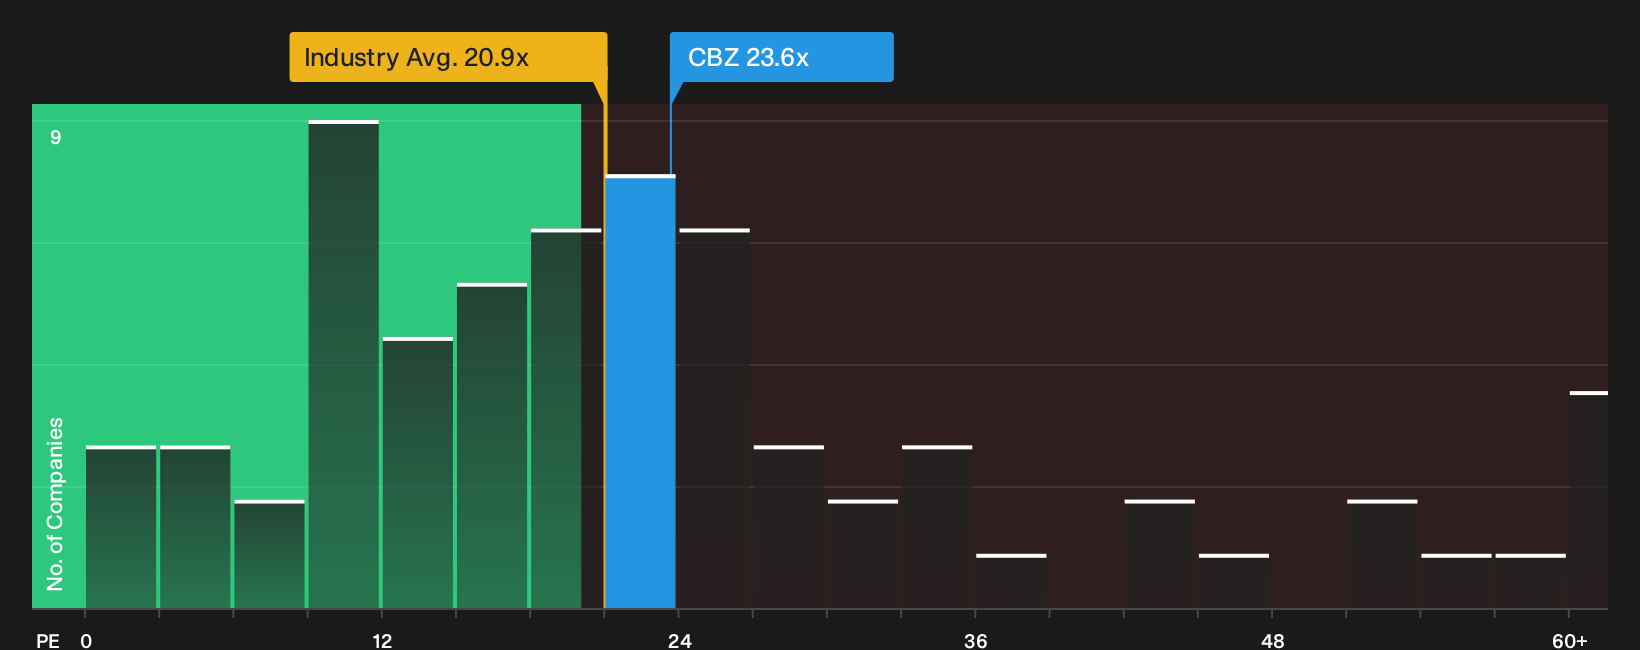
On simple earnings multiples, CBIZ tells a different story. The shares trade on a P/E of 23.6x, which is richer than both the peer average at 21x and the wider US Professional Services group at 20.9x, yet still below a fair ratio estimate of 26.7x.
That gap implies the stock carries some valuation stretch versus similar businesses, while still sitting under where the fair ratio suggests the market could migrate. Is that extra premium a warning on downside risk or a price of entry for perceived quality and growth?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and concern around CBIZ leaves you uncertain, take a closer look now and develop your own view with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CBIZ?
CBIZ may be front of mind today, but your next opportunity could be sitting in a very different corner of the market. Do not leave that on the table.
- Hunt for quality at a discount by reviewing companies that appear mispriced on fundamentals through the 33 high quality undervalued stocks.
- Prioritize resilience and capital protection by filtering for businesses with robust finances using the list of solid balance sheet and fundamentals (25 results).
- Seek out underfollowed potential by scanning our 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com